2026
The Italy Market Report 2026, published by Engel & Völkers, has been developed in collaboration with, and with the scientific support of, Nomisma.

2026
The Italy Market Report 2026, published by Engel & Völkers, has been developed in collaboration with, and with the scientific support of, Nomisma.
Index
07
EDITORIAL
10
12
ITALY'S PRIME MARKET NORTHWESTERN
74
92
ITALY'S PRIME MARKET CENTRAL IMPRESSUM
ITALY'S PRIME MARKET SOUTHERN AND THE ISLANDS
122
Being recognizable in the premium real estate market means having the clarity to read the present and the ability to anticipate its direction. This is the approach through which Engel & Völkers observes and interprets the market, strengthening its role as a benchmark at both national and international levels.
Within this perspective, we present the second edition of the Italy Market Report, developed in collaboration with Nomisma, an economic research company. This project has, from its very first year, established itself as a concrete and valuable tool, supporting brokerage activities and serving as an authoritative document for interpreting and communicating market trends.
The mid-to-high and high-end real estate segment in Italy is experiencing a phase of significant growth, driven by both domestic and international investments. Demand is diversified across primary residences, second homes and increasingly structured investment strategies, with an international component that now accounts for an average of 35% of buyers, confirming the value of premium real estate as a solid and strategic asset.
In this context, the Market Report takes on a central role: not only as a snapshot of the market, but as a tool capable of providing meaningful insights to guide decisions and strategies. At the same time, the investor profile is evolving, becoming more informed and increasingly attentive to service quality, process reliability, and data protection. Transparency and due diligence are now essential elements, reducing uncertainty and ensuring reliability at every stage.
There is also a growing awareness of the value of relying on a structured global player present in 36 countries, such as Engel & Völkers. Access to an international client base, economies of scale, and the maximization of property visibility translate into greater efficiency, a higher probability of sale, and improved price positioning.
The Italy Market Report is rooted in this vision: it is not only an analytical tool, but a concrete instrument to operate with cohesion across the entire country, ensuring a consistently high standard of quality. The growth of Engel & Völkers in Italy reflects these dynamics, within a context that today offers significant opportunities for those aiming to operate in the premium segment with an international outlook.
The Report responds to an ambitious objective: to be not only a point of observation, but of interpretation; not just a reading tool, but a true benchmark for the market.
Muhannad Al Salhi CEO Engel & Völkers Italia
Founded in Hamburg in 1977 by Dirk C. Engel and Christian Völkers, Engel & Völkers was born from a clear vision: to redefine real estate brokerage through quality, expertise and a distinctive positioning within the premium segment. An approach that, over time, has helped transform the Brand into one of the leading international references in luxury real estate.
The growth of Engel & Völkers has been built on a scalable and consistent model, based on the integration of local presence and global vision. Today, the network operates in more than 36 countries across five continents, with over 1,100 locations and a team of more than 16,700 professionals. A steady expansion that reflects not only the Brand’s geographical reach, but also its ability to attract and enhance highly qualified human capital.
Over the past two years, in Italy, the Group has confirmed a solid and continuous growth path, with more than 100 locations and over 1,300 professionals active across the
country. New openings recorded in the past year demonstrate a selective growth strategy, aimed at strengthening presence in key destinations and enhancing the quality of territorial coverage, supported by a structured marketing and communication approach that defines its positioning.
Engel & Völkers reached €100 million in revenue in Italy in 2025, contributing to a global result exceeding €1.3 billion, marking growth compared to the previous year. This figure highlights the strength of the operating model and the Brand’s ability to maintain positive performance even within a rapidly evolving global landscape.
With 49 years of experience and approaching its fiftieth anniversary, Engel & Völkers continues to consolidate its positioning in Italy through a structured international network, achieving an average annual growth of up to 20% over the past 24 months and an increasingly qualified presence in the markets in which it operates.
36
1.100 Countries Global Offices
16.700 1,3
€ billions
People at Engel & Völkers
Revenue 2025
The international economic landscape is marked by strong instability due to geopolitical tensions between the United States, Israel, and Iran, which have rekindled fears of a new energy crisis and fuelled market volatility. Global growth remains moderate and stable at around 3.3%, but market expectations are shifting toward a possible recession, while the Federal Reserve's credibility is weakened by domestic political pressure. In this context, uncertainty remains high and is reflected in increased demand for assets considered safe.
In Italy, the situation is characterized by weaker growth than in previous years but still higher than in Germany, and by a resilient labour market, with employment at record highs and unemployment at historic lows. However, the country remains exposed to the effects of international instability: the risk of renewed inflation could further erode household purchasing power and dampen consumption and investment. The combination of moderate growth, potential inflationary pressures, and energy dependence makes the overall picture fragile.
Since the end of 2025, the real estate market has shown signs of growth. Low inflation, the recovery of household purchasing power, and lower mortgage interest rates compared to the recent past have favoured an increase in capital provided by banks to support home purchases and the continued growth in sales. Beginning in 2024 Q3, the residential market began to grow again, albeit at a moderate pace, supported by the progressive reduction in interest rates. This positive trend
Residential sales in Italy (thousand)
continued throughout 2025, further consolidating in H1, when sales recorded an annual increase of 9.3%. During 2025 H2, the trend normalized, bringing the annual final figure to an overall growth of 6.3%, confirming a solid but more balanced expansion cycle compared to the initial surge (Fig. 1).
According to Nomisma's forecasts prepared in December 2025, at the end of the three-year forecast period (20262028), sales are expected to reach 785,000, close to those recorded in 2022 during the strong post-pandemic recovery. This confirms the positive phase of a market that remains significantly higher than the pre-pandemic years, when the market stood at around 600,000 transactions annually.
This outlook places the market at a high level of dynamism, especially when compared to the past: we need to go back to the period preceding the dual sub-prime mortgage crisis (2008) and sovereign debt crisis (2011) to find similar levels of activity, when the threshold of 800,000 transactions was exceeded.
The current expansionary phase of transactions in the residential market is contributing to the dynamics of property prices, evidenced by positive growth rates in nominal values, as has been the case continuously since 2021.
In 2025, the residential market continued its growth path, albeit at a more moderate pace than in previous years. The prices of properties in excellent condition increased by 1.3%, while those in good condition increased by 1.9%, confirming a positive trend but gradually slowing compared
to the two-year period 2022–2023. The more marked growth for properties in less valuable condition suggests greater pressure from demand in that market segment.
Over the forecast period, however, the intensity of price growth is expected to gradually decrease, with an annual growth rate of +1.0% in 2026 for the average of the largest cities, following the +1.4% recorded in 2025.
The slowdown in real estate price growth will not suffice to offset the increase in inflation. As a result, property prices will decline in real terms, with the reduction tending to increase over the three-year forecast period .
The home loans market in 2025 confirmed the consolidation of the recovery that began at the end of 2024. Following two years of sharp contractions in lending, the improvement in monetary conditions—fostered by the ECB's four, 25-basis-point cuts in key interest rates between January 2025 and February 2026—has fostered a return to demand and a stabilization of bank rates.
In terms of amount disbursed, in 2025 Q3 (latest available data), the volume of new home loans disbursed stood at around €35.9 billion, marking a significant rebound of +30.8% over the same period in 2024 (Figure 3). This result is primarily attributable to Q1 and Q2, which recorded yearon-year increases of 47.2% and 29.8%, respectively, over the same quarter of the previous year.
At the regional level, Central Italy, along with Rome, contributed most to the increase in new home loans (+44.6% annually). The Northeast follows with +36.8%, and the Northwest and South with similar increases of around 34%.
Forecasts prepared by Nomisma in December 2025 show new home loans growing at around 2% annually over the next three years, gradually bringing volumes back to levels close to €53 billion, in line with 2021 and 2022.
ENGEL & VÖLKERS MARKETS
INTERNATIONAL DEMAND (OVER PREVIOUS YEAR)
25 TOP PRICE 2025
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
69%
Source: Istat e Engel & Völkers
INVESTMENT PURCHASES
12 %
The Northwestern prime market confirms its excellent positioning, driven by lakeside, mountainous, and urban destinations with high international appeal. The top values reflect the demand for exclusive properties in prime locations.
In Valle d'Aosta, Courmayeur confirms the growth trend in the prime segment, with top prices of €20,000 per sqm for high-end properties, appreciated for their exclusivity, Alpine lifestyle, and year-round liveability. Breuil-Cervinia records top prices of €15,000 per sqm, reflecting the strong demand for new or renovated properties in prime locations, with a focus on amenities and mountain views.
In Piedmont, the Langhe, Alba, and Roero regions maintain a prestigious position linked to the food and wine lifestyle and quality of life. The top prices of the most exclusive properties have reached €3,000 per sqm, with particular interest for farmhouses and villas with gardens, privacy, and panoramic views. International clients, especially
27,000 €
PURCHASES WITHOUT HOME LOAN
66 %
North Americans, recognize the region as an alternative to Tuscany, valuing the bucolic lifestyle without sacrificing elite services. Asti and Monferrato exhibit similar dynamics, with a market that favours renovated properties in panoramic locations. The top price stands at €3,500 per sqm, driven by high-quality tourism and private investors attracted by the long seasonality and potential for property development. Cuneo confirms its interest in renovated properties, with top prices around €4,800 per sqm for prime villas and farmhouses, in natural settings attractive in both winter and summer. Energy efficiency and the liveability of homes remain key factors in demand.
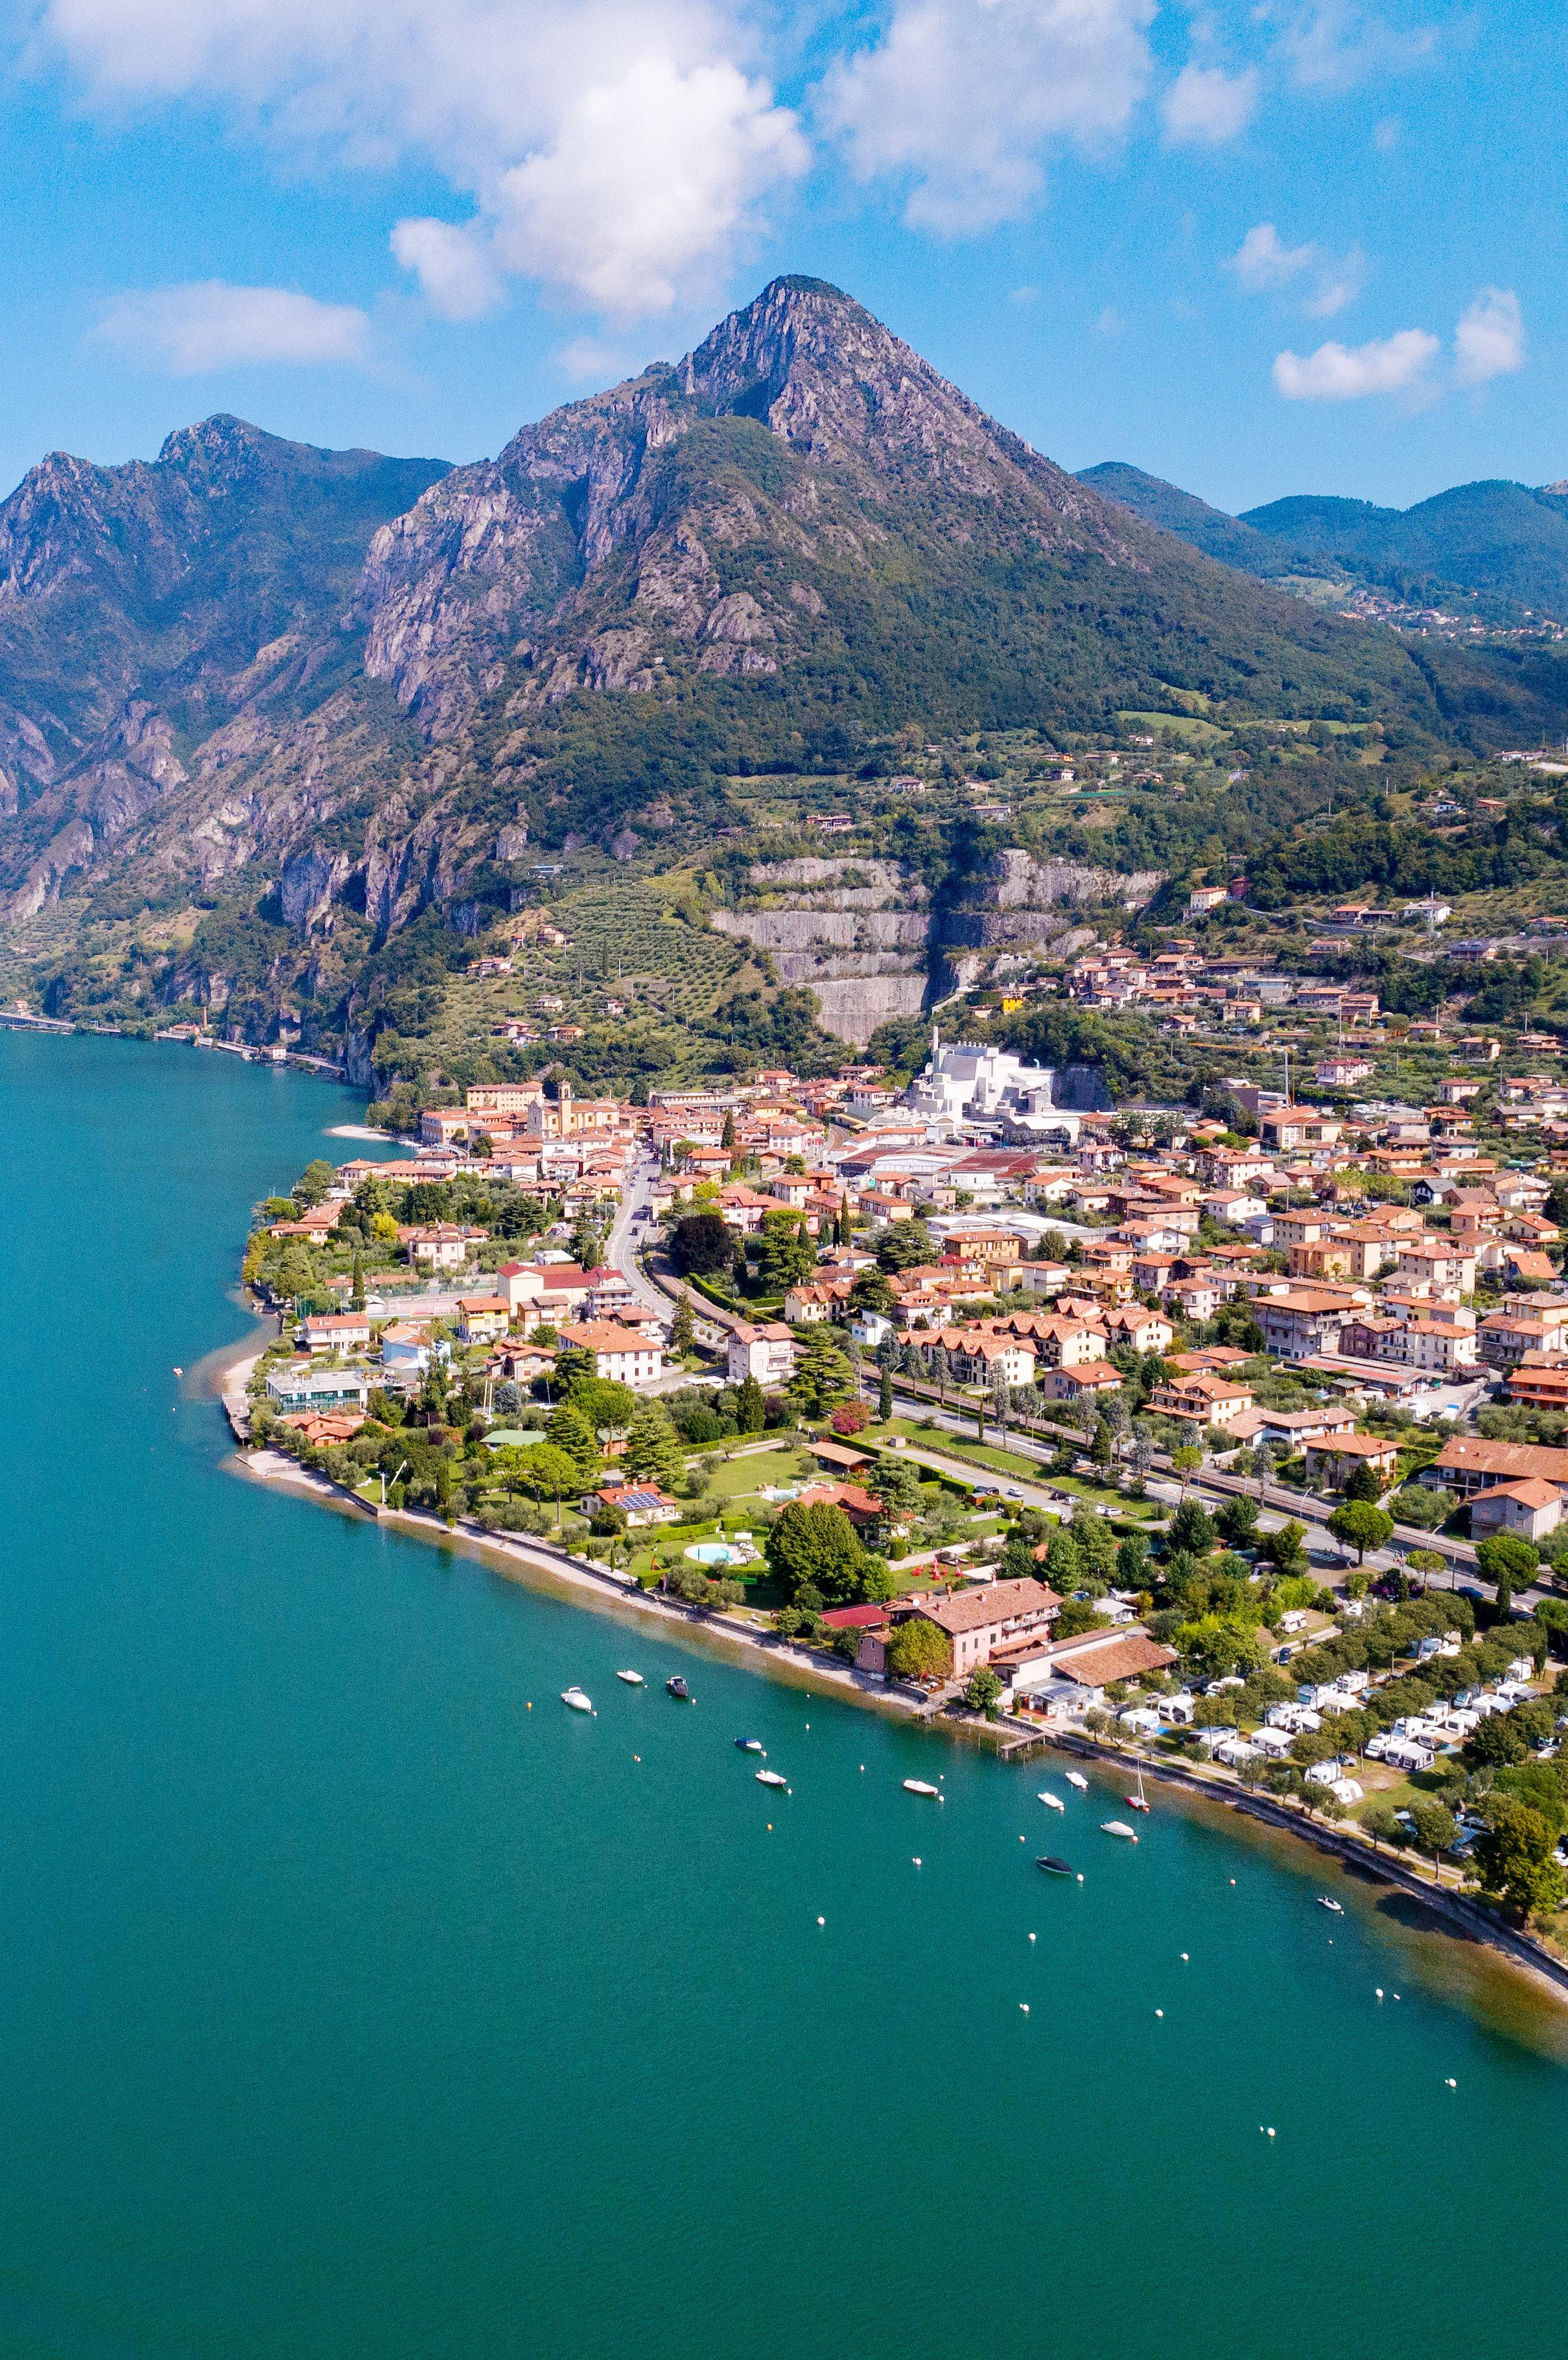
In Lombardy, Lake Como continues to dominate the highend segment, with top sales around €20,000 per sqm for lakefront villas and penthouses, often the subject of investment by international clients. Demand is favouring properties with terraces, gardens, and panoramic views, with increasing attention to privacy and construction
Source: Engel & Völkers Italy
quality. On Lake Maggiore and Lake Orta, top prices reach €8,000 per sqm, supported by high-end infrastructure and international appeal, particularly outside Europe. The creation of new resorts and luxury hotel chains is increasing demand for prime properties.
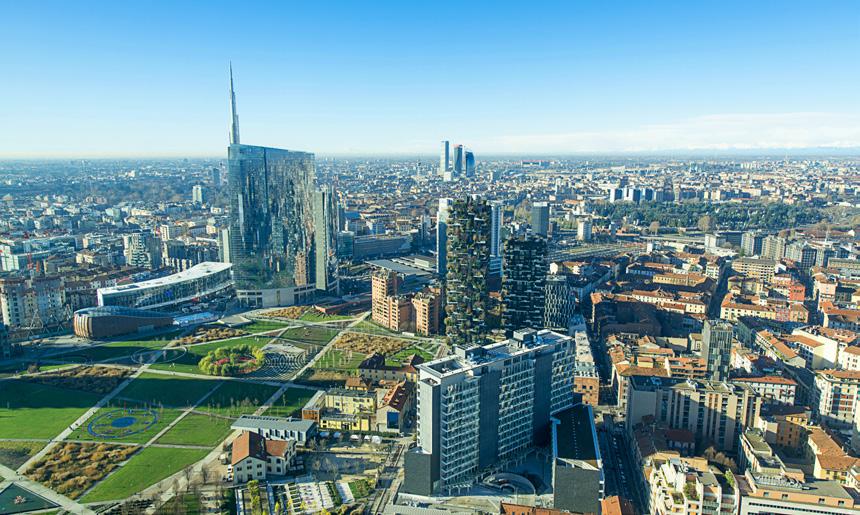
Milan, the financial and cultural heart of the city, continues to attract international investors and buyers seeking apartments and penthouses in central and semi-central areas. The city shows strong resilience in top values, where architectural quality and strategic location dictate the market. Top prices reach €27,000 per sqm in the historic centre and the most exclusive areas.
Provincial towns such as Legnano and Gallarate show top prices of €6,500 per sqm and €4,800 per sqm respectively, highlighting the shift in demand from Milan to more residential areas, with a focus on newly built villas, penthouses, and apartments.
Bergamo, Brescia and Monza and Brianza record top prices between €4,500 per sqm and €5,000 per sqm, with prime segments growing, driven by property quality, location, and
Origin of foreign buyers NW area
access to high-end services. Franciacorta displays a more selective market, with top prices of €3,000 per sqm, supported by properties with aesthetic appeal and potential for redevelopment.
In Liguria, Alassio and the Riviera delle Palme remain a
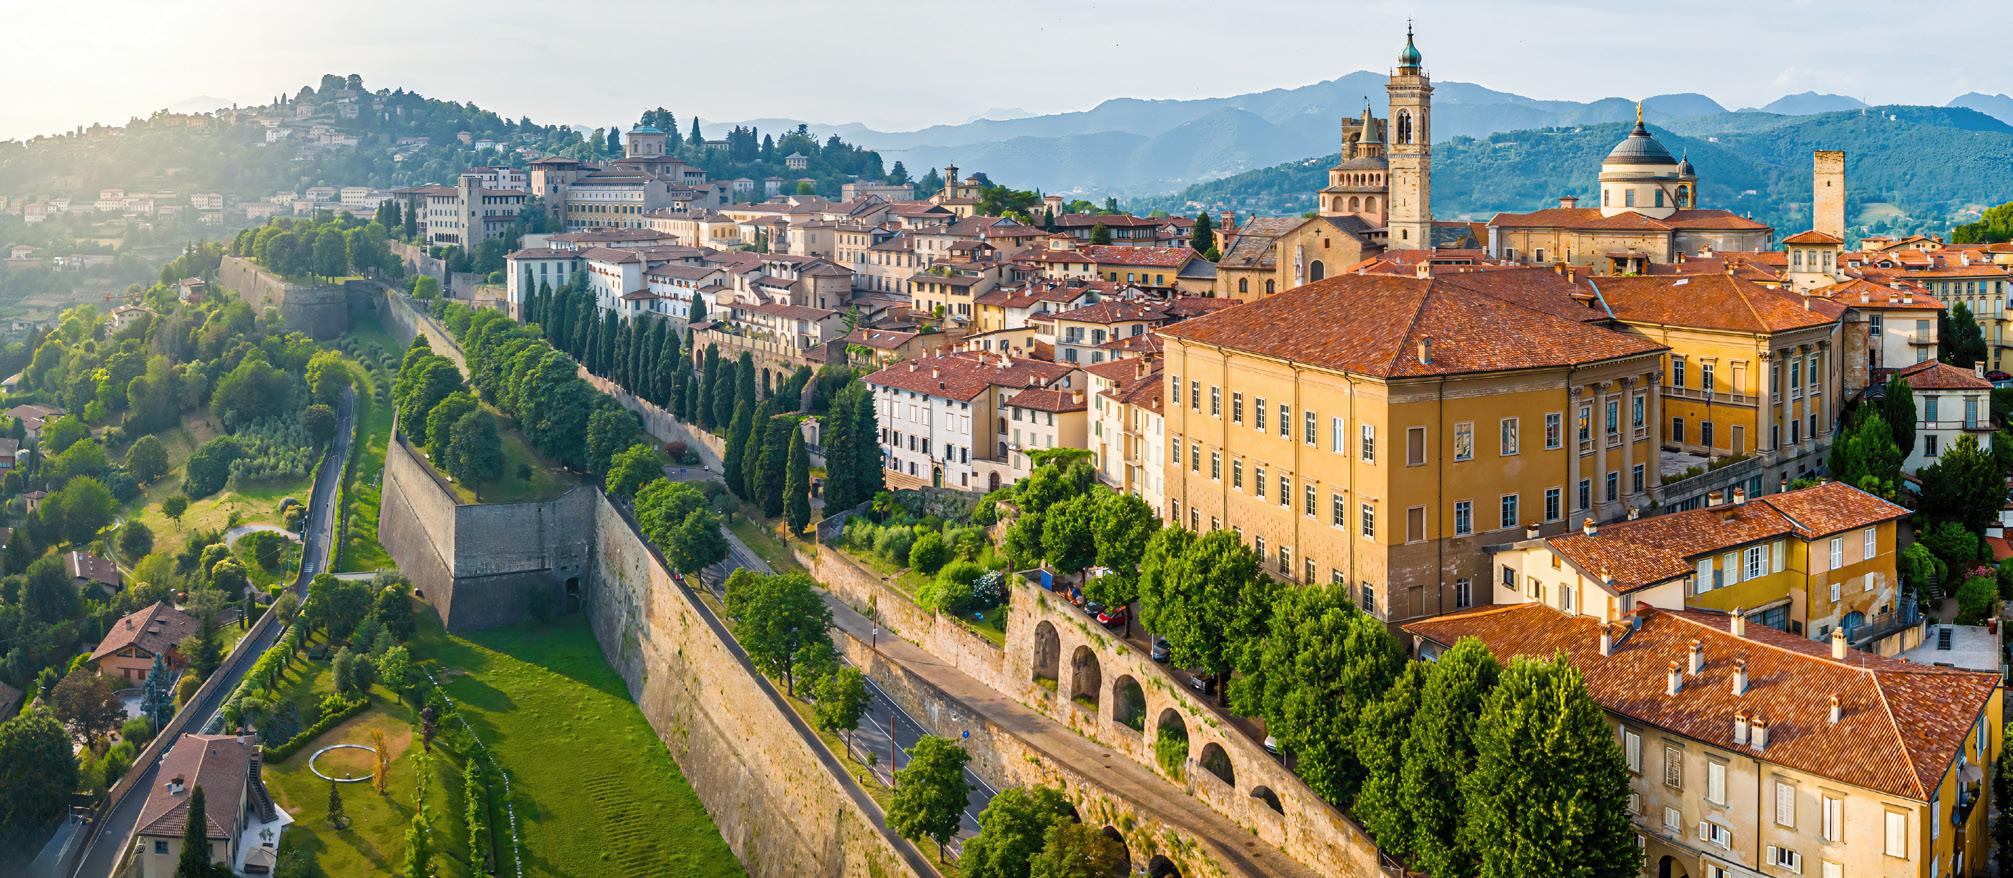
high-end market where the prime segment dominates due to quality and positioning. The city's appeal lies in the combination of its historical heritage, the privacy guaranteed by exclusive villas and penthouses, and the presence of high-end resorts and services, attracting an international and VIP clientèle. In 2025, top prices reached €16,000 per sqm, reflecting the demand for properties with sea views, large terraces, and high-end finishes. International demand is keeping the market dynamic, with fast closing times for top-quality properties. Genoa, while offering more diversified segments, is showing growing interest in renovated historic properties in central areas such as Carignano, Castelletto, and Albaro. The combination of sea views, historic architecture, and private outdoor spaces has pushed top prices to €8,000 per sqm, with international buyers focused on quality and
uniqueness, rather than the quantity of available properties. The outlook for 2026 sees stable valuesin urban areas of Lombardy and Piedmont, with slight growth in the mediumhigh segment thanks to the return of Italian and international buyers motivated by construction quality, outdoor spaces, and a strategic location. Lake and mountain areas will continue to grow in the prime segments, with increased competition between foreign and Italian investors, shorter closing times, and increasing selectivity towards prime properties. Second homes and prime properties are also expected to consolidate as stable investments, while infrastructure, taxation, and local liveability will remain key factors in purchasing decisions. The differentiation between prime properties and the secondary market will become increasingly clear, reinforcing a polarization of values.
NEW/RENOVATED, 2026 PRIME PRICE
Source: Istat e Engel & Völkers 15-18K €/sqm
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
1,2-1,5M
PURCHASES WITHOUT HOME LOAN 90 %
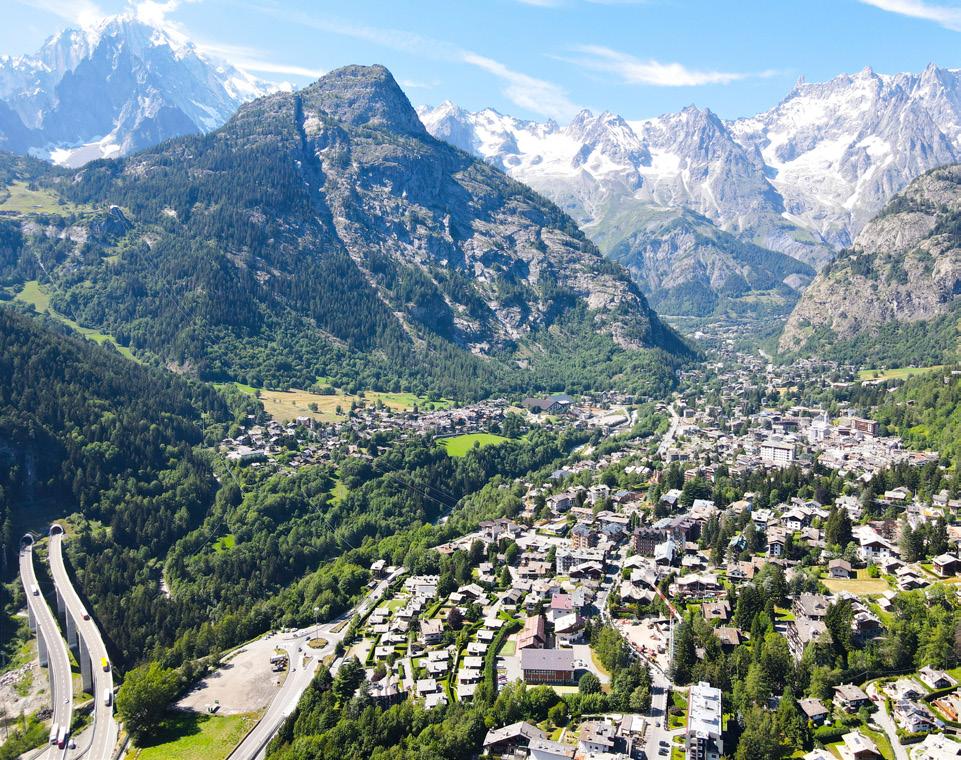
The Courmayeur market stands out for its dynamism, driven by rapidly growing demand for new or renovated properties, which, however, faces a declining supply of properties. Purchases in the prime (40%) and high-end (40%) segments predominate, with values per square meter confirming the prime profile of the location: prices range between €10,000 and €15,000 per sqm for the prime segment, rising to between €15,000 and €20,000 per sqm for high-end properties. Demand comes from Italians, predominantly between the ages of 45 and 54. The sector's dynamism is confirmed by extremely short sales times, which drop below a month in the centre and semi-centre, while remaining between 3 and 6 months in other areas. The market is expecting stronger demand in the prime segment and intense competition, with even faster take-up. Exclusivity and four-season liveability are driving
investments in properties that combine asset value and Alpine lifestyle.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
13-15K €/sqm +10 % 1,2-1,5M € 16K €/sqm 90 % 90 %
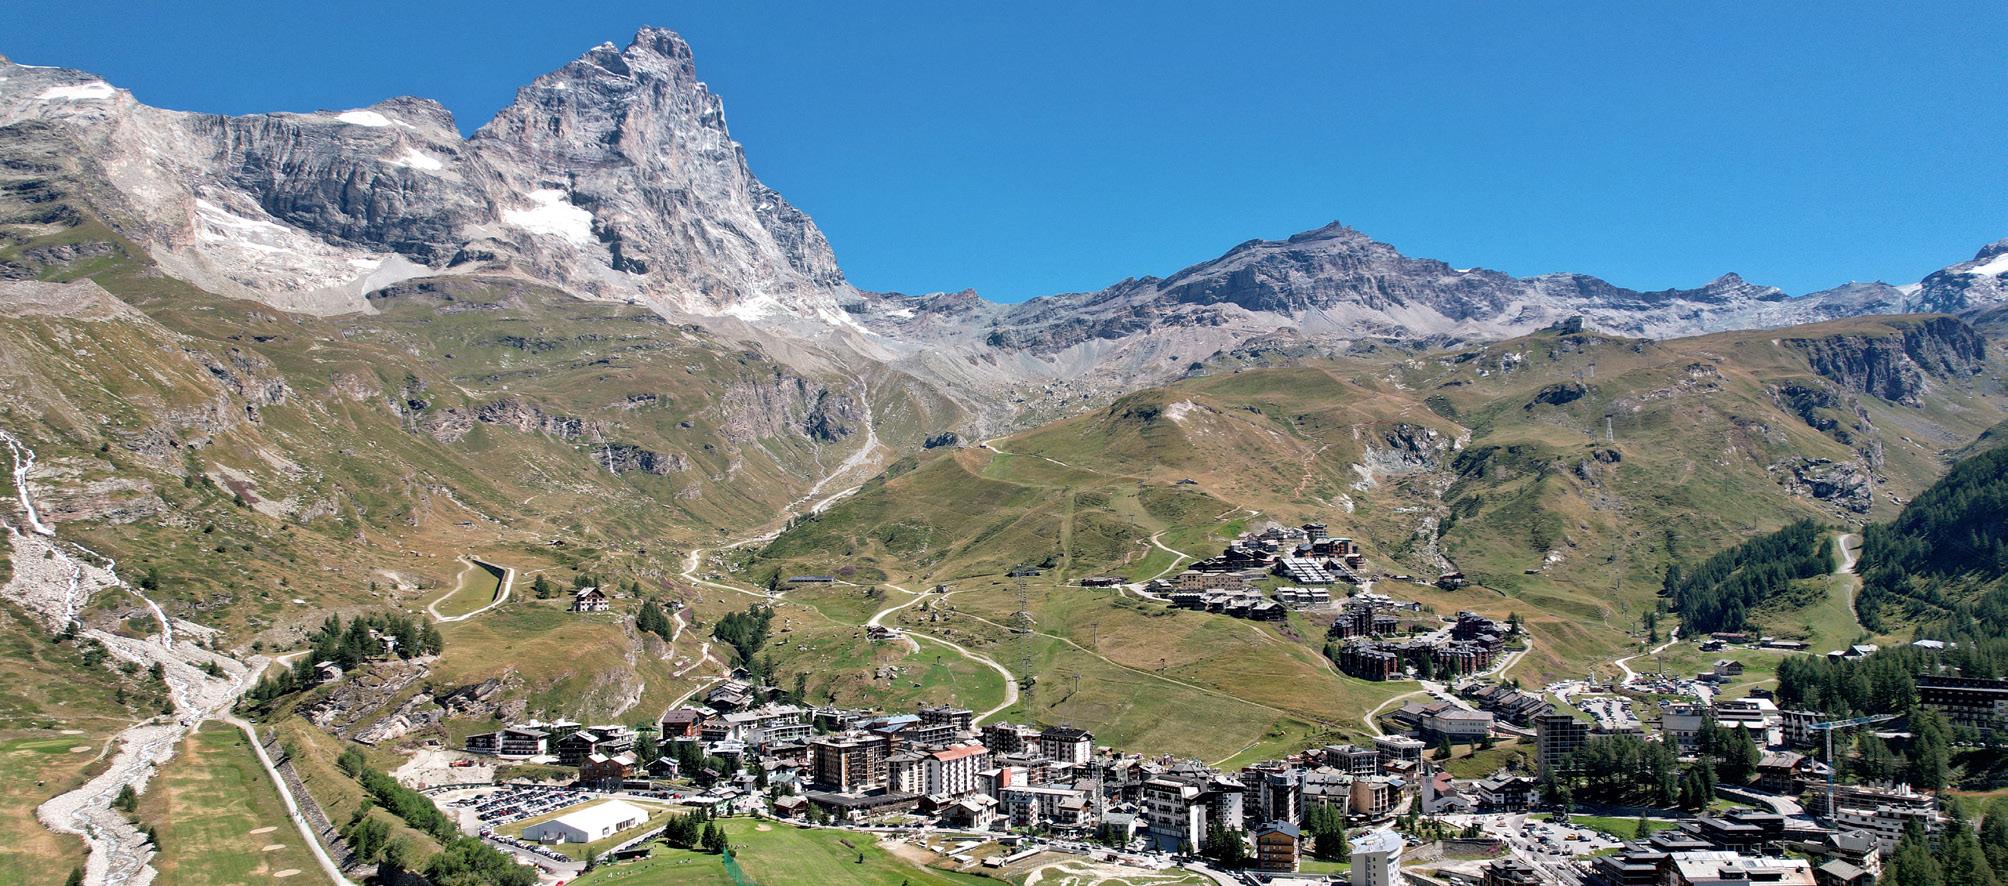
The Breuil-Cervinia real estate market is biased upwards: the prime and high-end segments represent 80% of the market. Regarding prices, the prime segment stands between €9,000 and €12,000 per sqm, while the high-end segment ranges from €12,000 to €15,000 per sqm. Demand, which is growing rapidly, is driven by a target market between 45 and 54 years old, who are looking primarily for second homes, with a view, terrace or balcony, and garage/parking space. Average sales times are rapid: less than a month in the centre, 1-3 months in the semicentre, and within 6 months elsewhere. The market is experiencing strong demand growth in the face of limited supply, pushing prices up. There is growing interest in quality properties, chosen for their location and amenities as assets to be enhanced over time. A dynamic market is expected for the rest of 2026, with further consolidation of
PURCHASES WITHOUT HOME LOAN
values in the most sought-after locations and a strengthening of the high-end segment.
Italian and foreign buyers
Source: Engel & Völkers Italy
2,2-3K €/sqm +4 /+7%
The prime market in Asti and Monferrato saw moderate growth in demand while supply remained stable, with price increases concentrated in the high-end and prime segments, where the fluctuation ranged between +4% and +7%. Transactions involved the prime segment (58% of the total) and the high-end segment (24%), while average sales times in prime areas remained between 3 and 6 months. Demand favours used properties in good condition, with particular interest in villas and farmhouses with outdoor spaces and areas suitable for a home office. The international component, accounting for 50% of total demand, continues to play a key role, attracted by the landscape and the high-potential market. The prime segment is expected to grow in 2026 H2, thanks in part to the interest of new investors linked to high-quality tourism.
500-800K €
Source: Istat e Engel & Völkers 3,5-4,5K
Cuneo's prime real estate market shows signs of a slight expansion in demand, while supply remains stable, accentuating the polarization between renovated homes and lower-quality products. New or renovated properties maintain the greatest appeal, reaching values of up to €4,500–5,000 per sqm in the most sought-after areas, while the intermediate segment shows a decline (-5%). The high-end market remains more dynamic, supported by buyers with high purchasing power interested in farmhouses, penthouses, and apartments with views, terraces, and high energy efficiency. Sales times range between 3 and 6 months, exceeding 6 months in the more peripheral areas. Demand is predominantly Italian (70%), while the share of foreign buyers is predominantly European. The main drivers remain purchasing power, property quality, and quality of life, while critical issues
concern seller expectations and inventory that doesn't meet required standards. Overall, the market remains selective, with significant price premiums for move-inready properties in sought-after locations.
NEW/RENOVATED, 2026 PRIME PRICE
TOP PRICE
Source: Istat e Engel & Völkers
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS PURCHASES WITHOUT HOME LOAN
The market in the Alba, Langhe, and Roero area is experiencing moderate demand growth, while supply is declining, with price increases varying by segment: intermediate prices range between €1,200 and €1,800 per sqm, with essentially stable variations; high-end prices range between €1,700 and €3,500 per sqm (+1-3%), and prime prices range between €3,500 and €4,800 per sqm, with a more marked increase (+4-7%). The second home market clearly dominates the demand structure (60%), followed by investment properties (20%), with first home purchases remaining marginal. The most sought-after property types are penthouses, villas, and farmhouses, while must-haves include a garden/outdoor space, a view, a home office, and silence/privacy. In negotiations, the main critical issues concern off-market prices, stock quality, and urban planning/cadastral compliance. Overall, the market exhibits fundamental strength, with the foreign component
Italian and foreign buyers
Source: Engel & Völkers Italy and the prime segment as the main drivers of dynamism for the remainder of 2026.
EUROPEAN
Source: Istat e Engel & Völkers
Milan's residential market remains solid, supported by moderately growing demand and a progressively increasing supply. Transaction activity remains dynamic and sees a clear prevalence of the prime segment, which accounts for approximately 64% of sales, while the intermediate segment represents 24% and high-end 12%.
The prices reflect the market's strong qualitative polarization: the intermediate segment ranges between €5,000 and €9,000 per sqm, the high-end segment between €9,000 and €15,000 per sqm, while prime reaches levels between €10,000 and €23,000 per sqm, with a top price of €27,000 per sqm for particularly rare assets.
In 2025, prices showed limited changes in the medium-low range (+1/+3%), while the higher ranges recorded more sustained increases (+4/+7%). Average sales times remain rapid, between 1 and 3 months. Demand is predominantly domestic, but the international component continues to support the prime segment.
The leasing sector remains dynamic and competitive, with rapid take-up times and virtually zero negotiation margins. Demand is concentrated primarily for renovated, furnished, and move-in ready properties, preferably in locations wellconnected to major business hubs and central districts. Over the course of the year, demand has gradually expanded to semi-central areas, with particular dynamism in well-served residential neighbourhoods characterized by good urban quality. Demand remains balanced between Italian and international tenants, often professionals or managers relocating to the city for work.
The outlook for 2026 indicates overall stable demand for sales, with more favourable trends in the prime segment, supported by international interest and the city's attractiveness. The leasing market overall also maintains a good balance, and demand is expected to remain solid in 2026, supported by the city's economic and international appeal.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
1,6-4K €/sqm +1/+3%
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
800K-1,2M €
PURCHASES WITHOUT HOME LOAN
4,5K €/sqm
Source: Istat e Engel & Völkers
Bergamo's prime residential market is experiencing moderate demand growth, driven largely by Italian buyers (approximately 90%), while supply remains stable. Prices are recording a modest annual increase, ranging between 1% and 3%. Transactions are concentrated in the high-end segment, which represents 50% of the total, and in the prime segment (30%), with average sales times exceeding six months. Regarding purchase reasons, first homes and replacements together account for 65% of the market; second homes follow at 25% and investment purchases at 10%. Demand favours new or renovated properties, with a preference for apartments, penthouses, and villas, with particular attention paid to terraces, outdoor spaces, and garages/parking spaces. Demand is expected to grow in 2026 H2, which should affect the entire city market.
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3,5-4,5K €/sqm -1/0% 500-800K € 5K €/sqm 80 %
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Brescia's prime residential market is experiencing moderate demand growth, driven primarily by Italian buyers, while supply remains essentially stable. Prices are experiencing a modest but widespread increase, with prime properties ranging between €2,500 and €3,500 per sqm, and high-end properties between €4,000 and €5,000 per sqm. Transactions are concentrated primarily in the intermediate segment, which accounts for approximately 50% of sales, followed by the prime segment at 45% and a smaller share of high-end transactions (5%). Demand favours new or recently renovated properties, with particular interest in apartments, penthouses, and villas. Among the most sought-after features are terraces or balconies, private outdoor spaces, a parking space or garage, and the presence of an elevator. There is also a growing focus on buildings with high energy performance. For 2026 H2, expectations indicate growing demand in the mid-range segment and stability in the prime and high-end
Sales by type of investment
Source: Engel & Völkers Italy
segments. The main factors that could influence the market include mortgage interest rates, the stability of the international environment, and the development of new infrastructure in the area.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3,5-6,5K €/sqm +1 /+3% 500K-1,2M € 7K €/sqm 40 %
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
In Monza, the prime real estate market is showing positive momentum, supported by moderately growing demand and stable supply. Prices are showing a marked increase in the mid-range segment, growing between 4% and 7%, where half of all sales are concentrated, while the prime and high-end segments are recording more modest increases, between 1% and 3%. The prime segment stands between €3,000 and €4,500 per sqm, while the high-end segment stands between €5,000 and €7,000 per sqm. Sales times are short, generally between one and three months in central and semi-central areas. Demand is concentrated primarily for new and renovated properties, particularly apartments, penthouses, and villas, and is driven primarily by Italian buyers (70%), with a growing foreign component. A terrace, garden, parking space, and a high energy rating remain essential must-haves. Off-market prices and
compliance with urban planning and land registry regulations are the main factors that disrupt sales.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3-4 K €/sqm +1/+3 % 500K-1,5M € 4,8 K €/sqm
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The prime residential market in Varese is showing moderate growth in demand while supply remains stable. The distribution of sales shows a clear predominance of the prime segment (60%), followed by intermediate (20%) and high-end (20%). Prices in the prime segment range from a minimum of €2,000 per sqm to a maximum of €3,000 per sqm, while high-end ranges from €3,000 to €4,000 per sqm. Compared to 2024, trends show an increase in the city centre and stability in other areas. Demand is driven primarily by Italian buyers (90%), with a limited foreign component (10%), almost exclusively European. The majority of buyers are between 35 and 44, while sellers are concentrated in the 55-64 age group. The most soughtafter types are apartments, penthouses, and villas, preferably new or renovated with a high energy rating. The most sought-after features remain a terrace or balcony,
Sales by type of investment
2025 Data garden, view, and parking space. Stability is expected across all segments for 2026 H2.
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
1,8-2,1K
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Franciacorta's prime market shows substantial stability in both supply and demand, with limited price fluctuations across all segments. Franciacorta attracts predominantly Italian demand (77%), primarily focused on first-time home buyers (65%), and buyers aged 45–54 with an average decision-making process of more than six months. The prime segment is largely predominant in sales, with a share exceeding 62%, compared to a high-end component of approximately 20%. The prime segment ranges between €1,700 and €1,950 per sqm, while high-end prices range between €1,900 and €3,000 per sqm. The most soughtafter property types are apartments, villas, and new builds; essential requirements include a terrace/balcony, garden/ outdoor area, parking space, and a high energy rating. For 2026 H2, forecasts indicate stability in the medium-low segment and growth in the prime and high-end segments.
Sales by type of investment
2025 Data
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
5-7K €/sqm -1/0% 800K-1,2M €
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
8K €/sqm 95 %
Source: Istat e Engel & Völkers
Ponte di Legno's prime residential market is experiencing moderate demand growth, while supply is growing, supported by infrastructure investments and the Alpine resort's growing visibility in the run-up to major international sporting events. Buyers' interest is primarily focused on new or recently renovated properties with high energy standards and amenities such as a terrace, panoramic views, and parking spaces. Sales are concentrated mainly in the prime segment, which represents approximately 83% of transactions, while the intermediate segment accounts for approximately 10%. The high-end segment remains more selective, with a share of around 7%. In the semi-central area, prices vary between €3,500 and €5,000 per sqm, while in the rest of the market they range between €3,500 and €4,000 per sqm. Demand is almost entirely tied to the purchase of second homes, with buyers primarily Italians in the 45–54 age group. For 2026 H2, stable
Italian and foreign buyers
Source: Engel & Völkers Italy
PURCHASES WITHOUT HOME LOAN
100 %
demand is expected in the intermediate segment and growth in the prime and high-end segments.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,5-3K €/sqm -10% 800K-1,2M €
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
3,5K €/sqm
Source: Istat e Engel & Völkers
The Buccinasco market is showing a lively trend, driven by strong demand growth while supply remains stable. New or renovated properties remain the most sought-after, favoured by buyers who are attentive to construction quality, energy efficiency, and the presence of outdoor spaces. Prices in prime areas range between €3,000 and €3,500 per sqm, while high-end areas range between €4,000 and €5,000 per sqm. Most purchases are in the intermediate segment, with a consequent significant reduction in prices for the other market segments (-10%). Demand is almost entirely Italian and focused on apartments, penthouses, and villas with terraces, gardens, and privacy. The average sale time is between 3 and 6 months, over 6 months in less central areas. Interest rates, property quality, and quality of life remain the main drivers of a stable yet selective market, with growing attention to large spaces and living comfort.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,8-5K €/sqm +4/+7%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
€
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Legnano's real estate market has seen sharply increasing demand while supply has remained largely stable, resulting in upward pressure on prices: the intermediate segment has seen an estimated increase of between 1% and 3%, while the prime segment has shown more marked growth, in the range of 4% to 7%, reaching prices between €3,000 and €4,750 per sqm. Prime properties dominate the sales mix (75%), also supported by demand from the Milan area, oriented towards contexts more suited to family life within a short distance of the city. The most sought-after types are apartments, penthouses, and villas, with terraces/ balconies, outdoor space, high energy ratings, and proximity to public transportation among the priority requirements. The main critical elements in the negotiation are the off-market price, the seller's expectations and urban planning and cadastral discrepancies. For 2026 H2,
forecasts indicate stability in the medium-low segment and growth in the prime segment.
Sales by type of investment 2025 Data
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
3,5-5,7K €/sqm +4/+7%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
The Saronno and Olgiatese market stands out for its dynamism, driven by rapidly growing demand for new or renovated properties, while the availability of properties remains stable. The market composition is led by the prime (50%) and high-end (30%) segments, followed by the intermediate segment (20%), with values that confirm the attractiveness of the area: prices range between €2,800 and €4,500 per sqm for prime, up to €3,200 and €6,250 per sqm for high-end. 80% of the demand comes from Italians, with a predominant target between 45 and 54 years old. The sector's liveliness is confirmed by the sales times in the city centre and semi-city areas, where transactions close between 1 and 3 months. The market is showing a trend towards further consolidation of demand and values, supported by families who prefer safe environments, with services for their children and access to green spaces. The efficiency of highway and rail
AVERAGE BUDGET IN PRIME SEGMENT
PURCHASES WITHOUT HOME LOAN
connections to Milan and the quality of life remain the main drivers of investment in the area.
Sales by type of investment
2025 Data
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
1,9-3,3K €/sqm +1/+3% 500-800K €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
4,7K €/sqm 40 %
Source: Istat e Engel & Völkers
The residential market in Seregno and Brianza shows moderately growing demand while supply remains stable, with a significant impact on the mid-market segment, which accounts for 60% of monitored sales. Prices show a more marked increase in this range (+4-7%) compared to the prime and high-end categories, both of which are increasing between +1-3%. Demand is supported by a high incidence of purchases with a mortgage (60%), while demand is mainly supported by Italian buyers (80%). Buyers are showing interest in apartments, villas, and new buildings with terraces, gardens, and good energy ratings, appreciating proximity to major transportation services. Sales times range between 3-7 months. The outlook for 2026 H2 indicates growth in demand in the prime segment, while the intermediate segment appears oriented towards stability.
PURCHASES WITHOUT HOME LOAN
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3-3,8K €/sqm +4/+7% 500-800K €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
4,4K €/sqm
Source: Istat e Engel & Völkers
The Gallarate and Busto Arsizio market shows a prevalence of sales in the prime segment (55%), followed by the intermediate segment (32%) and a high-end niche (13%). In the prime segment, prices range between €2,500 and €3,300 per sqm, while in the intermediate range, prices range between €1,700 and €2,000 per sqm. The purchase process requires very rapid processing times (1-3 months) for prime areas and longer processing times (over 6 months) for other areas. The target, almost entirely Italian (98%), is mostly aged between 45 and 54 and is interested in second-hand habitable properties such as apartments, penthouses and villas. Must-haves include terraces, gardens, parking spaces, a high energy rating, and home office space. Growth in the prime segment is expected for the rest of 2026, driven by Milan's high costs, which are pushing young professionals and new families to move to
this area, attracted by the quality of housing and the efficiency of its strategic transport links.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
5-7K €/sqm +1/+3%
TOP PRICE
7,5 K €/sqm
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
60 %
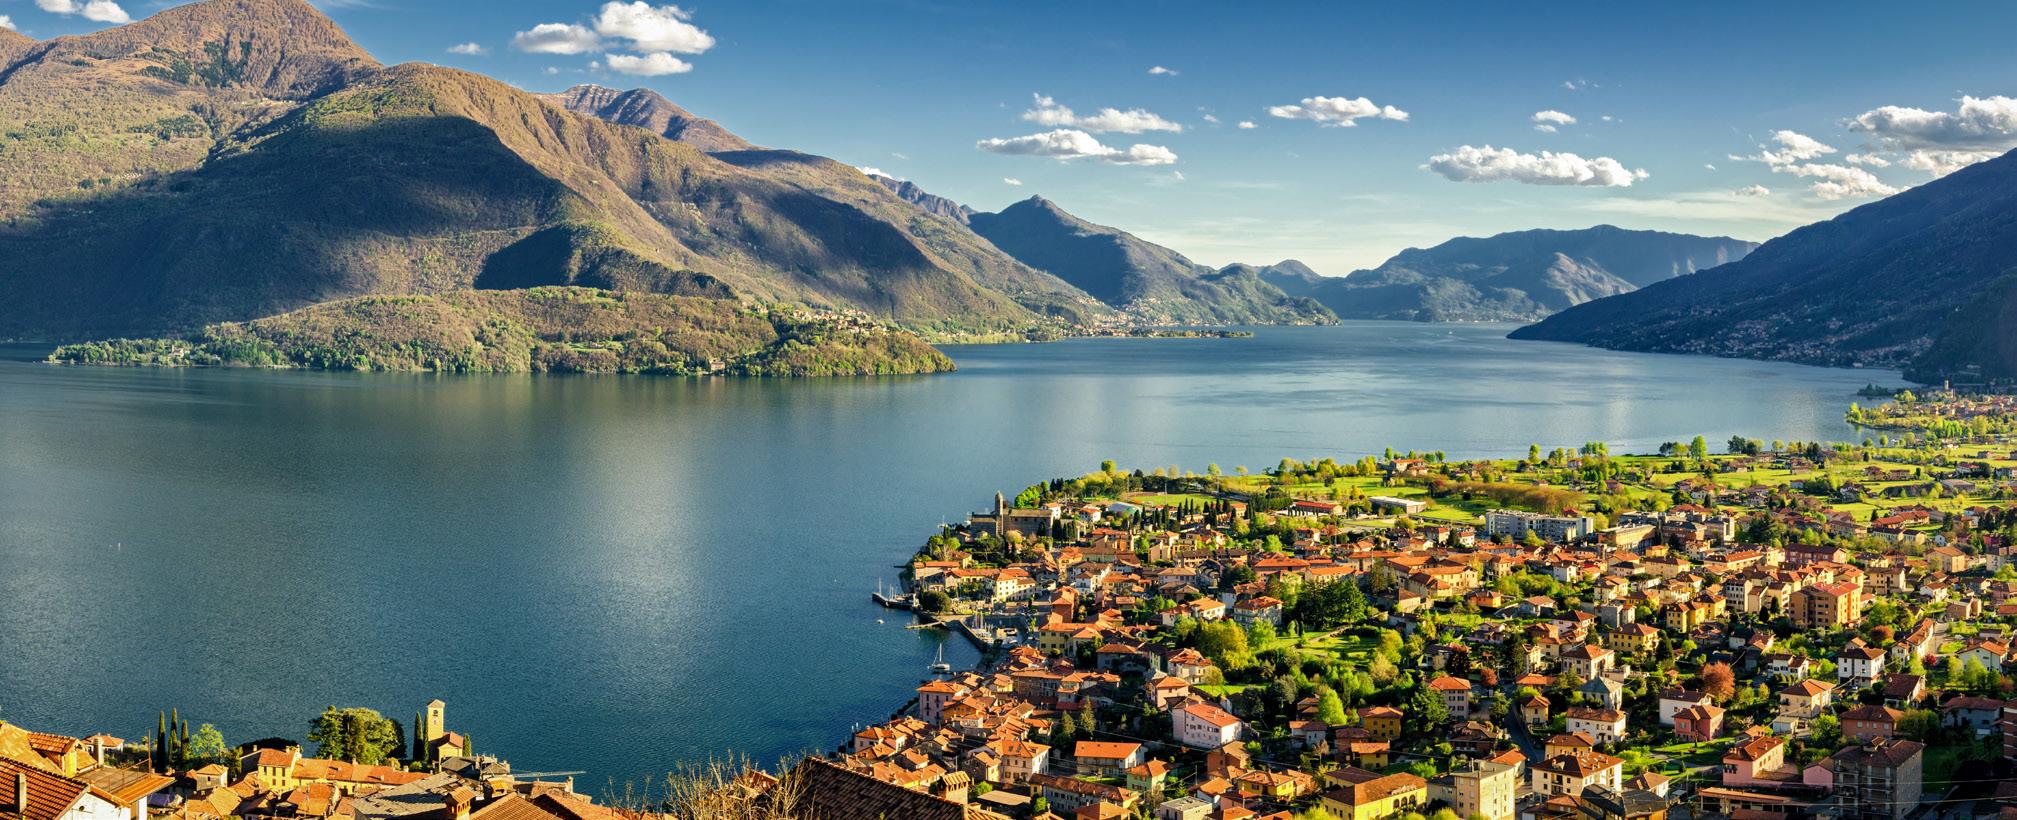
The prime residential market on Lake Como is experiencing strong growth in demand, largely driven by international buyers, who account for approximately 60% of all buyers. Supply remains generally stable, helping to support price levels, especially in the higher segments of the market. Sales are fairly evenly distributed across the various segments: 40% concern prime properties, 30% the intermediate segment and the remaining 30% high-end. Compared to the previous year, there was an increase in values in the central areas, while in the other areas a substantial stability prevails. As regards purchasing motivations, the market is strongly oriented towards second homes, which represent approximately 50% of transactions, followed by investment purchases (30%). First homes and replacements both account for 10%. 40% of buyers resort to bank financing, while 60% complete the transaction in cash. Demand favours new or recently renovated properties, with particular interest in
AVERAGE BUDGET IN PRIME SEGMENT
800K-1,2M €
PURCHASES WITHOUT HOME LOAN
60 %
apartments, villas and new buildings. For 2026 H2, expectations indicate growth in demand in all market segments.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
3-3,8K €/sqm +1/+3%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
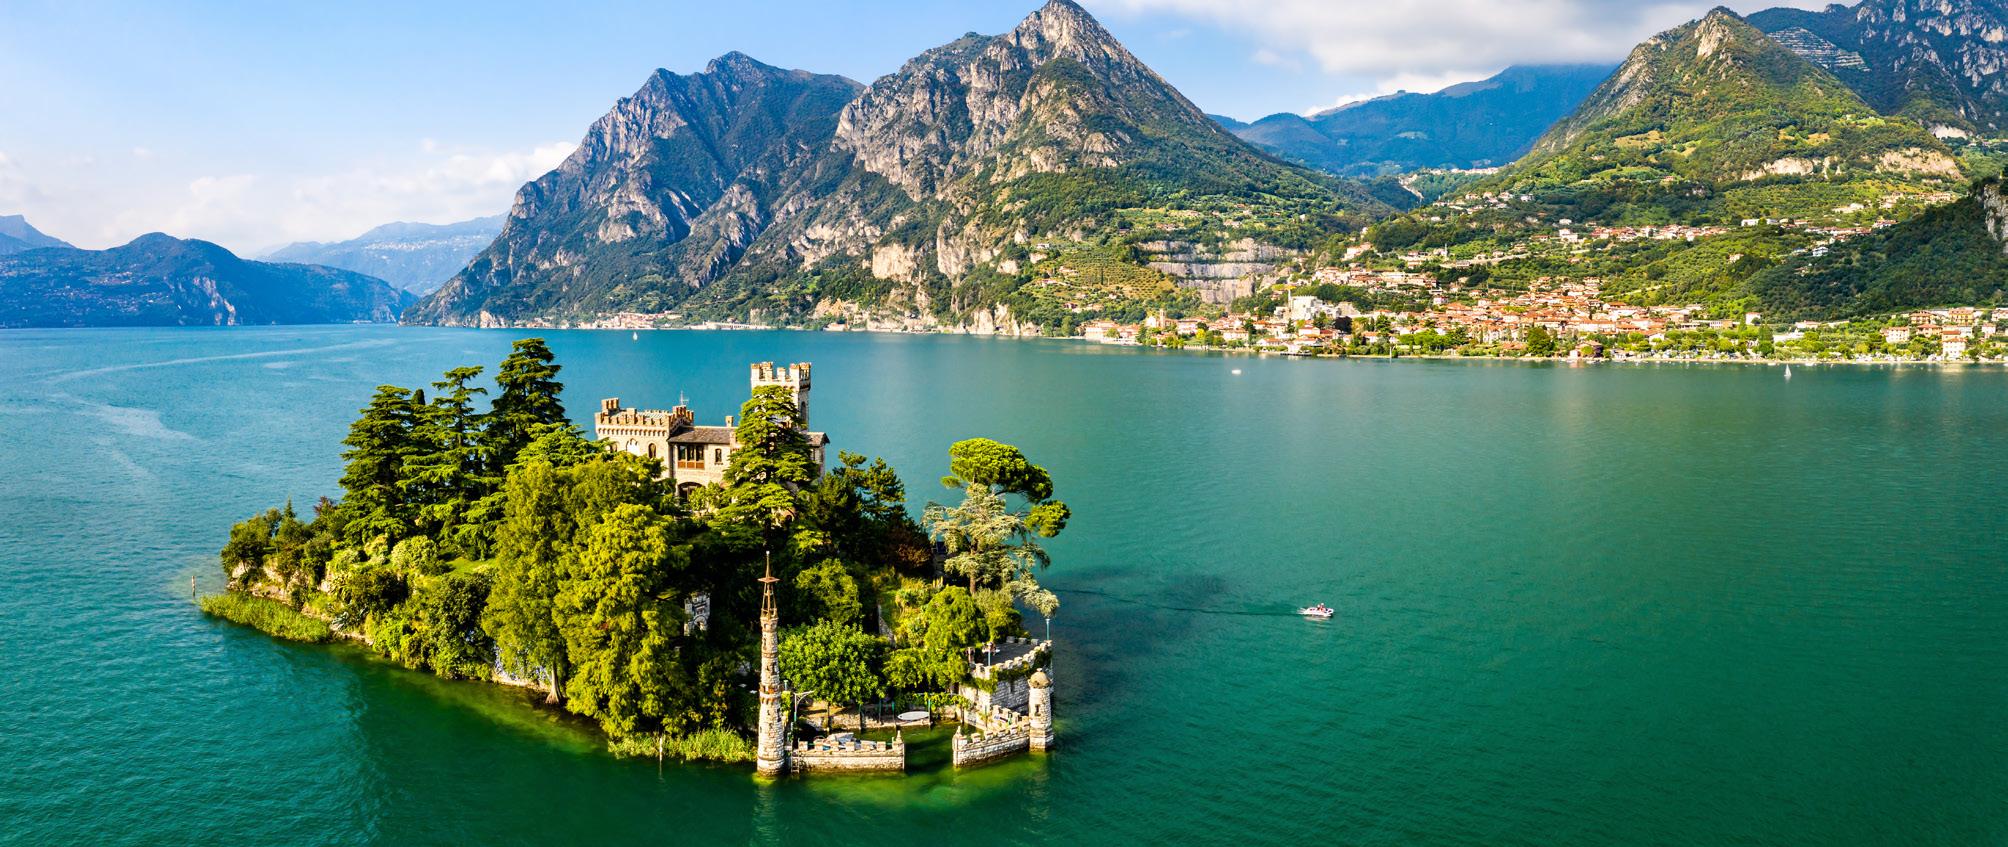
The 2025 context analysis shows that the Lake Iseo market is experiencing moderate growth in demand, with stable supply and a clear polarization between quality properties and secondary products. New or renovated properties continue to drive the market, particularly in the prime segment, which accounts for 65% of sales, with prices reaching €3,800 per sqm in central areas and €4,500 per sqm in top-line deals. The prime segment maintains a positive trend, supported by increasingly selective and informed demand, often international, oriented towards penthouses, villas, and new builds with lake views, privacy, and high energy standards; conversely, the intermediate segment is experiencing a decline in prices. Sales times range between 3 and 6 months in the main areas, exceeding 6 months in the rest of the market. Second homes represent the predominant share of purchases: 85%. Property quality, quality of life, and international demand remain the market's main drivers. For the rest of 2026, values are
AVERAGE BUDGET IN PRIME SEGMENT
800K-1,2M €
PURCHASES WITHOUT HOME LOAN
expected to hold up - and in some cases increase - in the prime segment, with an increasingly marked gap compared to the secondary product.
Sales by type of investment
2025 Data
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,5-3,5K €/sqm +1/+3%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
800K-1,5M € 8,4K €/sqm
Source: Istat e Engel & Völkers
The Lake Maggiore and Lake Orta market is dominated by the prime segment (60%), in a context characterized by moderately growing demand and increasing supply. Prices for this sector range between €2,400 and €3,000 per sqm, with interest primarily directed at new or renovated homes. Average sales times reflect local dynamism, ranging from 1-3 months in central areas to over 6 months in peripheral areas. The market is supported by a prevalent share of second home purchases (55%), 60% of which are completed by international buyers. The search focuses on apartments and villas featuring must-have features such as terraces, panoramic views, parking spaces, and high energy efficiency standards. The positive trend is expected to consolidate in 2026, supported by the construction of new high-end infrastructure, such as luxury hotels and restaurants, which will ensure price resilience in the prime segments.
Source: Engel & Völkers Italy
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers 3,5-4,4K
EUROPEAN BUYERS OVER
BUYERS
PURCHASES WITHOUT HOME LOAN
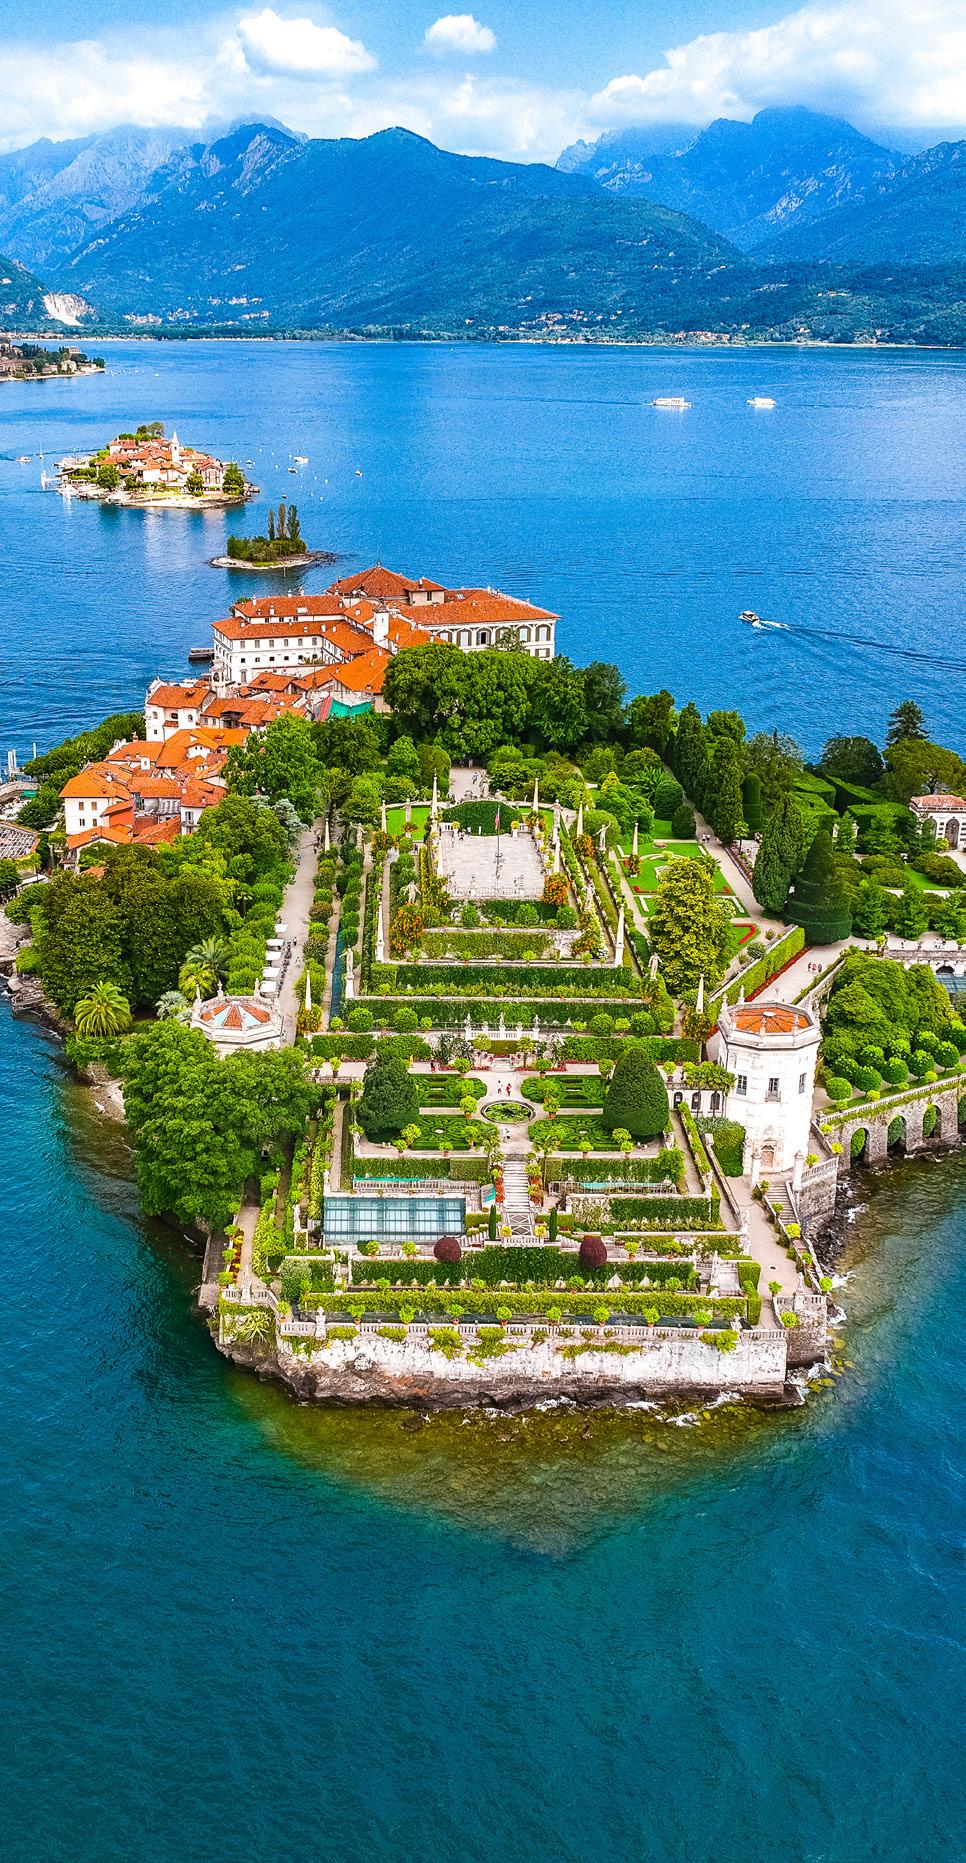
Genoa's real estate market is characterized by increasingly selective demand, oriented toward quality properties, particularly in established residential areas and in contexts with architectural and scenic value. Potential buyers are primarily interested in new or renovated homes, which are perceived as more efficient and immediately usable solutions.
Average prices in the prime segment range between €2,000 and €5,000 per sqm, while the high-end segment fluctuates between €4,000 and €8,000 per sqm, with top prices that can reach significantly higher levels for particularly exclusive properties.
Demand is supported by a target age group mainly between 45 and 54, approximately 50% of which is focused on replacing their first home.
Essential requirements include outdoor spaces such as terraces or gardens, a panoramic view, a parking space, and am elevator. The most sought-after properties offer
distinctive details linked to their historic architectural character and sea views, elements that contribute to defining a prime positioning in the urban context.
Sales times are rapid, with transactions concluding in 1-3 months in prime and semi-central areas and in 3-6 months in the rest of the market.
There is also a growing interest in areas undergoing urban regeneration, where the combination of historical heritage and new infrastructure projects helps strengthen the overall attractiveness. Although Italian demand remains predominant, foreign investors are attracting increasing attention, with a significant presence of North American buyers. For 2026 H2, demand is expected to remain stable in the mid-range segment and grow in the prime and highend ones, supported by drivers such as the pursuit of quality of life and perceived favourable tax policies. Genoa thus consolidates its role as a valuable residential market in the long term.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
7,5-10K €/sqm +1/+3% 800K-1,2M €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
12K €/sqm 20 % 90 %
Source: Istat e Engel & Völkers
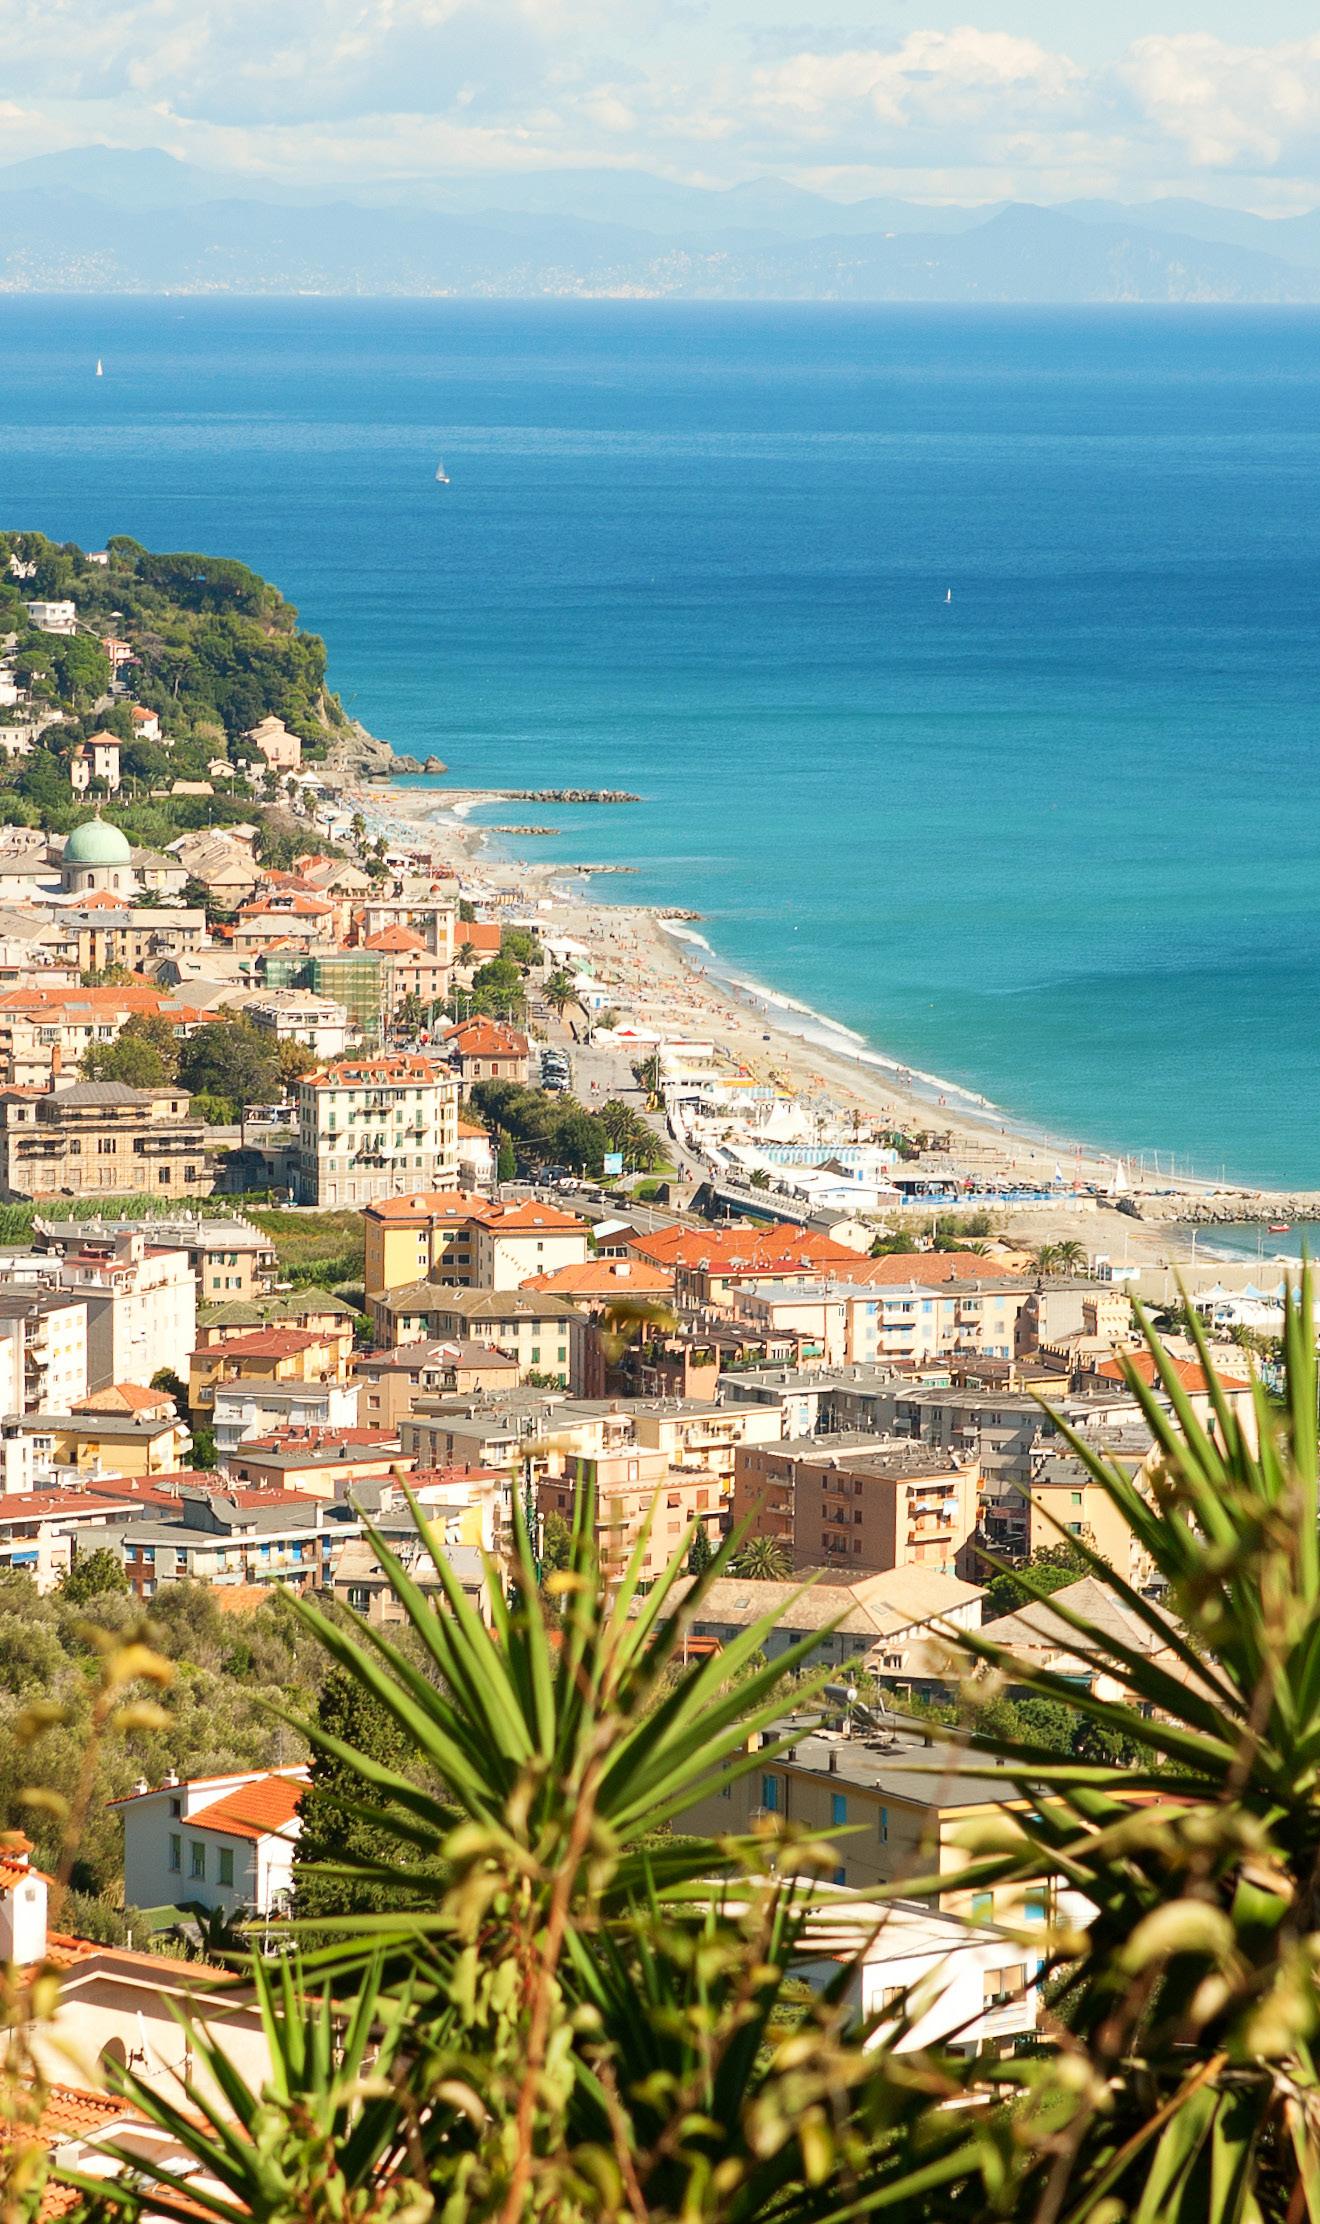
The prime market in the Savona and Varazze area has shown a progressive strengthening of demand in the face of a decreasing supply, determining an increase in values between 1 and 3% in the intermediate and prime segments and between 4 and 7% in the high-end segment. In the centre, average prices exceeded €5,000 per sqm in prime properties and €9,000 per sqm in high-end properties. Transactions were concentrated in the prime (50%) and high-end (30%) segments, with average times of less than a month in the most sought-after areas and between one and three months in the rest of the market. Demand favours new construction, with attention to amenities such as sea views, outdoor spaces, elevators, and garages/parking spaces. The market is driven primarily by first- and secondhome purchases, with a predominance of Italian buyers and a growing contribution from foreign buyers, particularly European ones. For 2026 H2, overall market stability and
Sales
Source: Engel & Völkers
growth in the prime and high-end segments are expected, driven by newly developed, high-quality products.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
7-15K €/sqm +1/+3% 800K-1,2M €
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
18K €/sqm 30 % 65 %
Source: Istat e Engel & Völkers
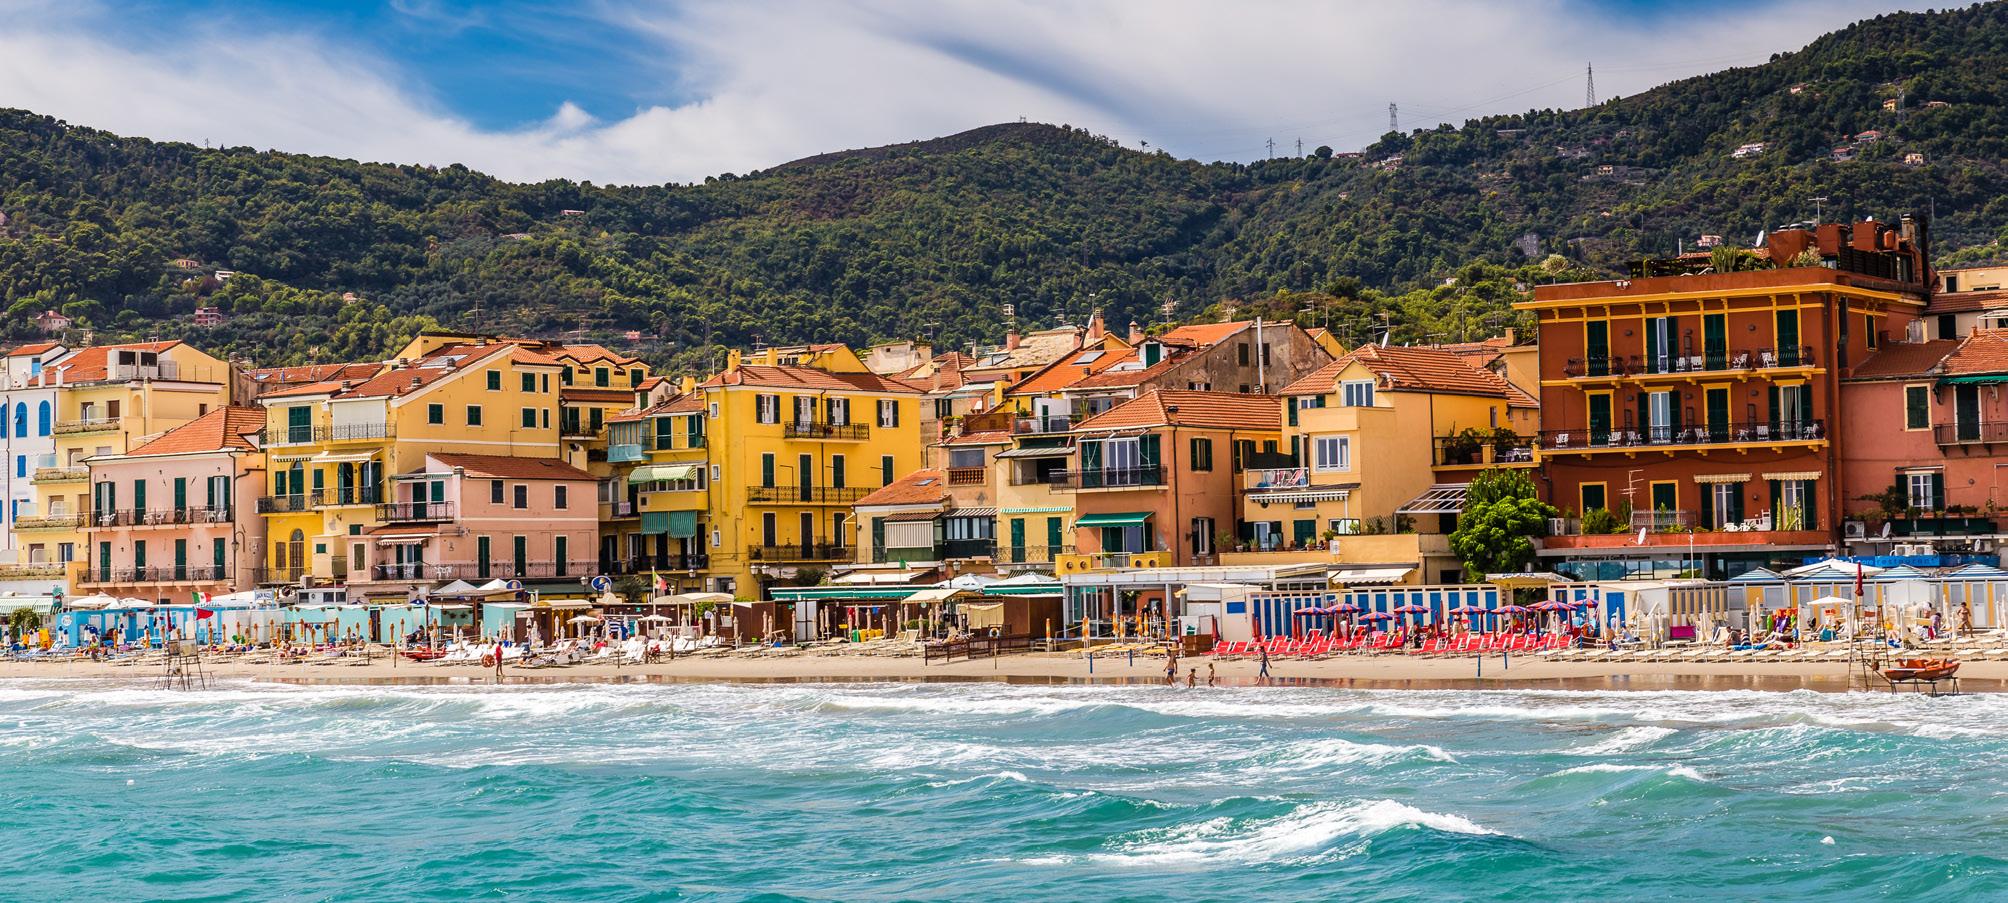
The Alassio and Riviera delle Palme market is showing a stable , positive trend, supported by slightly growing demand and substantially unchanged supply. New or renovated properties continue to drive the market, with prices reaching up to €15,000 per sqm in central areas, confirming the location's prime positioning. Penthouses, villas, and new builds are among the most sought-after properties. The prime segment is seeing the sharpest price increases, driven by buyers seeking quality construction, sea views, privacy, and exclusive settings. Sales times are rapid in the most sought-after areas, while they lengthen slightly in the semi-central area and in the rest of the market. Demand comes mainly from ItalIan customers (70%), with a growing international component, mainly European. Second homes represent the largest share of sales, confirming Alassio as an elite destination for a market oriented towards comfort and quality of living, also
demonstrated by the prevalence of sales in the prime segment (60%).
Sales by type of investment
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
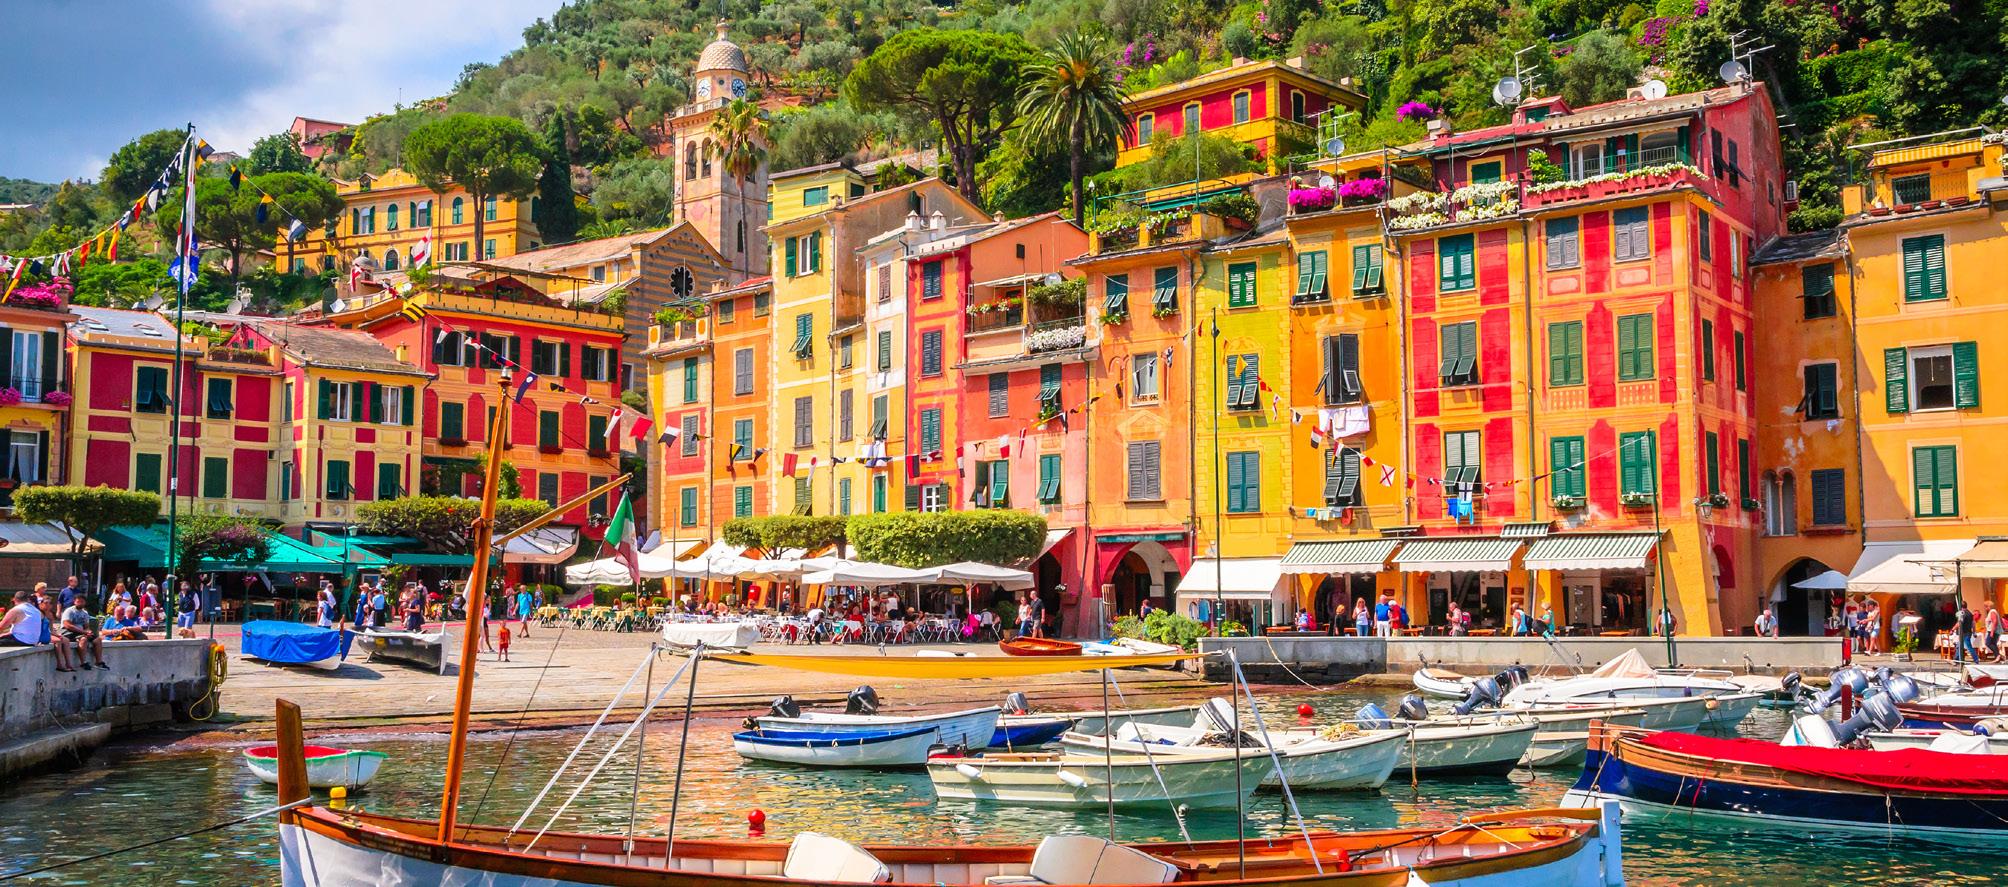
The prime market of Santa Margherita Ligure and Portofino is characterized by a highly upwardly biased demand structure: the prime segment accounts for 65% of transactions, while high-end accounts for 20%, with moderately growing demand and declining supply, which is accentuating the pressure on prices. Prime and high-end recorded increases estimated at around +4-7%, while intermediate remained more modest (+1-3%). With a 30% share of foreign buyers – an increase compared to the previous year – foreign demand remains a structural factor in the market. Typical buyers range between 45 and 54 years old and prefer apartments, villas, and new buildings with a terrace, view, garden, and parking space. Santa Margherita Ligure and Portofino are a market strongly oriented towards second homes, with values in the prime segment between €3,000 and €9,000 per sqm and in the high-end segment between €6,000 and €20,000 per sqm,
2025 Data firmly positioned in the top-tier of the Ligurian market and among the highest prices nationally.
Sales by type of investment
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
4,5-5,5K €/sqm +1/+3%
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
800K-1,5M €
PURCHASES WITHOUT HOME LOAN
9K €/sqm 20 % 50 %
Source: Istat e Engel & Völkers
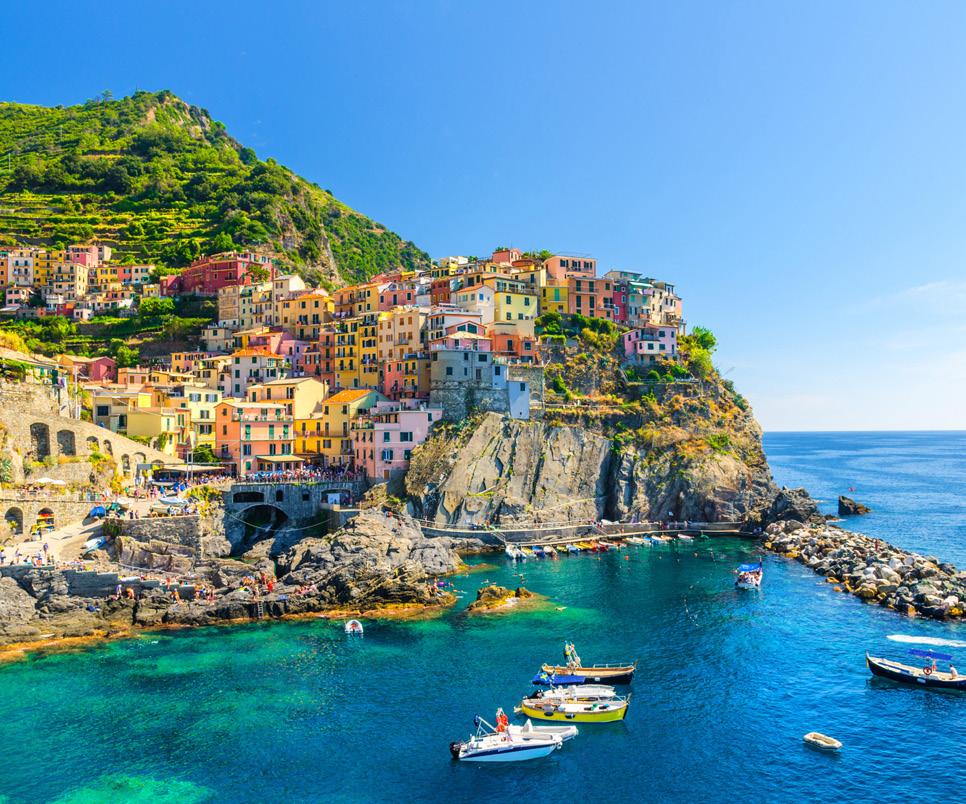
The prime residential real estate segment in Sestri Levante and the Cinque Terre is experiencing a stable phase, with steady demand and a supply that hasn't seen significant fluctuations. Prices are growing moderately and uniformly across all three segments, with increases estimated between 1% and 3%. In terms of value, new or renovated properties in the centre range between €4,500 and €5,500 per sqm, while in the semi-centre the prices reach €4,000 per sqm. Sales times vary significantly: less than a month for properties in the city centre, 1–3 months in semi-central areas, and up to 6 months in the rest of the country. Sales are concentrated in the prime segment (50%), followed by high-end and intermediate, with a significant incidence of second homes. The market remains predominantly domestic (80%), while the foreign component is made up almost exclusively of European buyers. The most soughtafter properties are apartments, villas, and new builds, with a focus on pre-owned, habitable properties. Must-haves
include terraces, sea views, parking spaces, and elevators. The outlook for 2026 H2 is essentially one of stability for the prime segment and growth for the high-end.
ENGEL & VÖLKERS MARKETS TOP PRICE 2025
INTERNATIONAL DEMAND (OVER PREVIOUS YEAR)
17 24,000 €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
80%
Source: Istat e Engel & Völkers
INVESTMENT PURCHASES PURCHASES WITHOUT HOME LOAN
14 %
The prime residential markets of the North East show a complex but overall solid picture, supported by quality of life, selective demand, and a growing focus on the quality of the inventory.
In Emilia-Romagna, dynamic cities like Bologna and Parma are experiencing moderate, structural growth, driven by services, connections, and economic attractiveness; on the Romagna coast, Riccione and Rimini are experiencing developments in their offerings, driven by new construction and redevelopment. The highest price is recorded in Bologna at up to €7,500 per sqm, while in Riccione it reaches €8,000 per sqm.
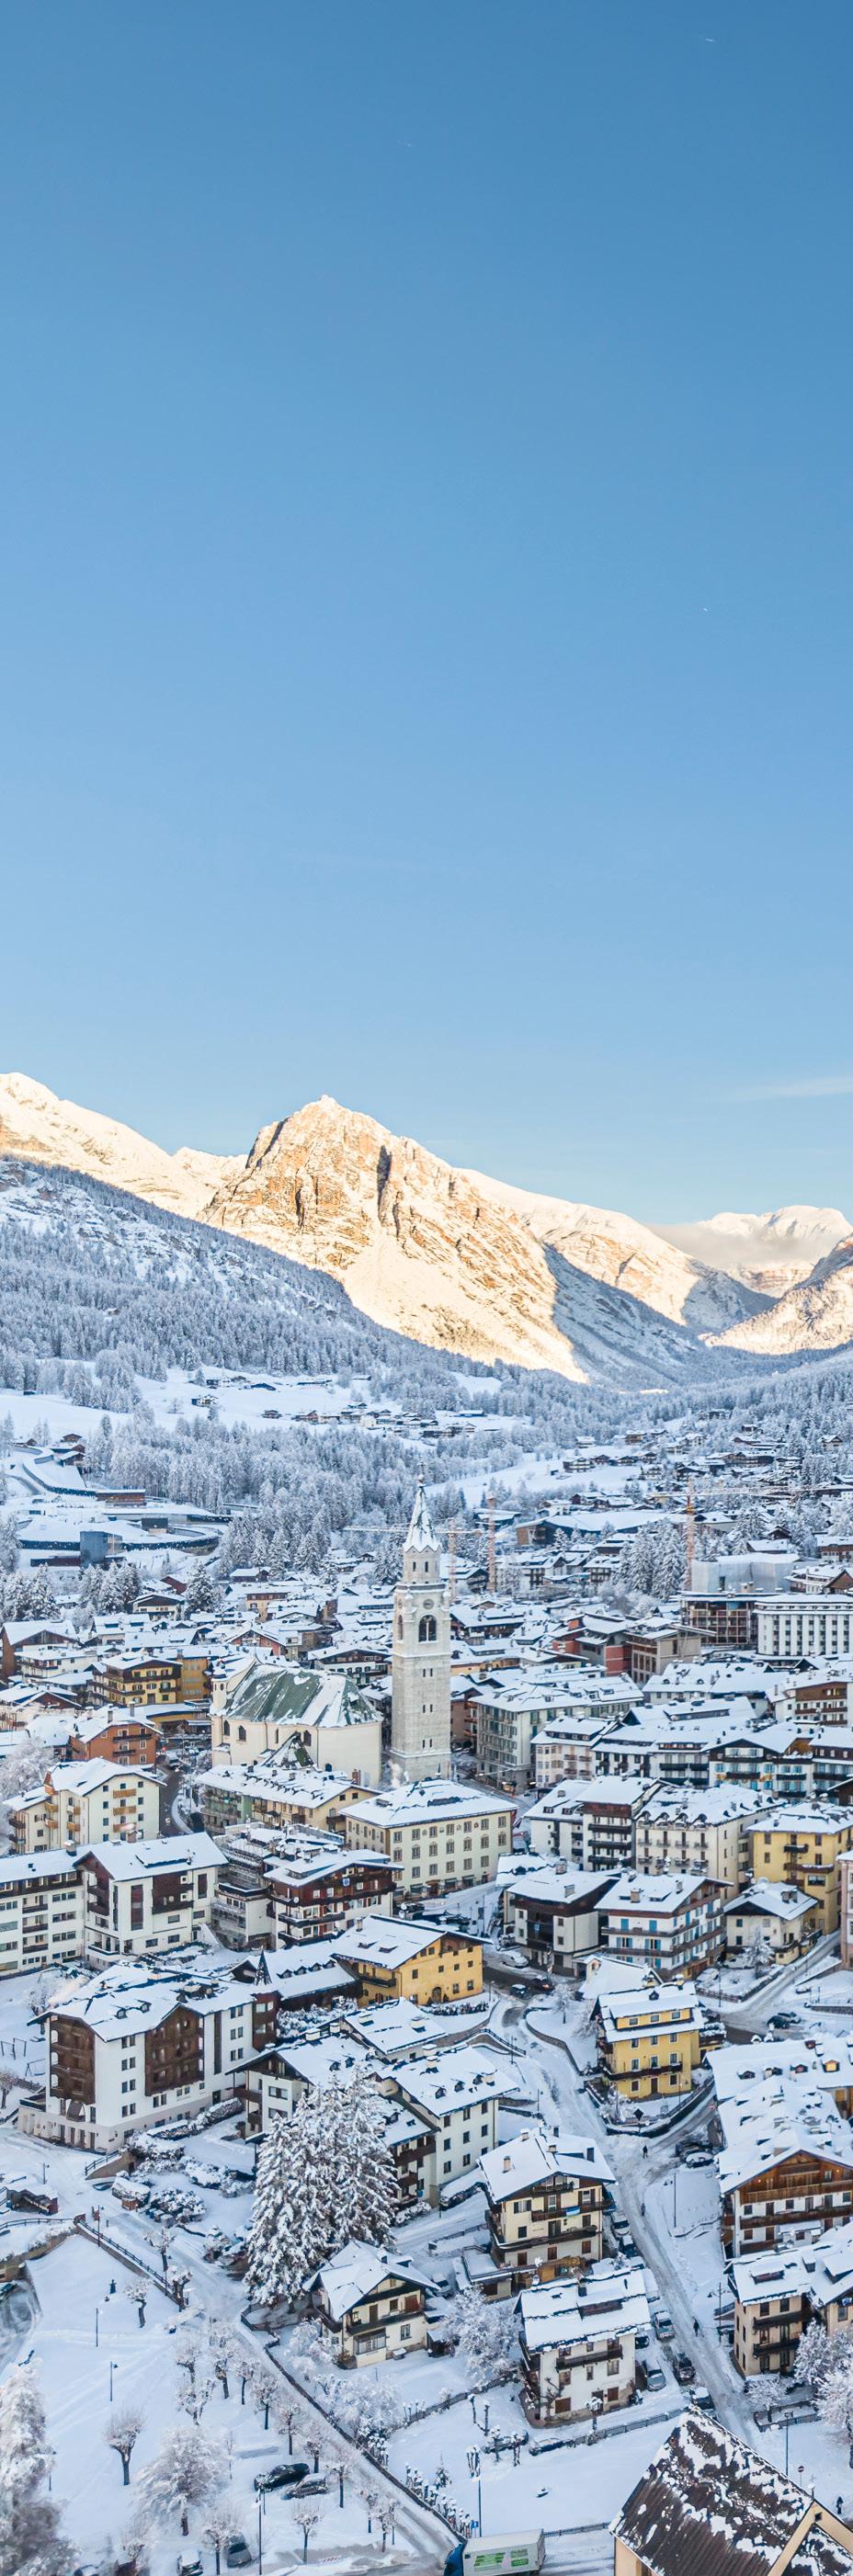
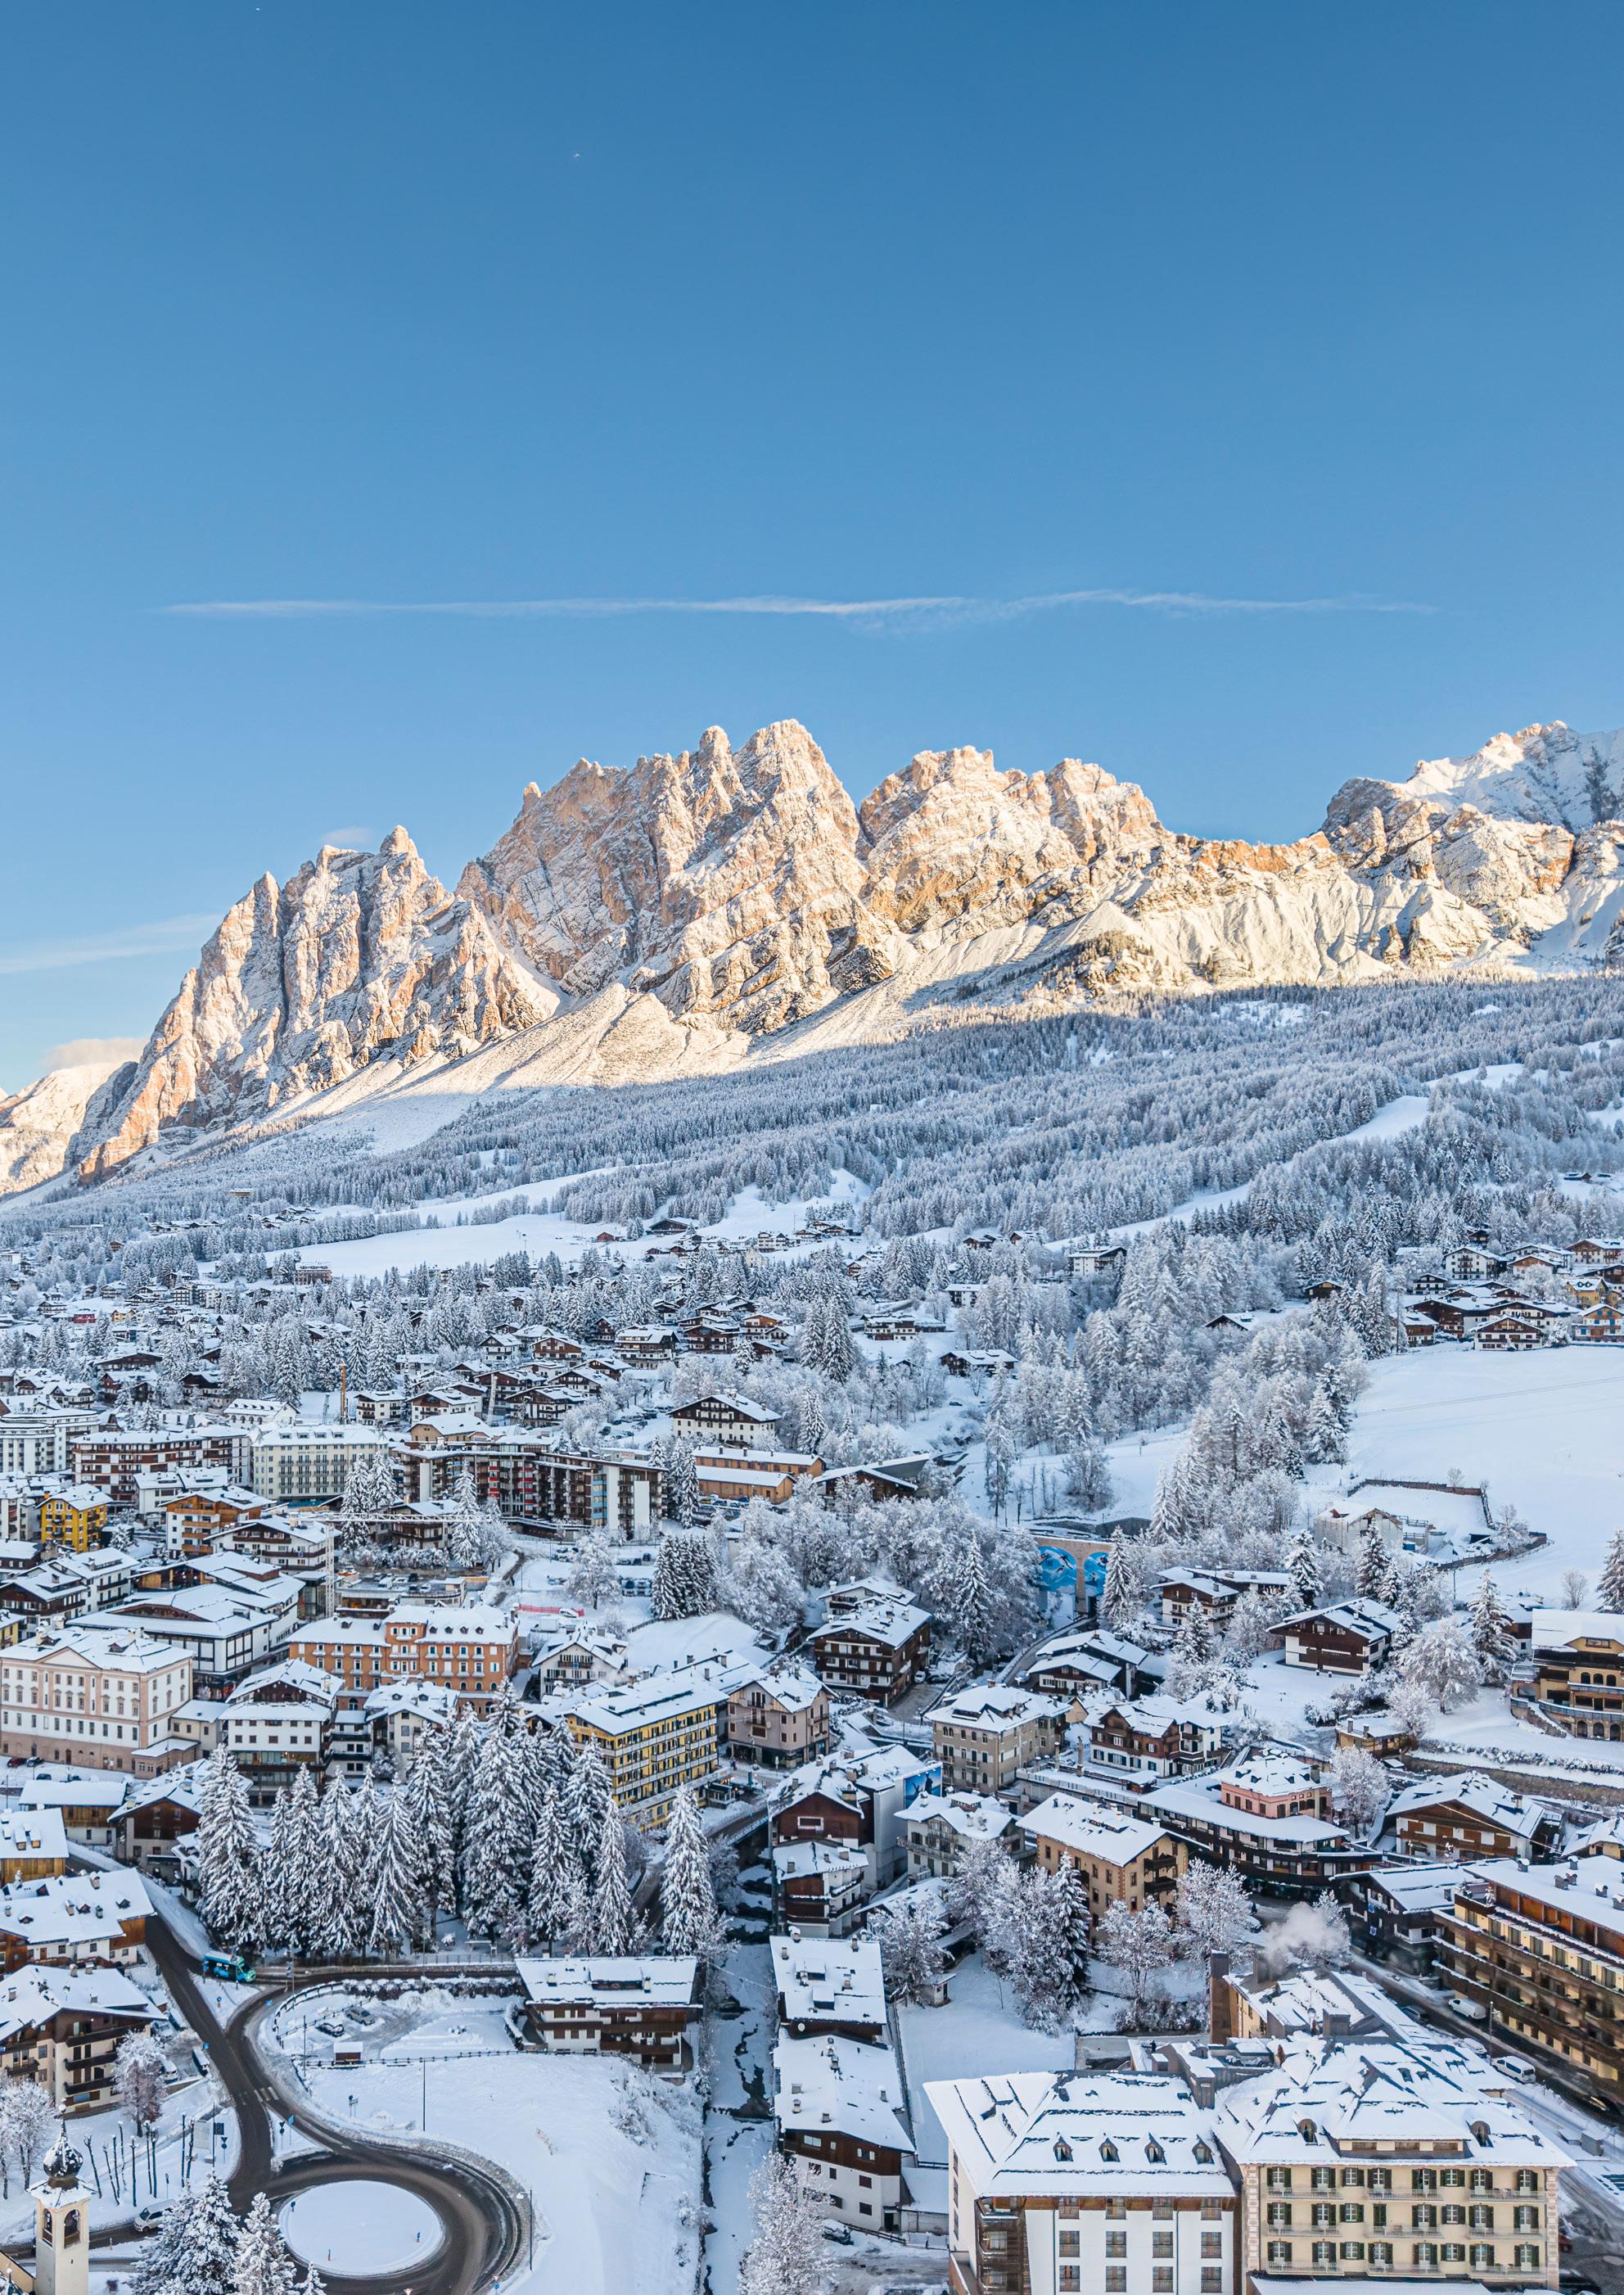
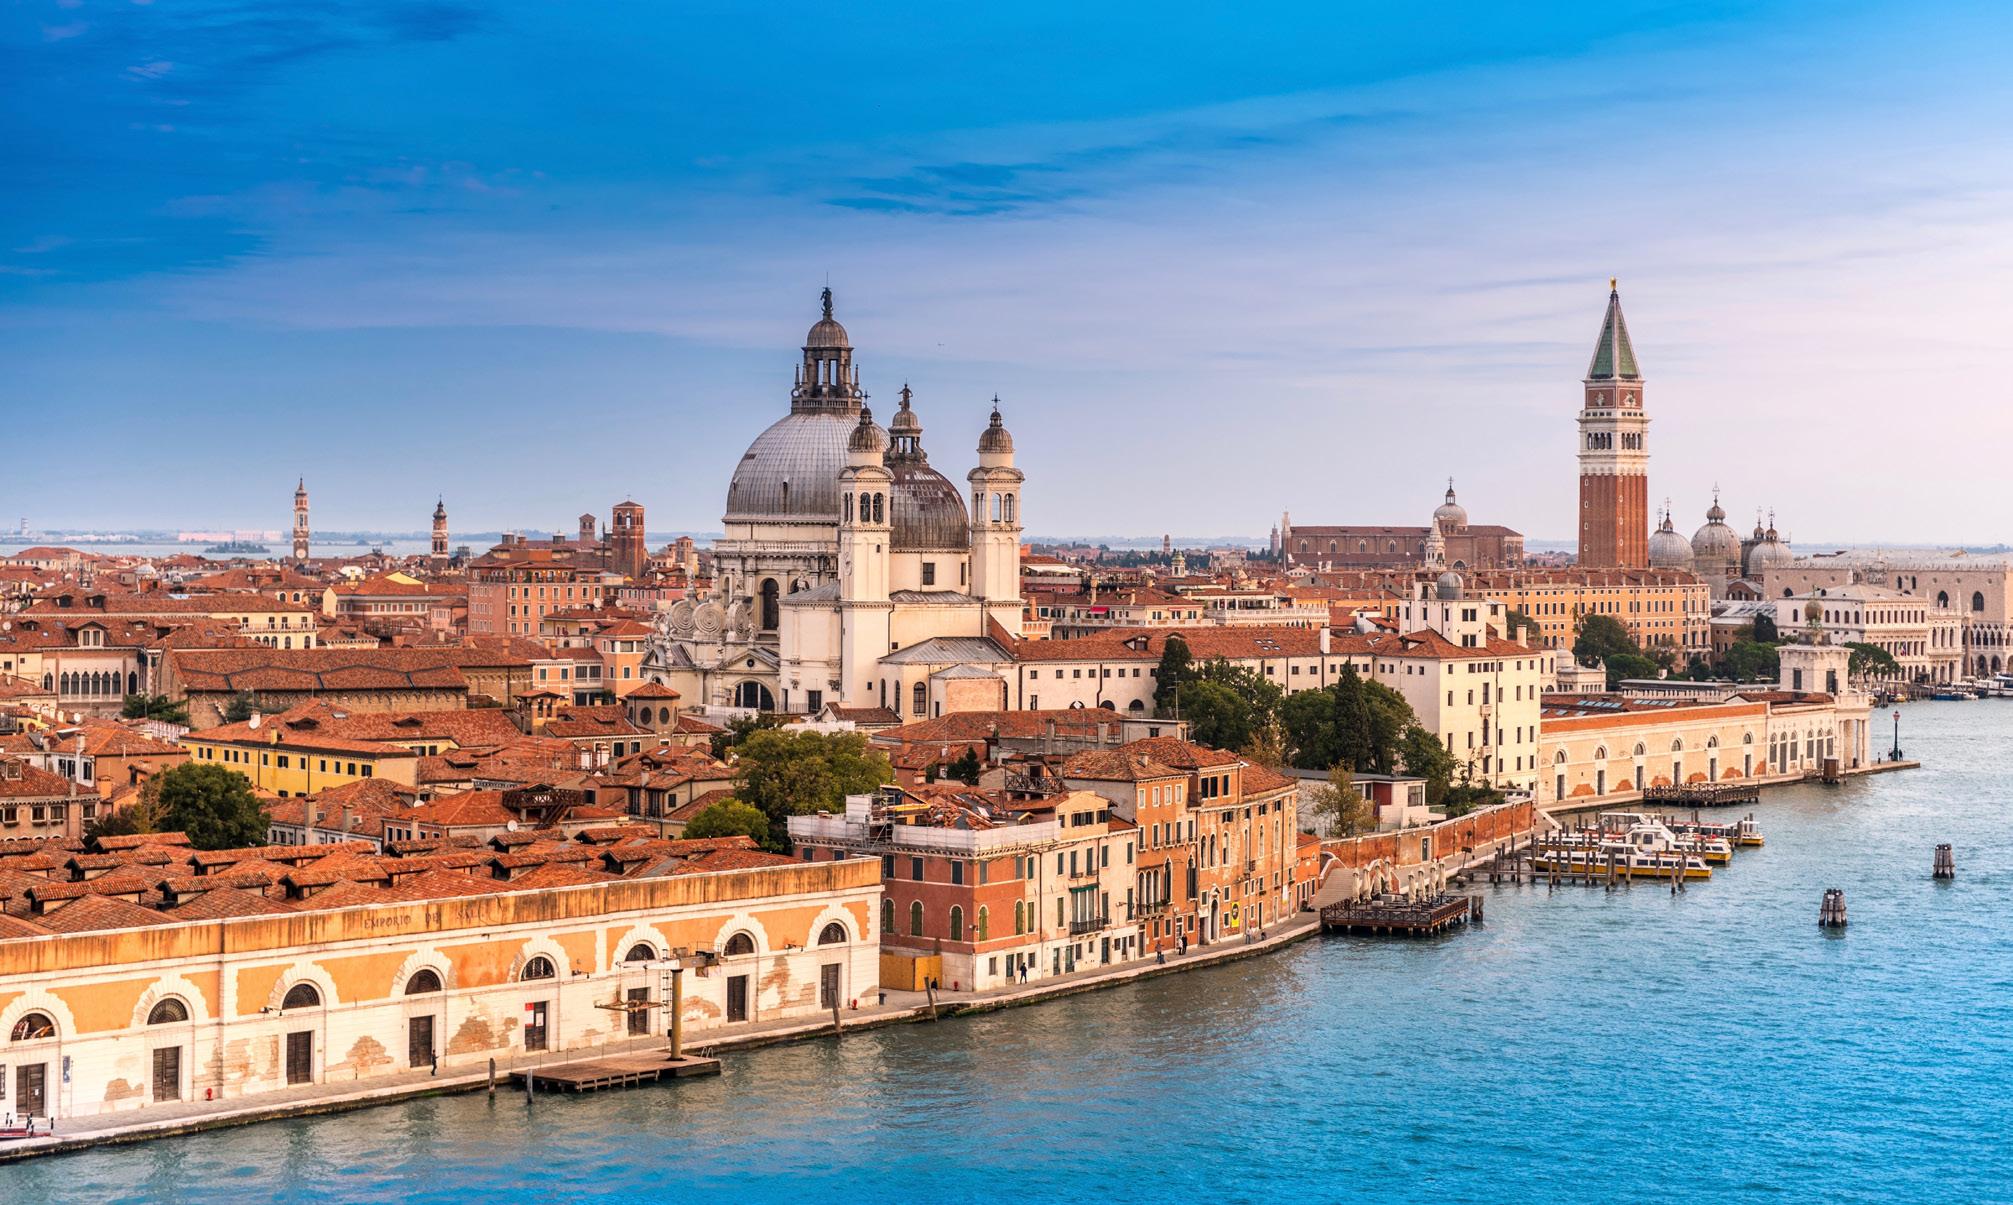
In Veneto, a strong polarization emerges between lifestyle and urban markets: Venice is supported by international demand with prices reaching €20,000 per sqm, while the Venice Lido stops at €7,000. In tourist destinations like Cortina d'Ampezzo, top prices reach €24,000 per sqm, reflecting the scarcity of prime real estate and the interest
68 %
in prime second homes. Lake Garda (Bardolino-Peschiera) maintains a demand focused on quality, with tops up to 10,000, while cities such as Padua, Verona, and Treviso show more balanced growth, linked to energy efficiency, services, and accessibility.
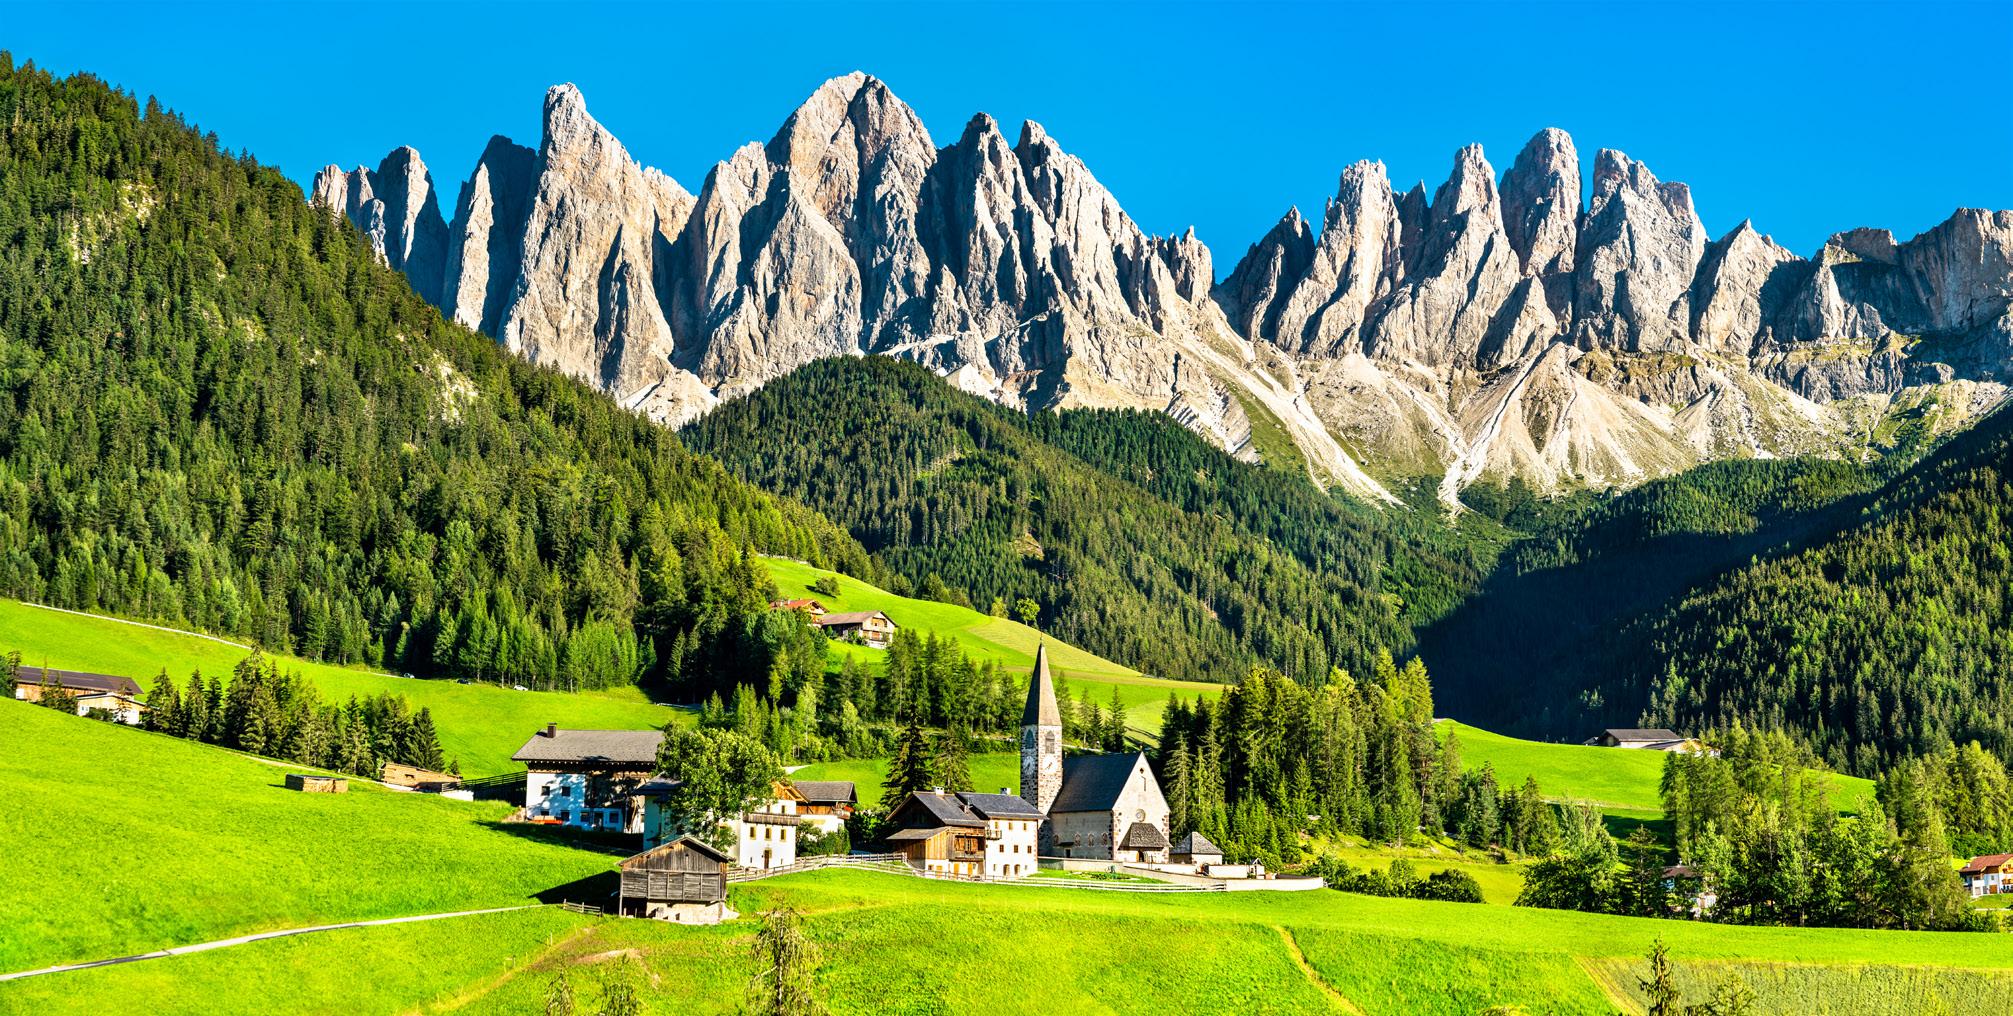
In Trentino-Alto Adige, Alpine markets remain among the most robust and expensive in Italy: in Bolzano and Bressanone, prices peak at €12,500 and €13,000 per sqm, respectively, while in the tourist areas of Brunico and Alta Badia, prices reach €15,000 per sqm. Trento also shows high values, with tops up to €19,000 per sqm. Overall, common drivers are limited supply, real estate quality, and international demand, with prospects for stability or selective growth in 2026.
The outlook for the rest of 2026 is overall positive, but oriented towards selectivity. The prime and high-end segments will continue to benefit from solid demand,
Italian and foreign buyers
Source: Engel & Völkers Italy
supported by both high-spending domestic buyers and international buyers in lifestyle and tourist destinations. A general consolidation of values is expected, with dynamics more closely linked to the availability of new or refurbished products and energy efficiency. In the Alpine and Lake markets, the shortage of quality supply is expected to continue to support prices, while in urban and coastal locations greater attention is expected to be paid to the correct positioning of market values. Among the main factors that can influence the scenario are the trend in interest rates, the macroeconomic context and infrastructure investments. Overall, the scenario remains oriented towards stable volumes and targeted growth in prime locations.
Origin of foreign buyers NE area
Source: Istat e Engel & Völkers 6-11K
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
The prime market in Bolzano and its province remains solid, with prices among the highest in Italy and continued growth in demand, while supply remains insufficient to meet demand. Prices are rising, particularly in the prime and high-end sectors, reaching very high values, up to €11,000–12,500 per sqm in the most sought-after areas, confirming the strong pressure on the prime segment, which accounts for 60% of transactions. Sales times often exceed six months, due to greater caution on the part of buyers, influenced by the cost of mortgages and the high threshold for entry to the market. The typical buyer is looking for penthouses, villas, and energy-efficient homes with gardens, views, and elevators. Demand is 40% international, a factor that strengthens the area's attractiveness. For the rest of 2026, prices are expected to remain stable or moderately growing, supported by solid demand but with caution linked to affordability and local economic conditions.
Sales by type of investment
Source: Engel & Völkers
AVERAGE BUDGET IN PRIME SEGMENT
PURCHASES WITHOUT HOME LOAN
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
The prime residential market in Bressanone is experiencing moderate growth, with supply increasing and prices marking +4–7% in all segments. New or renovated properties range from €4,500–7,000 per sqm in the city centre, with top prices settling at €13,000 per sqm. In the semi-central area (€3,500–€5,000 per sqm) and in the rest of the market (€3,500–€6,000 per sqm), with overall stable trends compared to 2024. The times from first contact to proposal are homogeneous for the various market segments (3–6 months). The structure of demand by purchase purpose highlights a prevalence of first homes (60%), followed by second homes (30%) and investments (10%). About 20% resort to mortgages. Demand is focusing on apartments, penthouses, and villas with terraces or outdoor spaces. The main driver for foreign buyers is the quality of life in the area. For 2026 H2, the expected scenario is one of stability.
PURCHASES WITHOUT HOME LOAN
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
Source: Istat e Engel & Völkers 5-10K €/sqm +4/+7%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
The real estate market in Brunico, Alta Badia, and Alta Val Pusteria is clearly segmented, with an increasingly highquality offering. In the prime segment, average prices range between €5,000 and €12,000 per sqm, while the high-end range varies between €10,000 and €15,000 per sqm. Average sales times range between 3-6 months. Demand is generally stable, supported mainly by a mature target between 45 and 54 years old, made up of 70% Italians and 30% international buyers, particularly Europeans, strongly interested in new or refurbished solutions. Must-haves include panoramic views, balconies, high energy rating, and privacy. Despite the expected stability for the rest of 2026, prices continue to rise due to resilient demand and limited supply. The scenario remains influenced by taxation, international stability, and urban planning regulations, key drivers for this area in the heart of the Dolomites.
AVERAGE BUDGET IN PRIME SEGMENT
PURCHASES WITHOUT HOME LOAN
by type of investment
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
4,5-5,8K €/sqm +1/+3% 500-800K €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
8,6K €/sqm 90 %
Source: Istat e Engel & Völkers
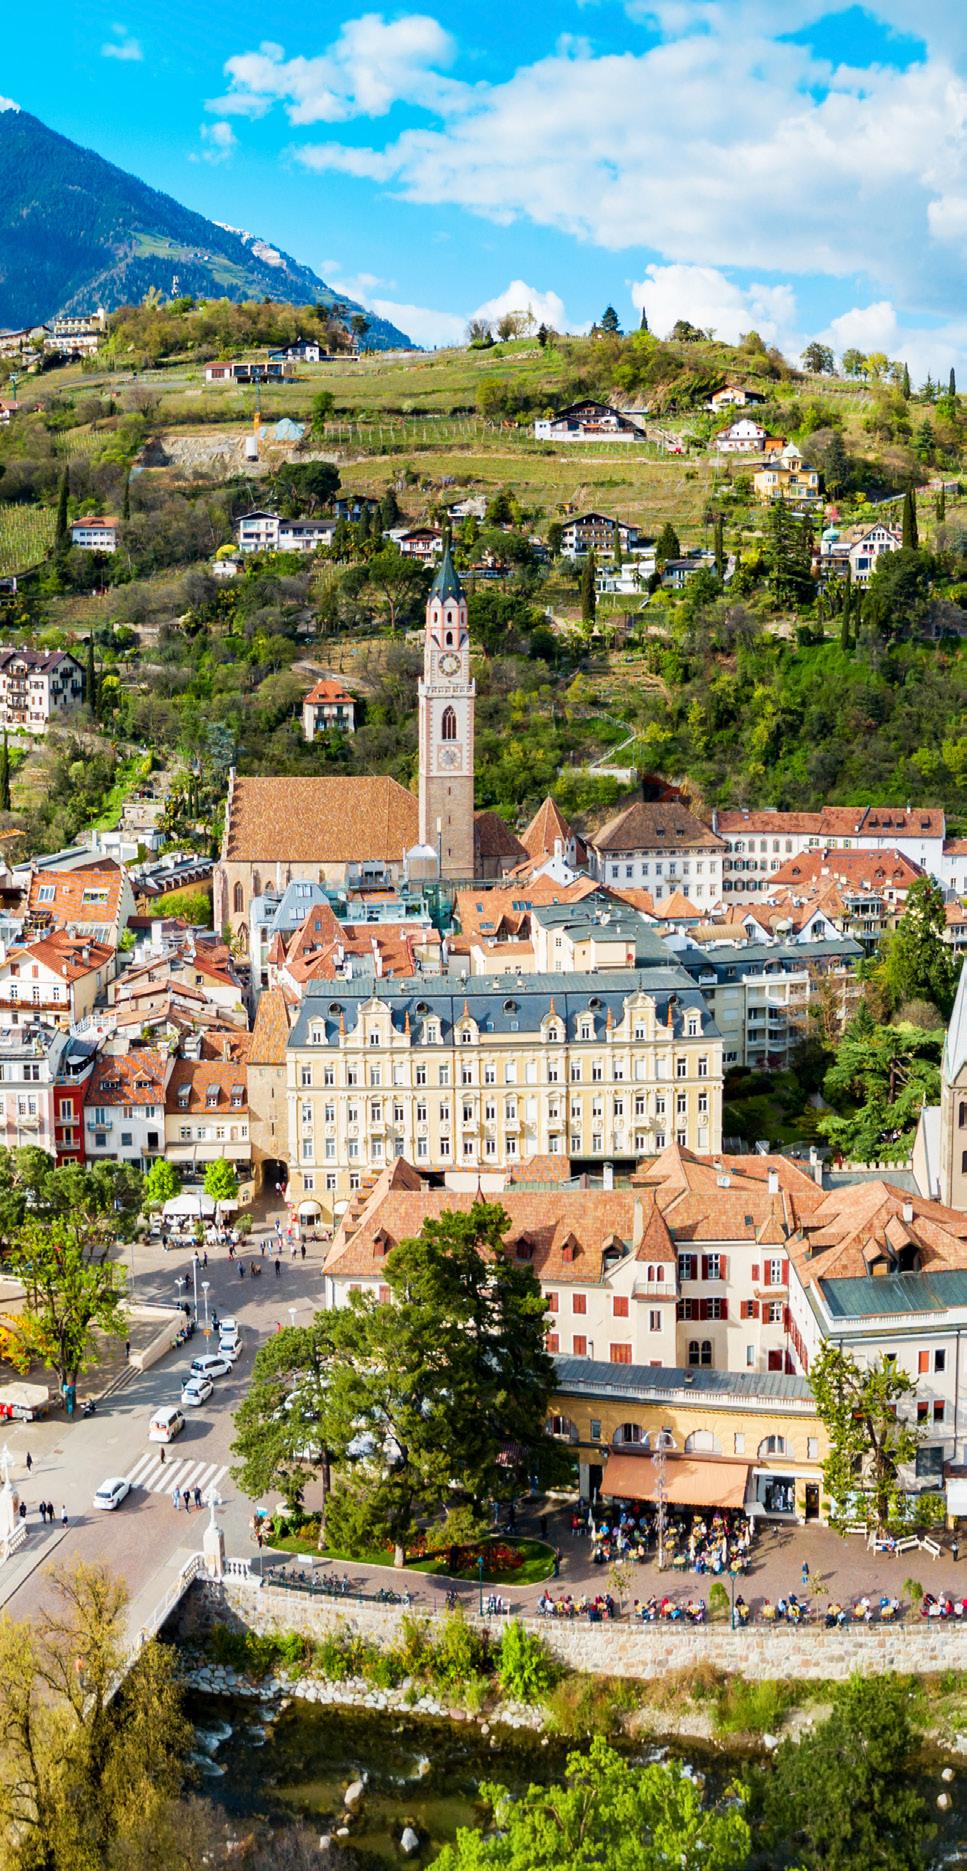
Merano's prime real estate market is generally stable, with demand slightly declining and supply remaining unchanged.
Prices show a differentiated trend: the intermediate segment, which contains the majority of sales, is substantially stable, while prime and high-end properties are recording a moderate increase of between 1% and 3%.
New or renovated properties continue to attract the greatest interest, with prices in central areas reaching an average maximum of €5,800 per sqm and a peak of €7,000 per sqm. Sales times range between 3 and 6 months in the central and semi-central areas, exceeding 6 months in the rest of the market. Demand remains solid, supported by both Italian buyers and a significant international component, with second homes accounting for 50% of purchases. The quality of the properties, international demand, and quality of life have the greatest impact on market dynamics, while terraces, views, and parking spaces are among the most sought-after requirements.
PURCHASES WITHOUT HOME LOAN
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
4-10K €/sqm +1/+3%
EUROPEAN BUYERS OVER
AVERAGE BUDGET IN PRIME SEGMENT
800K-1,2M €
PURCHASES WITHOUT HOME LOAN
19K €/sqm 70 % 30 %
Source: Istat e Engel & Völkers
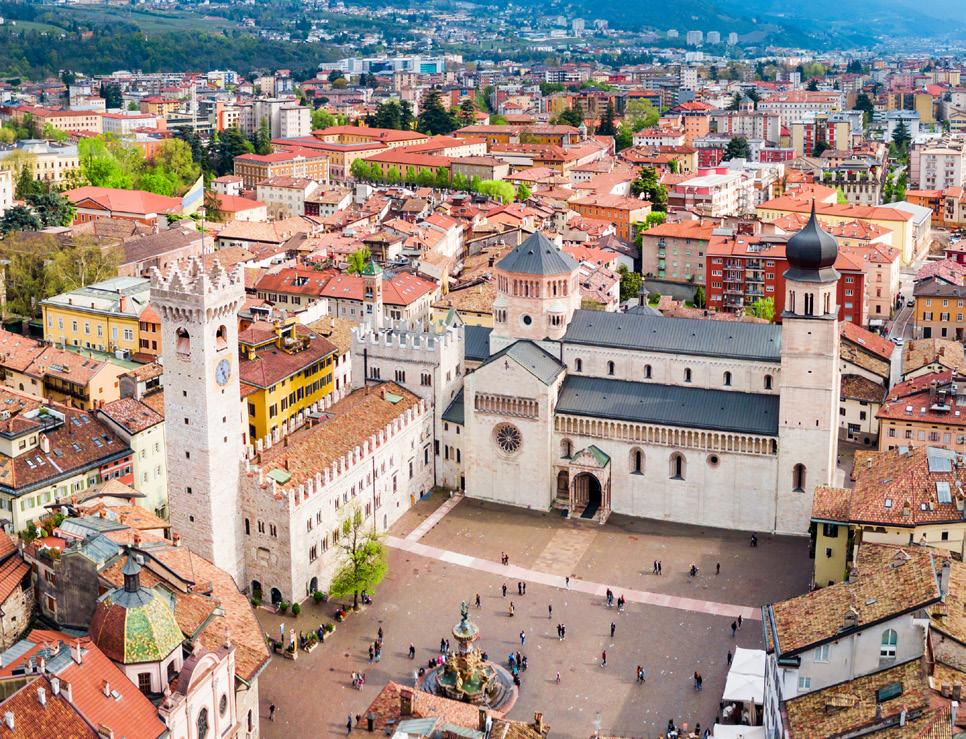
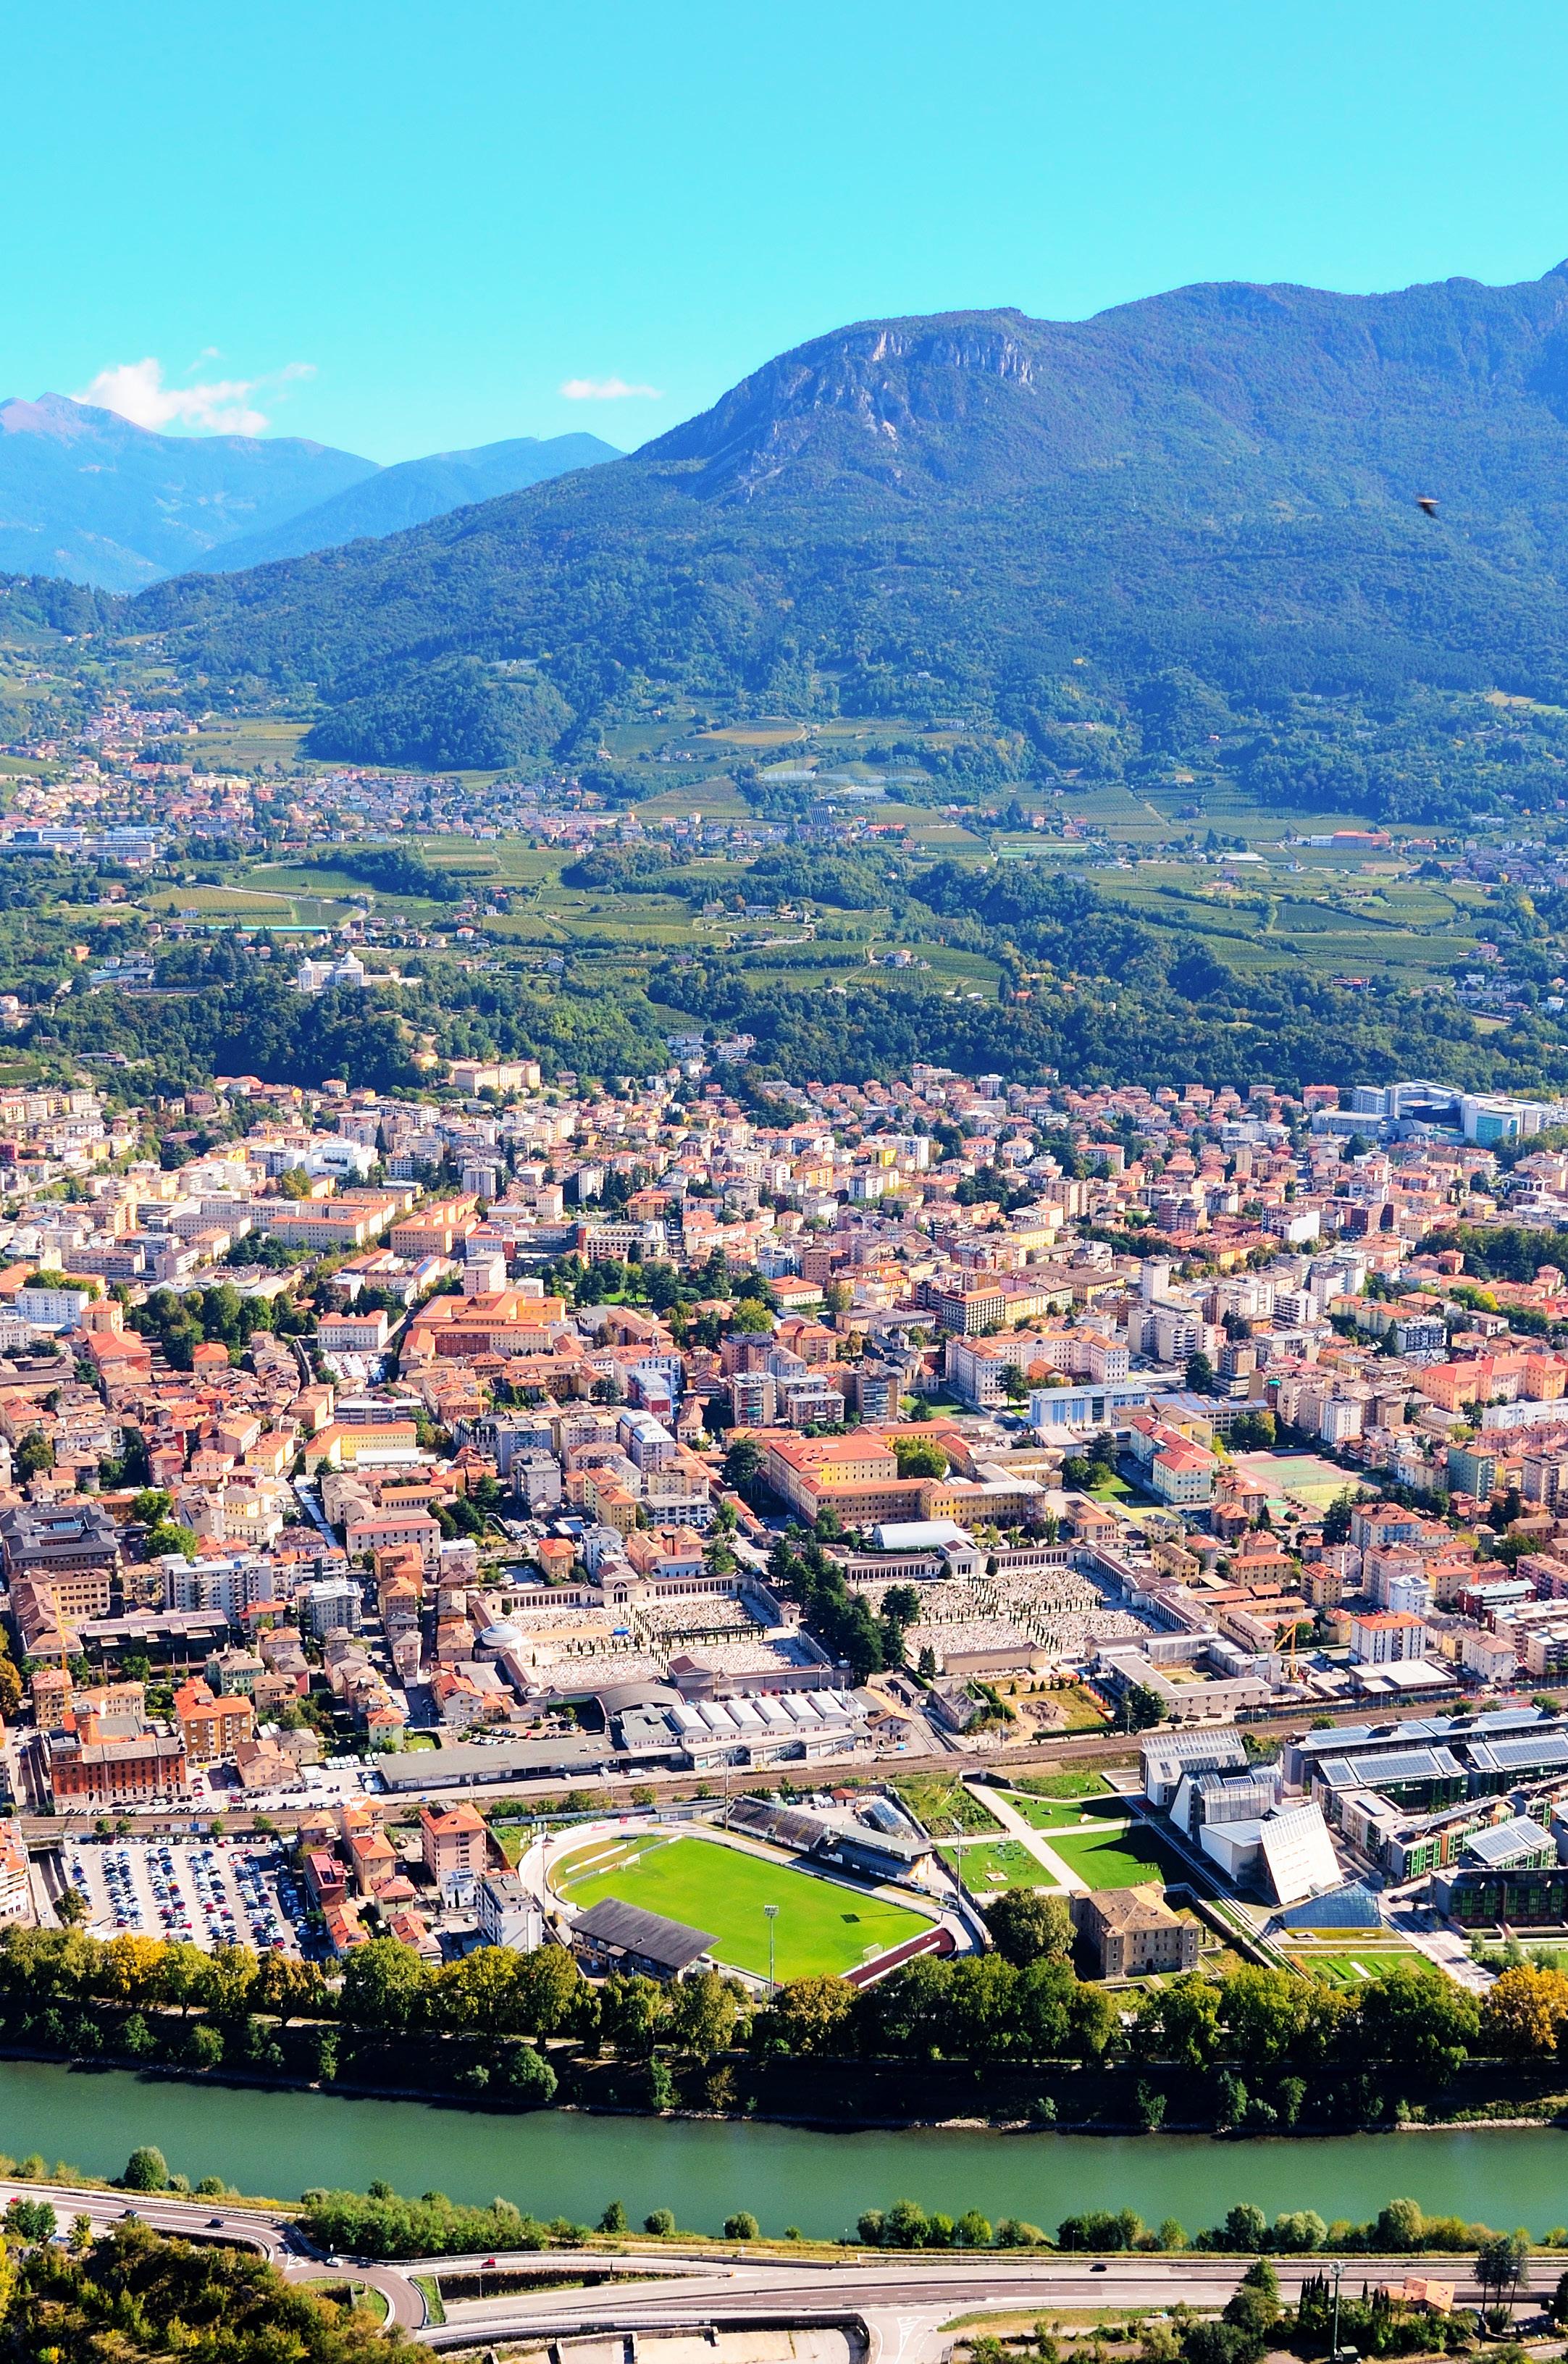
Trento's prime residential market remains stable overall, with solid demand and slightly declining supply. The distribution of sales sees 55% concentrated in the prime segment, 25% in the intermediate segment and 20% in the high-end segment, out of an annual total of between 50 and 100 transactions. The changes in estimated average prices indicate a limited growth in the intermediate and prime segments (+1/3%) and a more marked increase in high-end (+4/7%). Demand is driven primarily by Italian buyers (85%), with a limited foreign component (15%), almost exclusively European. The most requested types are apartments, villas and new buildings. The most sought-after features remain a terrace or balcony, garden, and parking space. Stability is expected in the intermediate and prime segments for 2026 H2, with possible further growth in high-end. The factors that could have the
greatest impact are international stability and the dynamics of reputation and territorial attractiveness.
EUROPEAN BUYERS OVER
1,2-1,5M €
PURCHASES WITHOUT HOME LOAN
20K €/sqm
Source: Istat e Engel & Völkers
Venice's residential market remained generally stable in 2025, amid moderate growth in demand and a progressively declining availability of properties. Market values range between €4,000 and €5,000 per sqm for the intermediate segment, between €5,000 and €8,000 per sqm for the prime segment, and up to €20,000 per sqm for the most exclusive solutions, with average annual increases of around 1-3% across all segments. The market is largely driven by demand for second homes and investments, which together account for 80% of purchases, with the incidence of mortgage-backed sales remaining entirely marginal. There is a strong preference for quality, welllocated properties, with greater selectivity in demand compared to the asking price. In the intermediate market segment, decision-making times are longer, while in the prime and high-end segments, cash purchases with longterm investment purposes prevail.
Buyers are predominantly international, aged between 55 and 65, with a dominant share of European origin, attracted by the unique urban context, the quality of life, and the city's cultural dimension. The most sought-after types are used but habitable apartments, preferably with distinctive features such as open views, terraces or outdoor spaces, and an elevator. Average take-up times are short in the most prestigious central areas, ranging between 1 and 3 months. The outlook for 2026 H2 predicts stable demand, with the main drivers being the fiscal framework, international stability, and major events that periodically consolidate the destination's global appeal, such as Carnival, the Biennale, and the Venice Film Festival.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
Source: Istat e Engel & Völkers 4-5K €/sqm
TOP PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
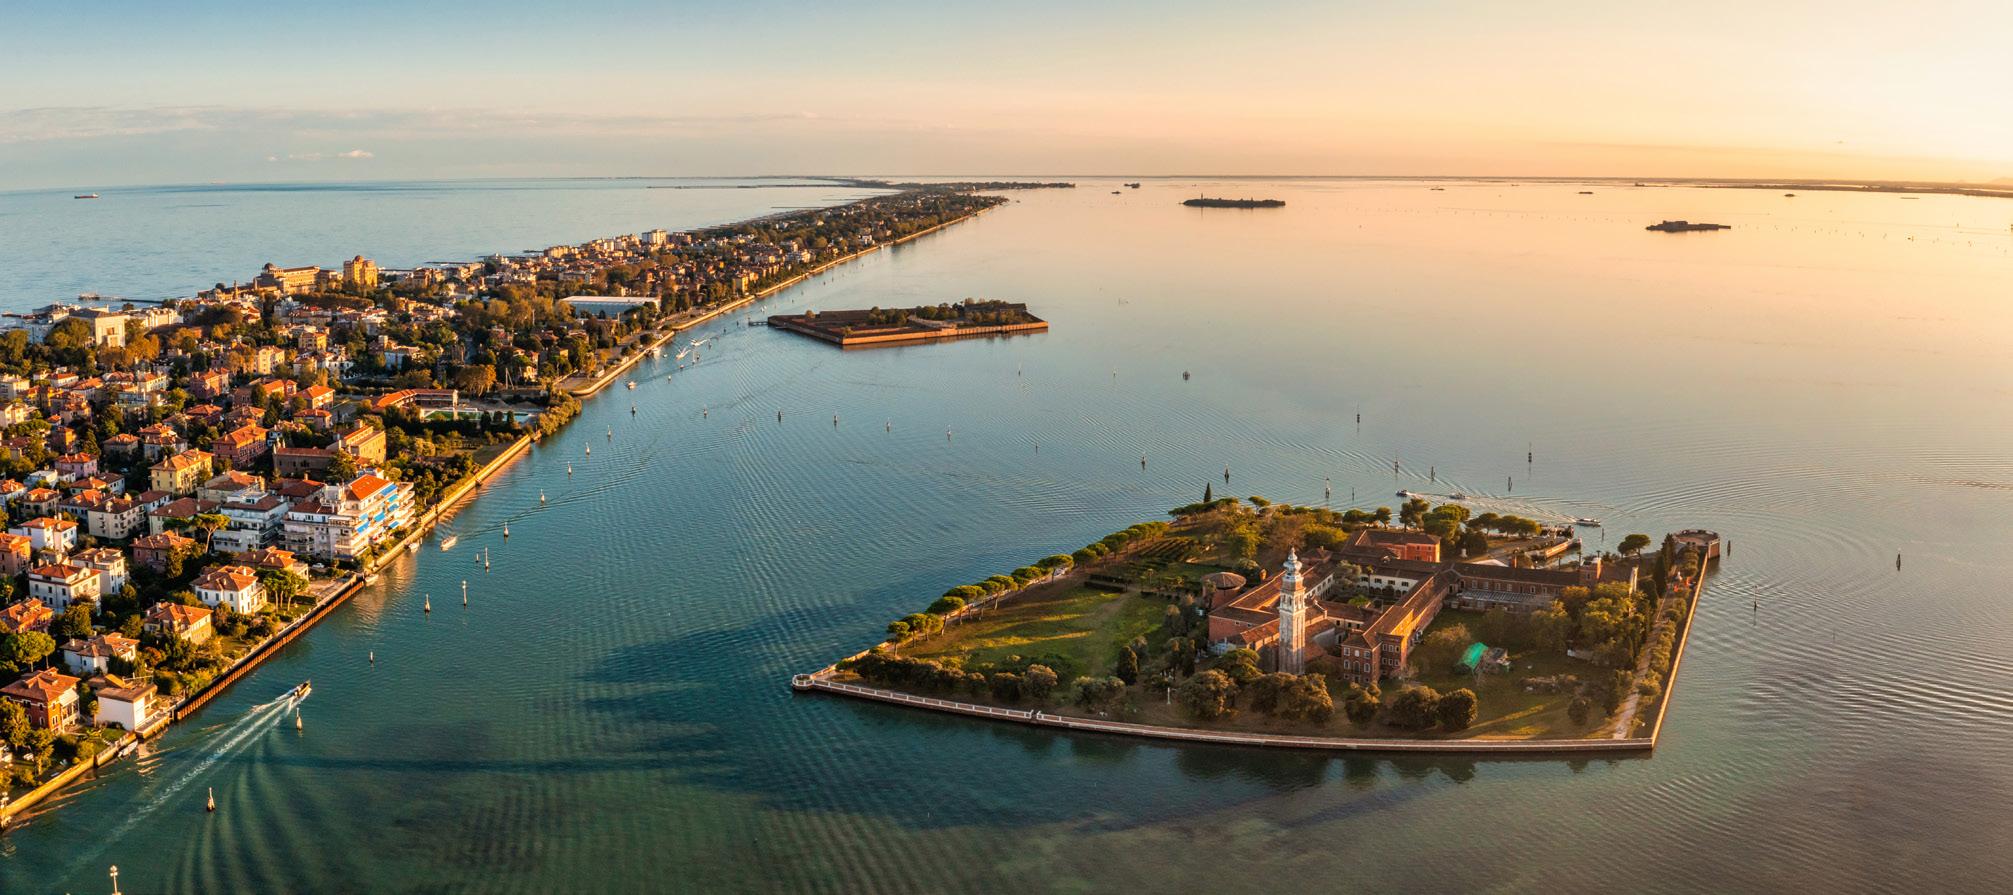
The Venice Lido residential market showed substantial stability in 2025, supported by consolidated demand and a balanced supply. Market values range between €2,500 and €3,000 per sqm for the intermediate segment, between €3,000 and €5,000 per sqm for the prime segment, and up to €10,000 per sqm for the most exclusive solutions, with average annual increases of around 1-3% across all segments. Demand is driven by second home sales, which account for 80% of the total. Buyers are largely international, primarily European, attracted by the surrounding environment, the quality of the properties, and a glamorous seaside atmosphere that strengthens the island's appeal in the mid-to-high end segment. Preferences are oriented towards new or recently renovated homes, penthouses, and villas with terraces, outdoor spaces, views, and parking spaces. Average sales times range between 1-3 months.
For 2026 H2, expectations indicate growing demand in the prime and high-end segment.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
4,5-6K €/sqm -1/+0%
EUROPEAN BUYERS OVER INTERNATIONAL
6,5K €/sqm
Source: Istat e Engel & Völkers
40 %
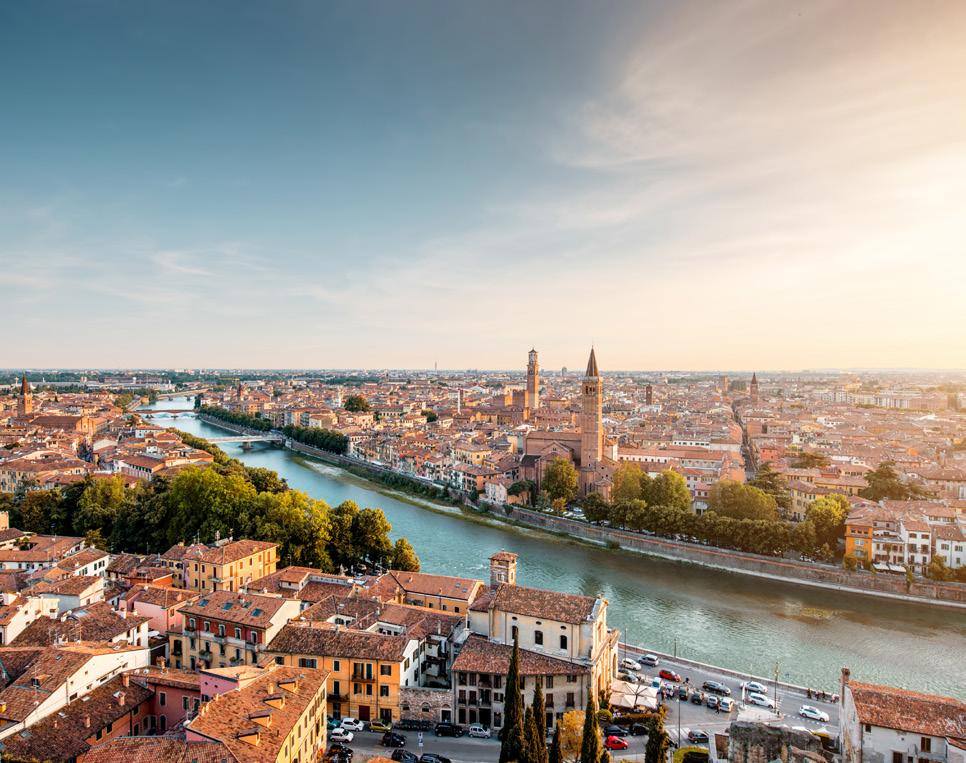
Verona's residential market is showing overall balanced dynamics, with moderately growing demand and stable supply. Price changes show a differentiated trend between segments: in the intermediate range, an increase of between 1 and 3% is observed, while in the prime and highend segments a tendency towards stability prevails. The composition of demand remains strongly oriented towards first-time home purchases, which represent approximately 60% of transactions, with a significant national component accounting for approximately 90%. Interest is primarily focused on habitable used properties in central and semicentral areas, with particular attention to properties that offer terraces, parking spaces, and elevators. The average absorption times, between three and six months, indicate a selective but still liquid market, supported by a good level of purchasing power.
For 2026 H2, stable demand is expected in the intermediate
AVERAGE BUDGET IN PRIME SEGMENT
500-800K €
PURCHASES WITHOUT HOME LOAN
80 %
and high-end segments, while a slight increase is expected in the prime segment, supported by product quality and new infrastructure under development.
Italian and foreign buyers
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
4,5-5,5K €/sqm +4/+7% 500-800K €
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
6,5K €/sqm 85 % 70 %
Source: Istat e Engel & Völkers
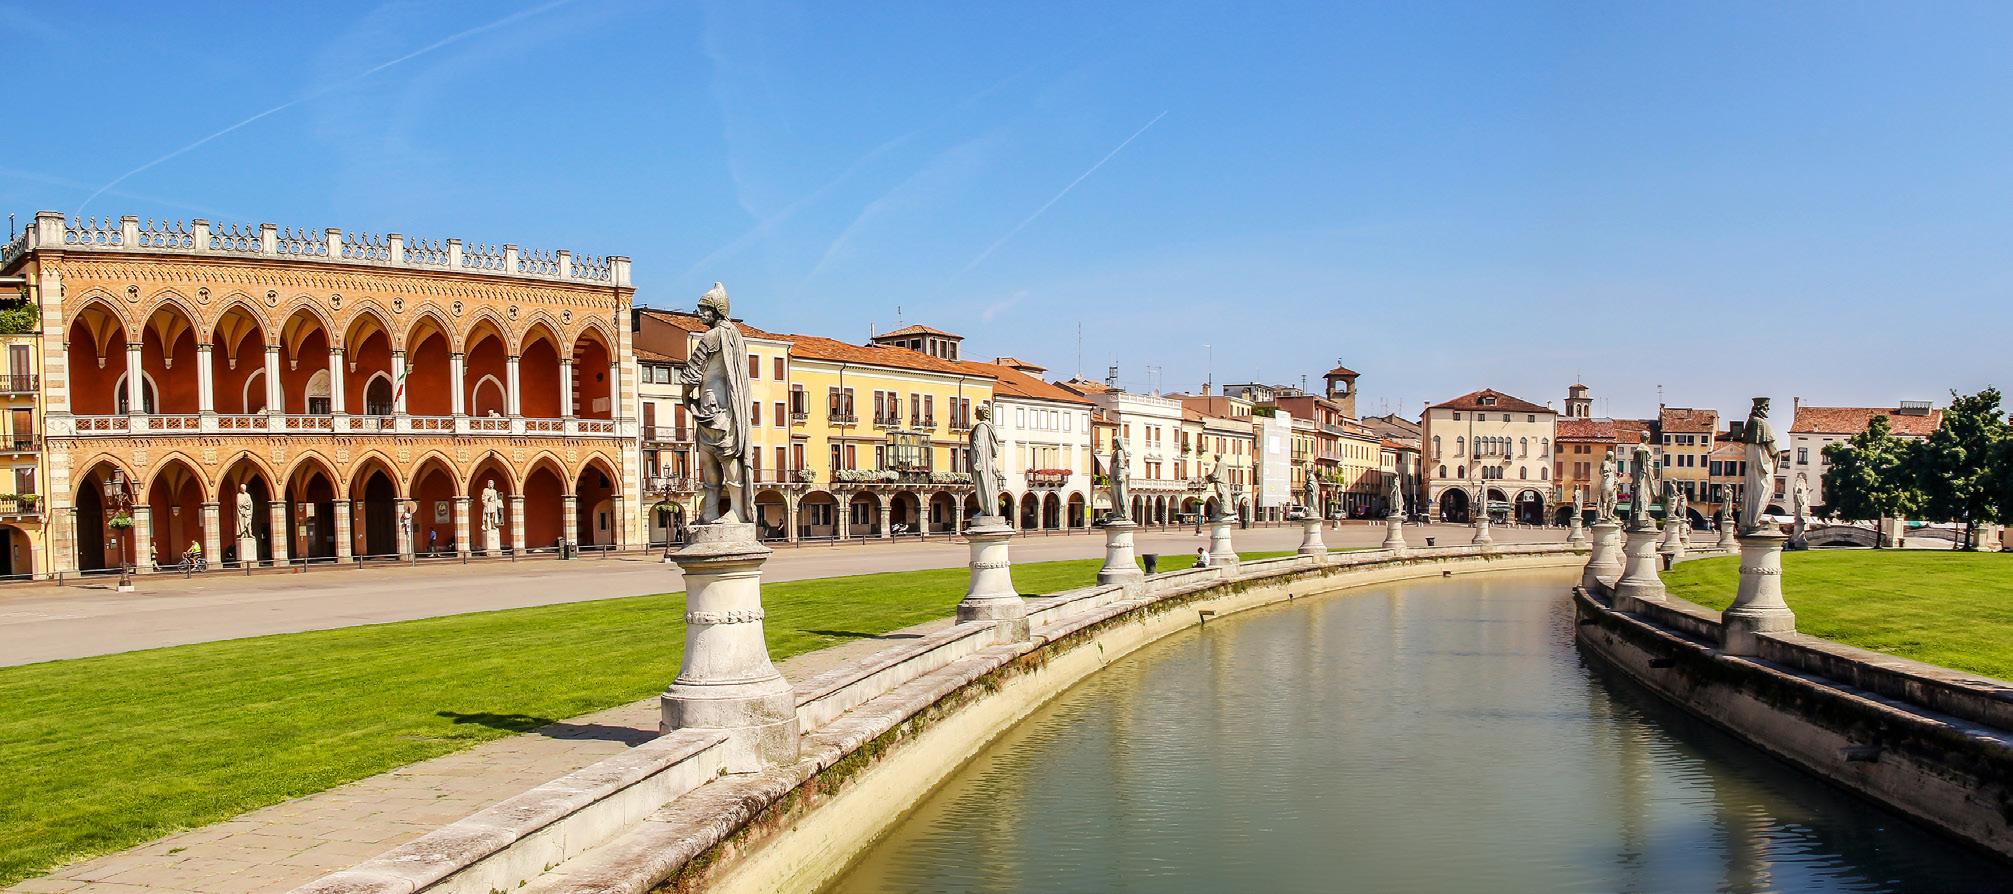
The prime residential market in Padua is showing moderate growth in demand while supply remains stable. The prime segment is predominant, with 55% of sales and records an estimated price variation between 4 and 7%, more accentuated than the intermediate segment (+1/3%). The values in the prime segment range between €2,900 and €4,000 per sqm. Decision times are very quick in central areas (less than a month) and become more relaxed the further away from the centre you go. Buyers, predominantly Italian (90%), show an increasingly selective profile, attentive to quality, energy efficiency and location, with a propensity to purchase apartments, penthouses and new buildings. Expectations for 2026 H2 are for growth in the intermediate segment and stability in the prime and high-end segments.
Factors that could have a positive impact include more or less favourable taxation, the construction of new
Sales by type of investment
2025 Data infrastructure, and the evolution of the regulatory and urban planning framework.
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,5-3,3K €/sqm +1/+3% 500-800K €
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
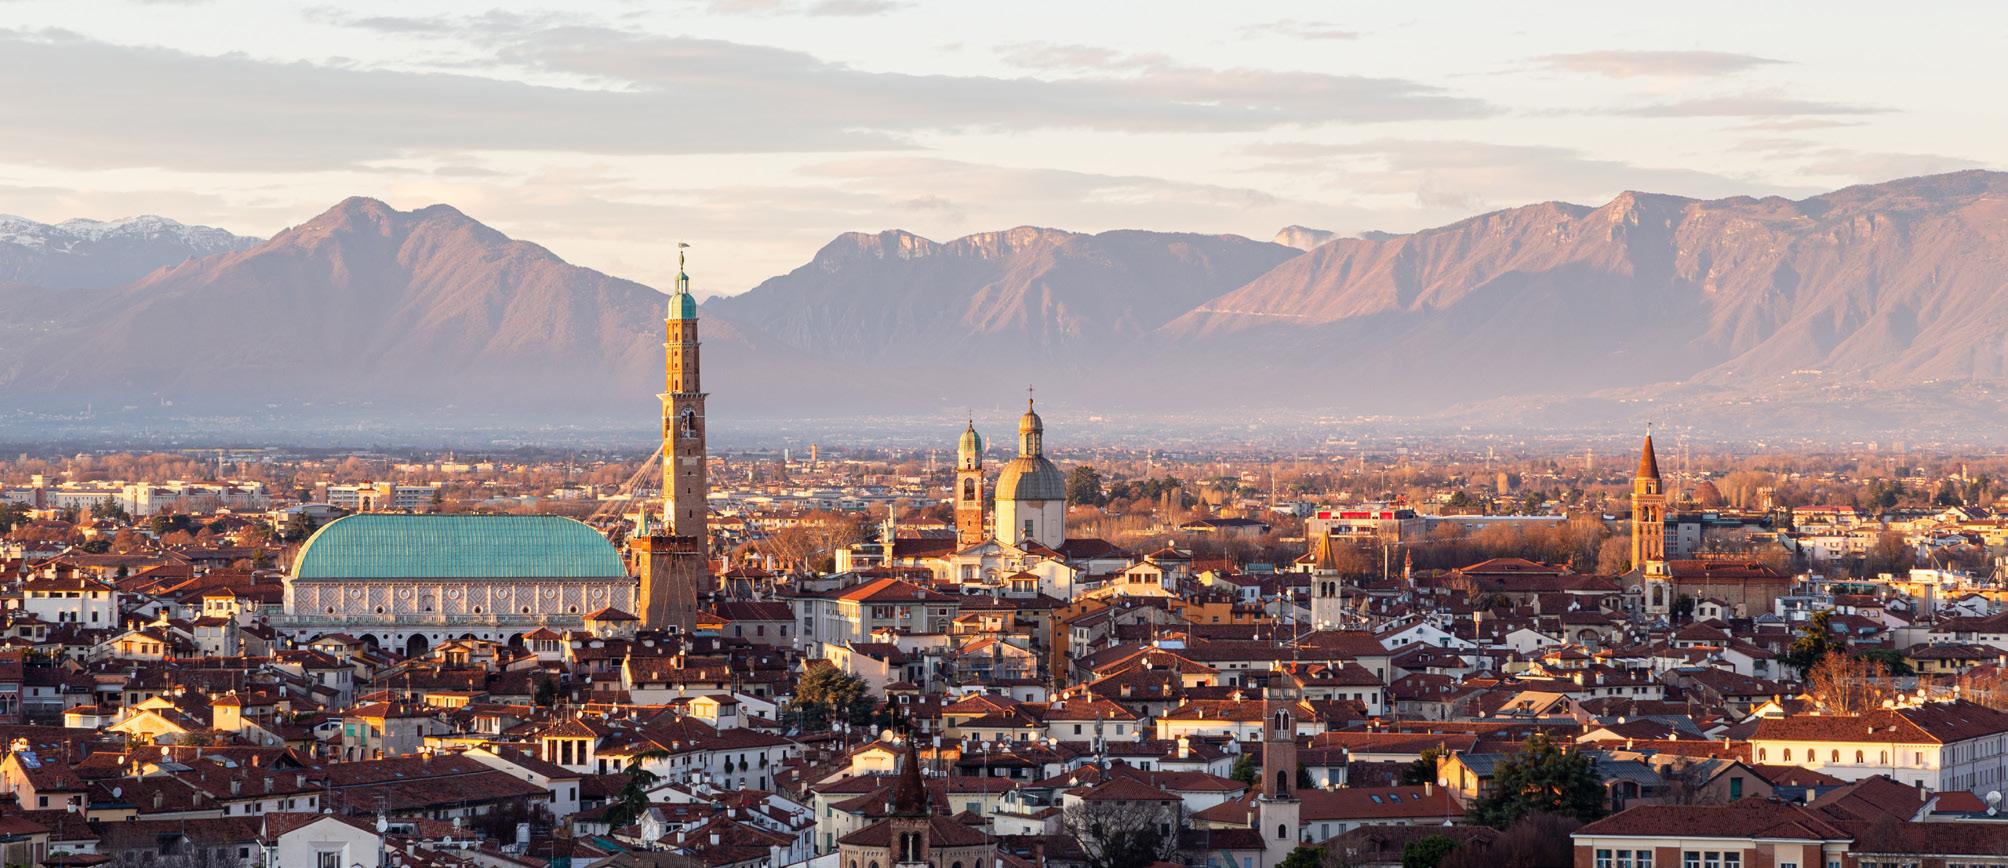
In Vicenza, demand for prime properties has shown marked growth, not accompanied by a corresponding increase in supply, which has remained stable. This pressure is reflected in an upward trend in prices in the intermediate and prime segments, both of which are estimated to grow between +1% and +3%, while high-end remains substantially unchanged. The prime segment ranges between €1,800 and €2,400 per sqm, while high-end prices range between €2,500 and €3,000 per sqm. The market is driven almost entirely by Italian buyers (92%), with first homes being the main reason (65%) and widespread use of mortgages (60%). Buyers are increasingly focusing on value for money and energy efficiency, showing particular interest in apartments, villas, and new builds. For 2026 H2, growth is expected in the intermediate segment and substantial stability in the upper segments. Factors that could have a positive impact in the medium to long term include the
Sales by type of investment
2025 Data dynamics of mortgage interest rates and greater stability in the international scenario.
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
4,5-5,5K €/sqm +4/+7% 500K-1,2M €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
6,5K €/sqm 85 % 50 %
Source: Istat e Engel & Völkers
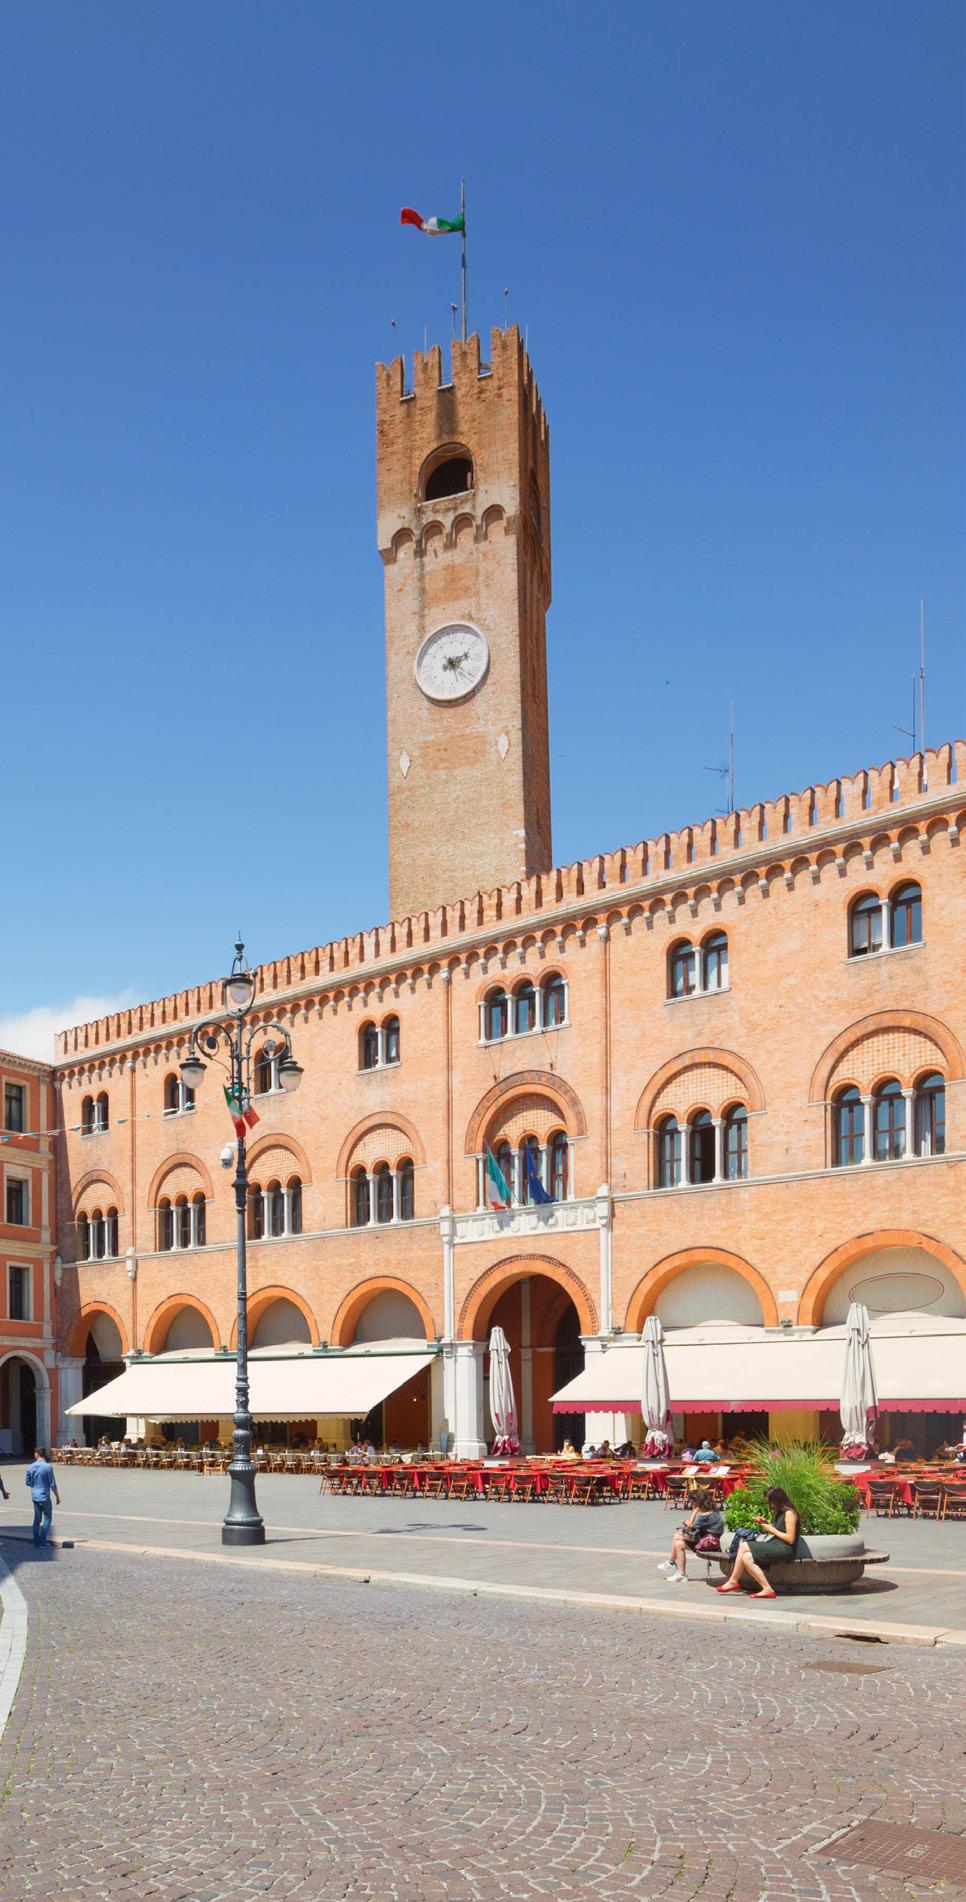
Treviso's prime real estate market is generally stable, with demand slightly declining and supply remaining unchanged. Sales are concentrated in the prime segment (50%), while high-end accounts for 30% and intermediate for 20%. Prices show limited variations: +1–3% in the mid-range and high-end segment, +4–7% in the prime segment. For new/ renovated properties, prices range between €4,500–5,500 per sqm in the centre (top 6,500), €3,000–3,500 per sqm in the semi-centre (top 4,000) and €2,000–2,500 per sqm in the rest of the market (top 3,000). The sales times are set at 1–3 months in central areas and 3–6 months in other areas. Buyers are 90% Italian, with a small and predominantly European foreign component. Interest is oriented towards apartments and villas, even used ones but in good condition, with attention to terraces, garages, elevators, and energy efficiency. There is a growing appreciation for the quality of life and for neighbourhoods close to the historic centre, considered particularly attractive by more mature buyers.
Sales by type of investment
Source: Engel & Völkers Italy
2-3K €/sqm +1/+3%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
5,5K €/sqm 90 %
Source: Istat e Engel & Völkers
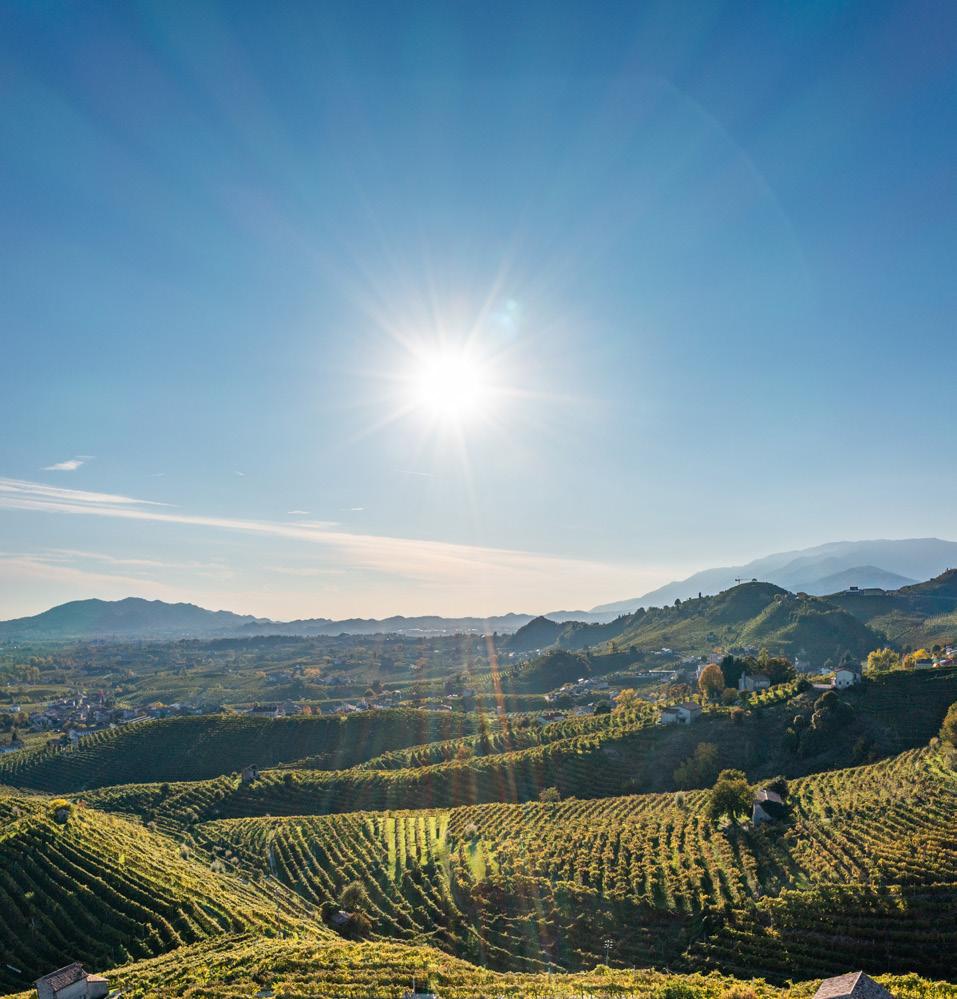
The Prosecco Hills market has a defined segmentation, with a prevalence of the prime (40%) and intermediate (40%) sectors, followed by high-end. In the prime segment, average prices range between €2,000 and €3,000 per sqm, while the intermediate range varies between €1,500 and €2,000 per sqm. Demand, supported by 5-10 annual sales and moderately growing, is aimed at new or refurbished properties as new, with average sales times being rather rapid (3-6 months). The main target is made up of buyers between 45 and 54 years old, 70% Italian and 30% international (European), interested in farmhouses and rustic houses to renovate (70%) or detached villas (30%). Must-haves include a view, garden/outdoor spaces, and a parking space/garage. Despite the stability expected for the rest of 2026, the outlook remains influenced by purchasing power, foreign demand, and quality of life. The allure of the landscape and the prestige of the territory remain the main drivers of transactions in the UNESCO site.
AVERAGE BUDGET IN PRIME SEGMENT
PURCHASES WITHOUT HOME LOAN
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
18-20K €/sqm +10% >1,5M €
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
24K €/sqm 80 % 80 %
Source: Istat e Engel & Völkers
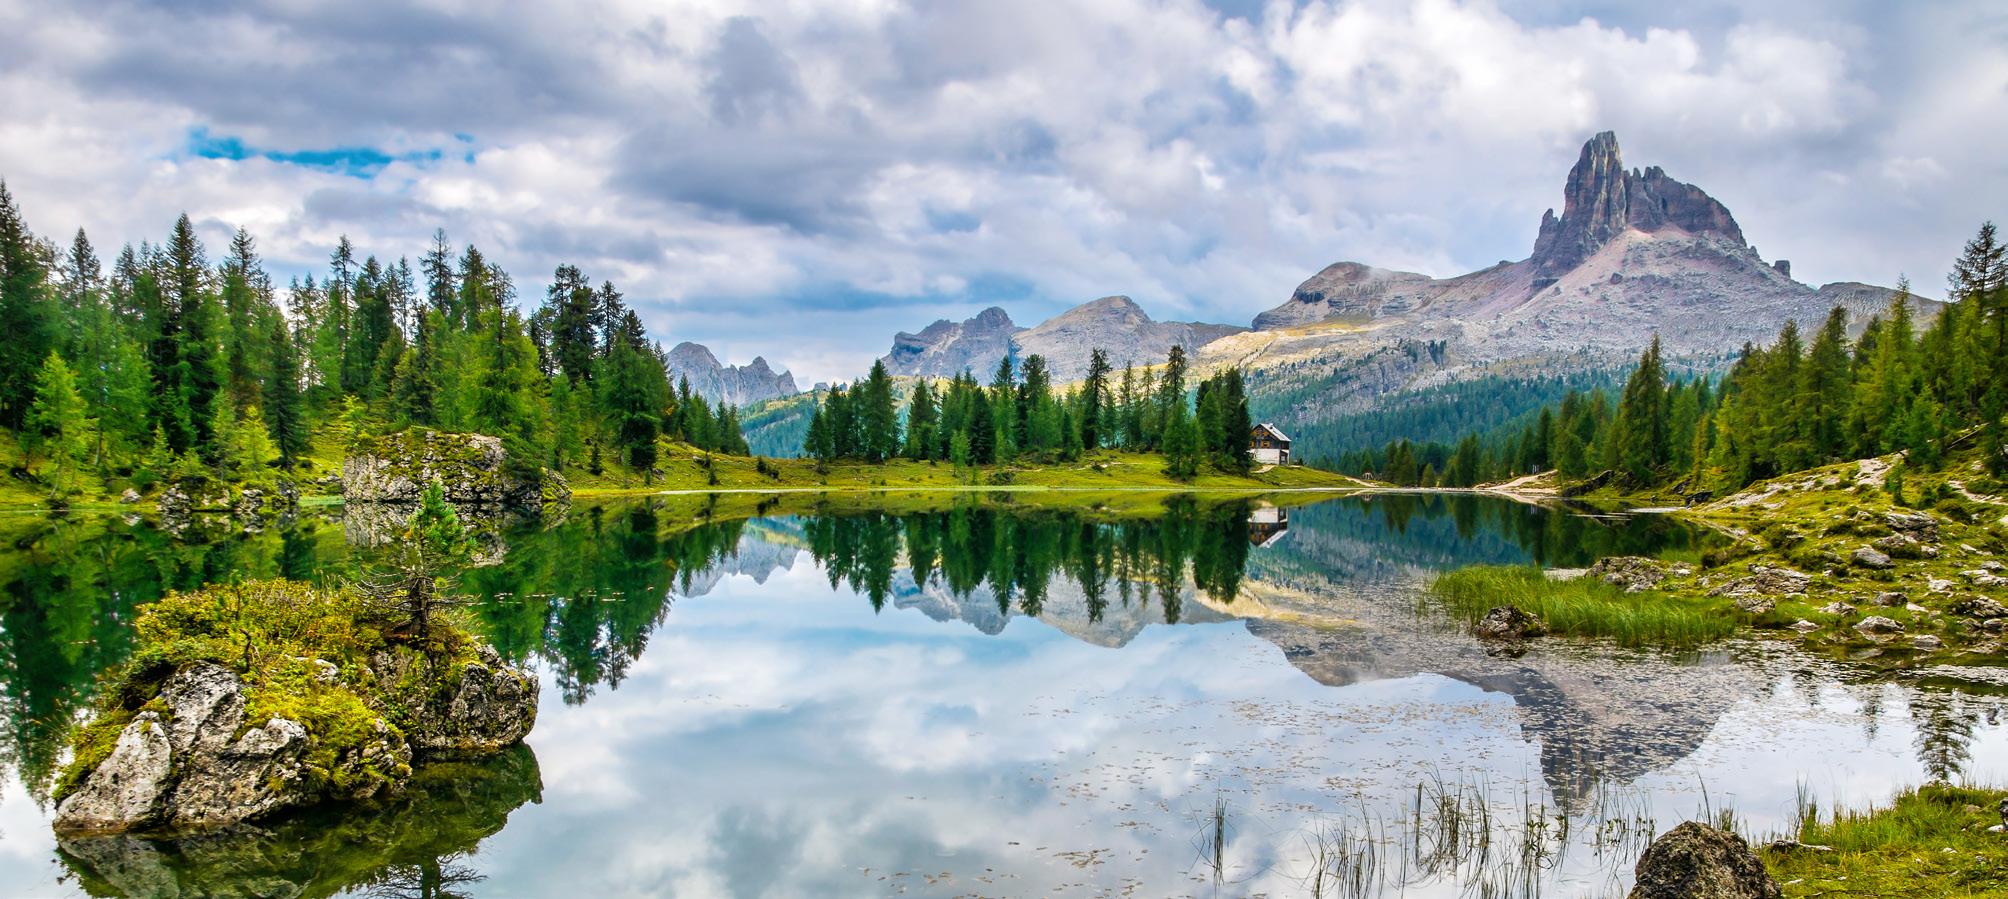
In Cortina d'Ampezzo, the market is dominated by traditional apartments and villas, with a strong preference for habitable second-hand properties. The sector focuses on the high-end segments: prime properties range between €15,000 and €20,000 per sqm and high-end ones range between €20,000 and €24,000 per sqm. With 5-10 transactions per year, the target remains 90% Italian (4554 years old), although foreign demand is increasing compared to the previous year. In 2025, the market recorded a moderate decline in all areas, with average sales times exceeding six months. Despite the slowdown, demand remains strong for properties with views, garages, and exclusive amenities, while supply is growing. This buyer profile, oriented both towards investment and the Alpine lifestyle, will drive the trend for the rest of 2026: growing demand is expected, which, concentrated in top-tier
properties, will push prices further upward, especially for prime properties and new, top-notch renovations.
Sales by type of investment
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
5-8K €/sqm +1/+3% 1,2-1,5M € 10K
Source: Istat e Engel & Völkers
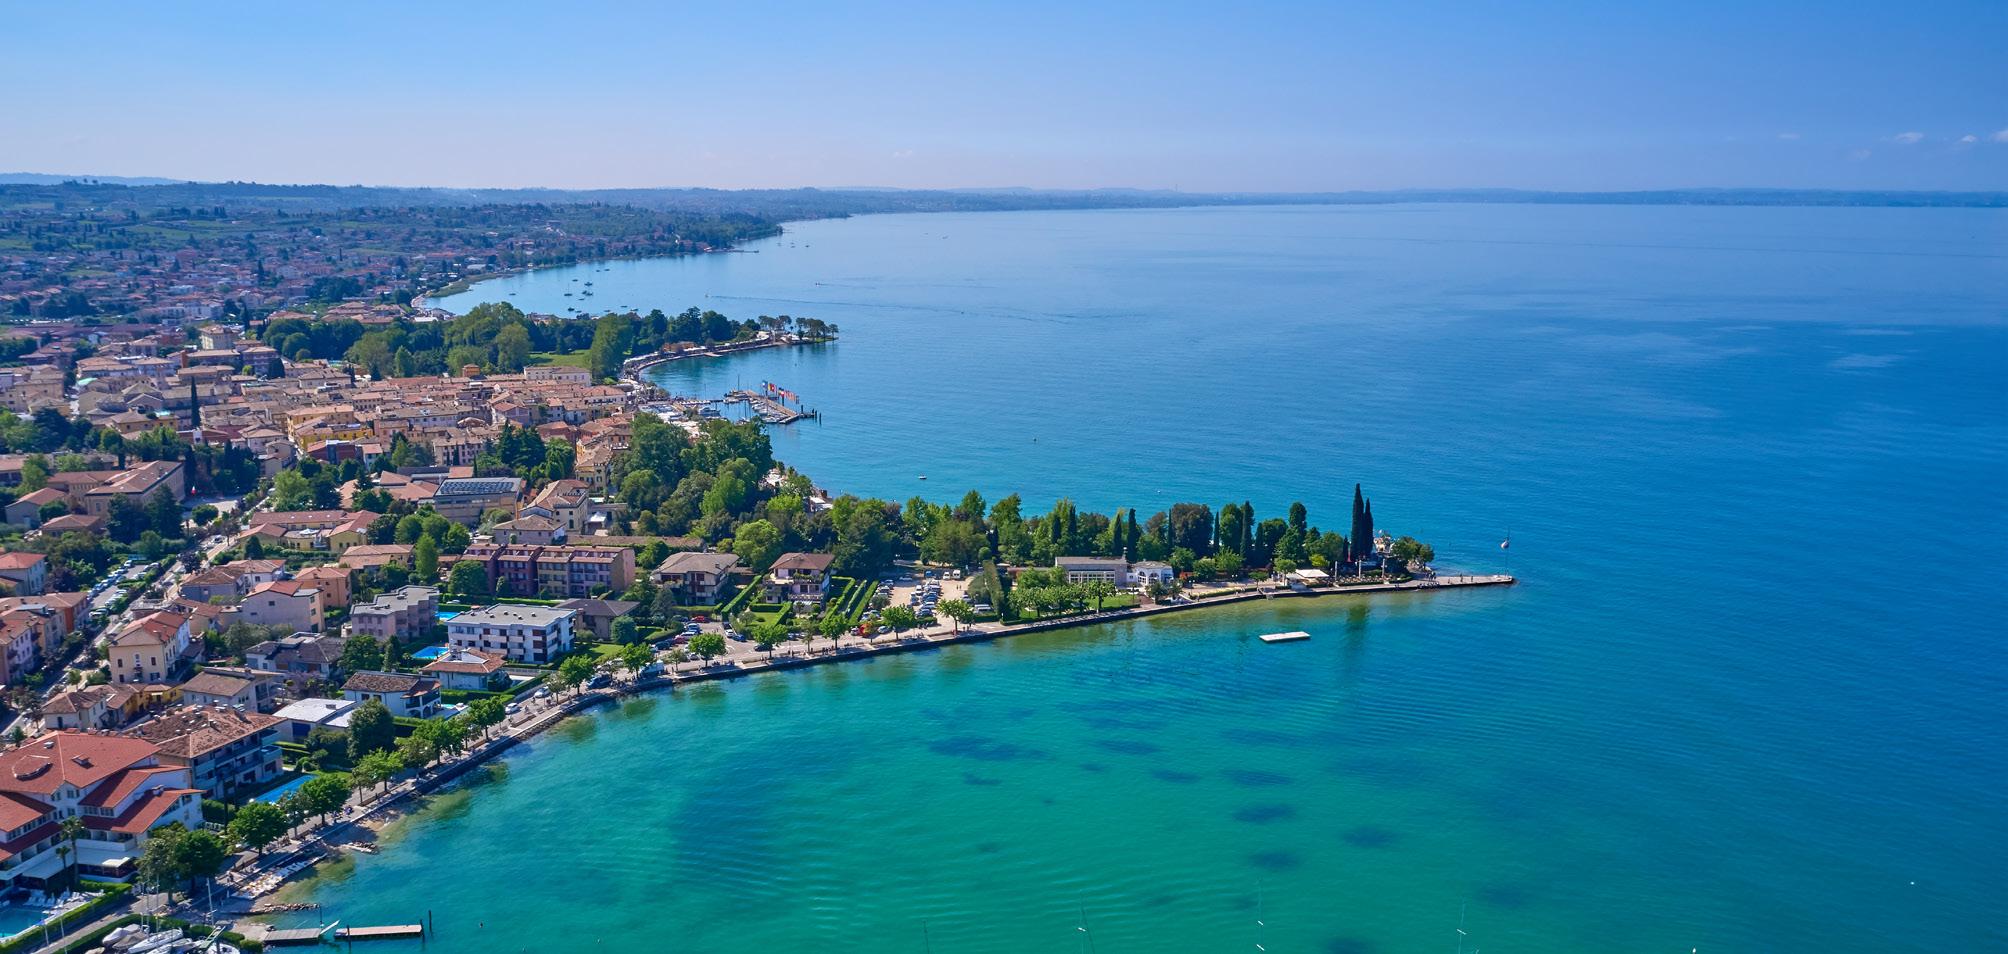
The Bardolino and Peschiera del Garda markets are showing moderate growth in demand, accompanied by an increase in supply. Price dynamics show substantial stability in the intermediate range and positive variations of between 1 and 3% in the prime segment and between 4% and 7% in the high-end segment. Second home purchases are the most common reason, while international buyers account for around 60% of overall demand. Interest is focused on new or fully renovated properties in prime locations. Sales times of more than 6 months indicate increasing selectivity among buyers and a greater focus on product quality and location. Among the most requested elements are outdoor spaces and high levels of energy efficiency. For 2026 H2, stable demand is expected in the intermediate segment and growth in the prime and highend segments.
Source: Engel & Völkers Italy
PURCHASES WITHOUT HOME LOAN
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
4,5-6K €/sqm +1 /+3%
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
7,5K €/sqm
Source: Istat e Engel & Völkers
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
45 %
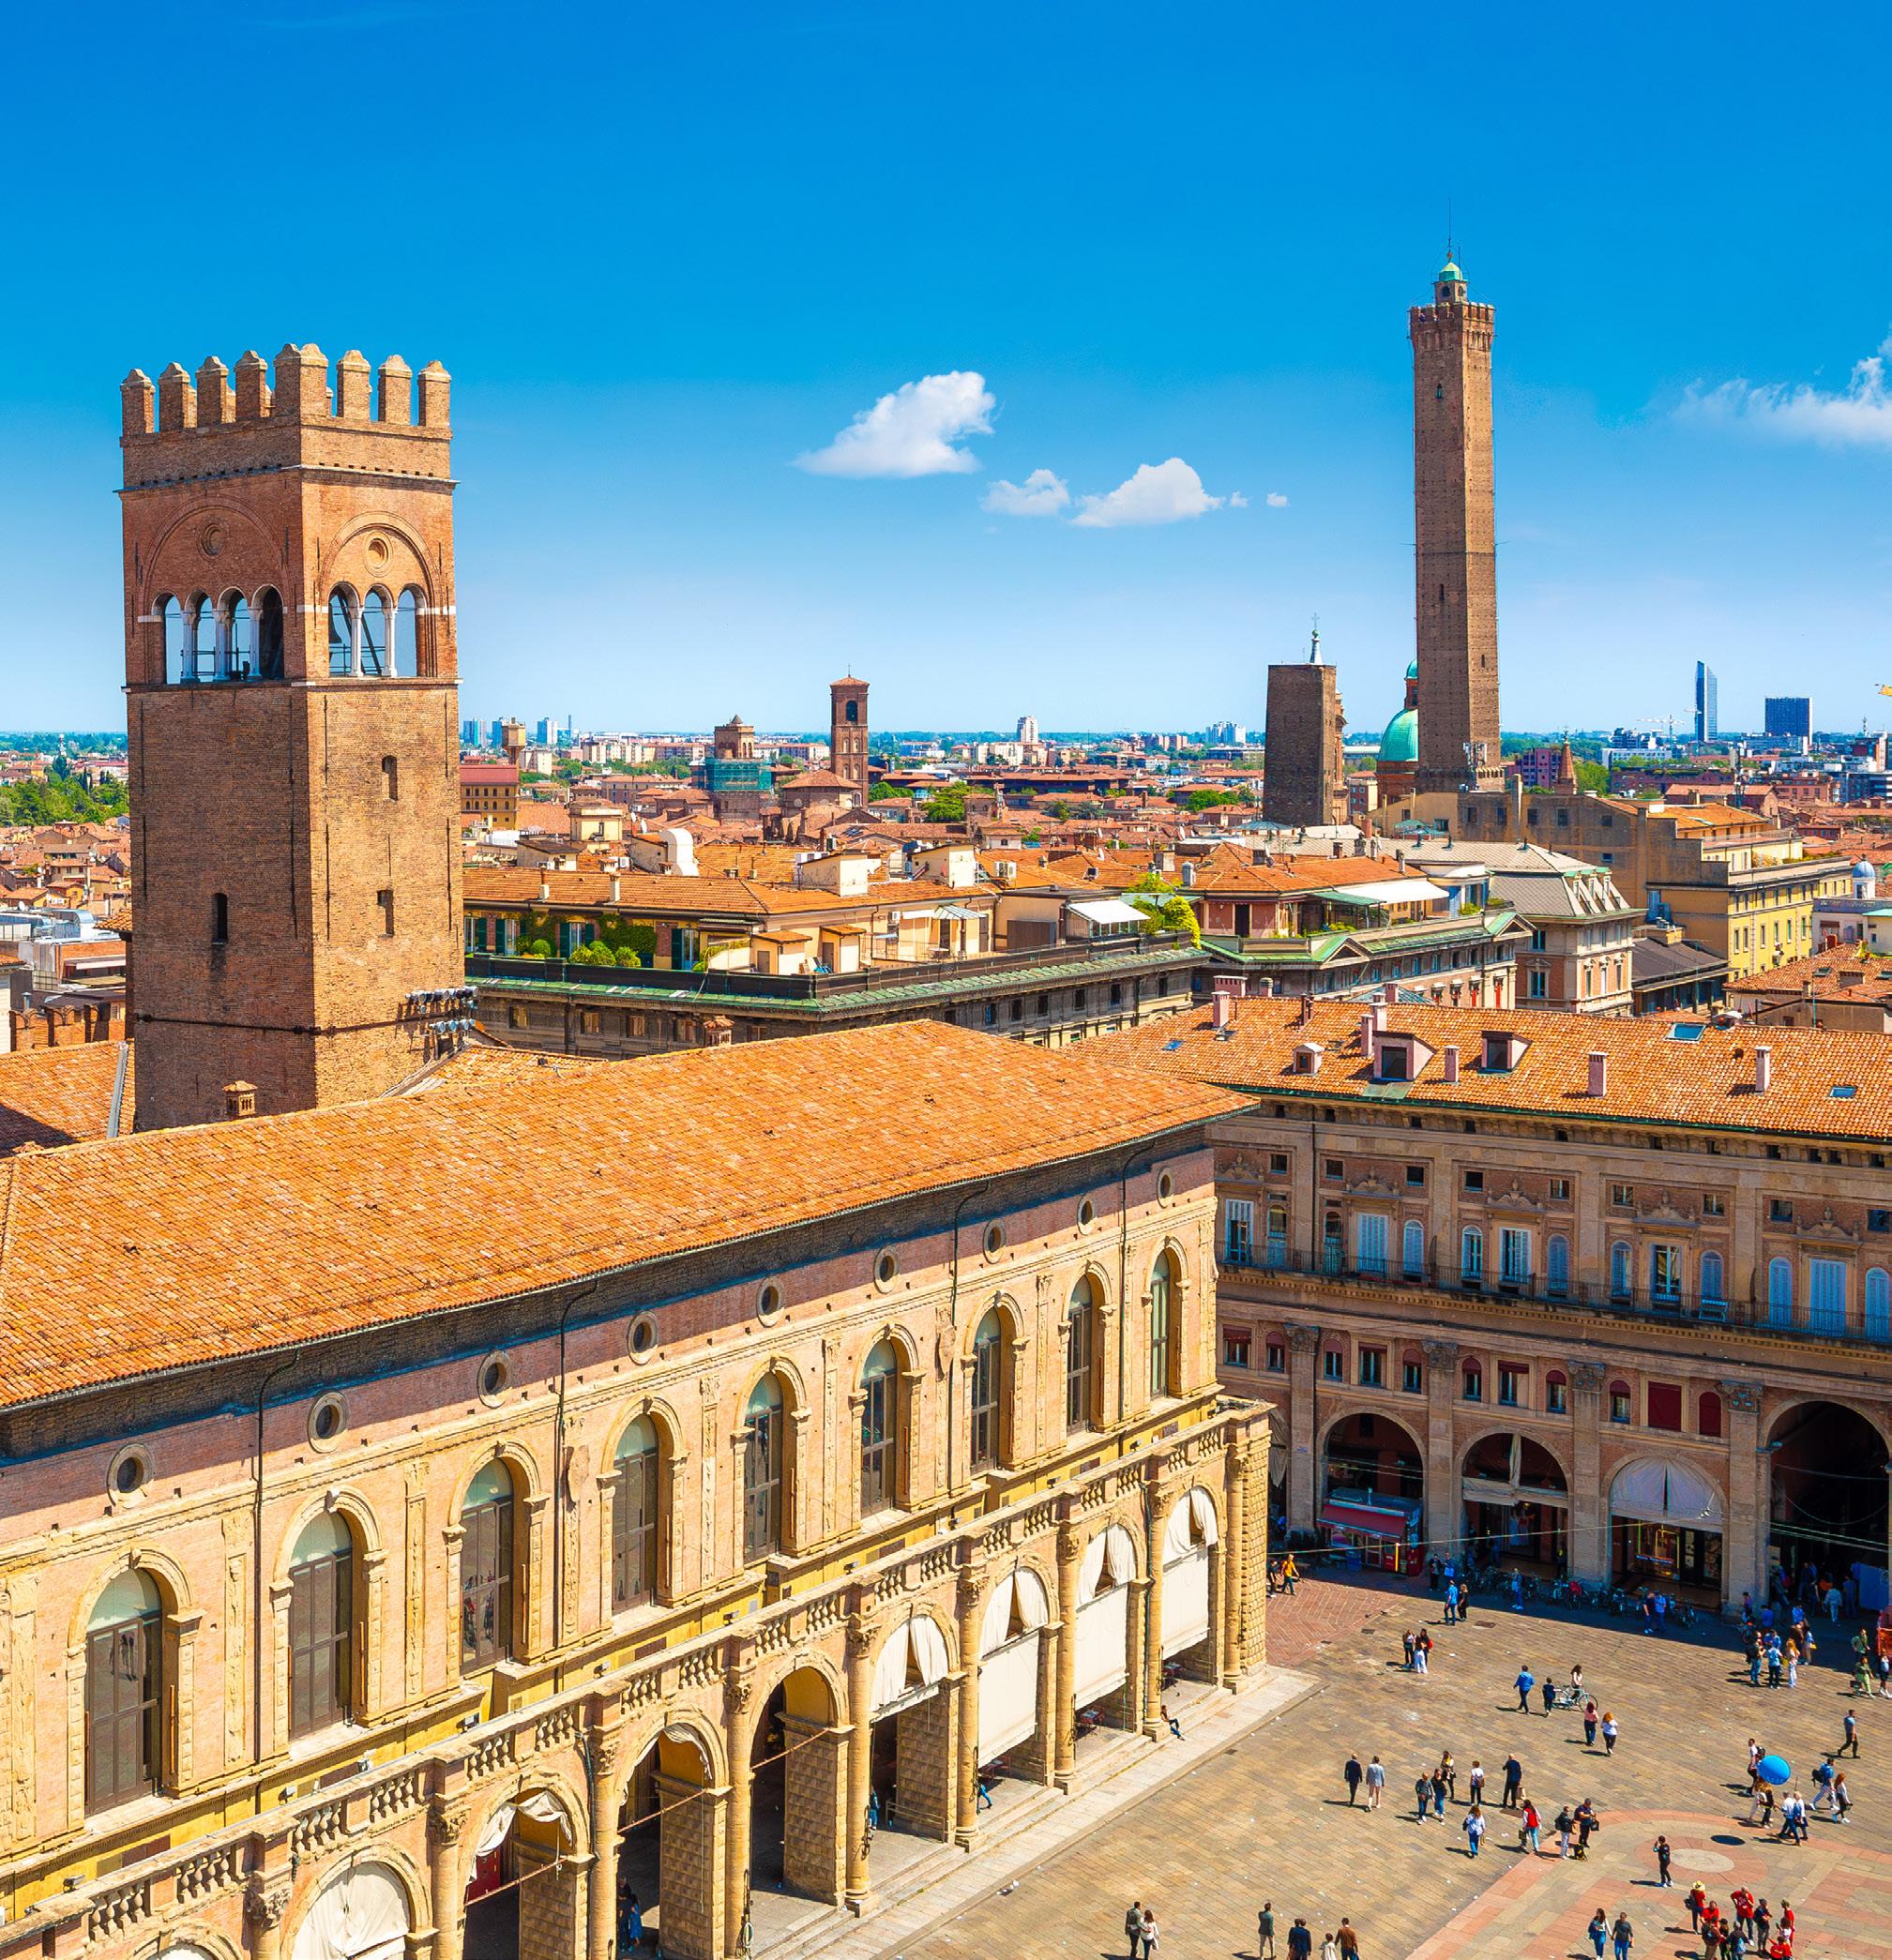
Bologna's residential market continues to perform well, supported by stable demand and rising values in the prime segment. Average prices range between €1,800 and €3,000 per sqm for the mid-range market, between €4,200 and €6,500 per sqm for prime properties, and between €4,600 and €7,000 per sqm for high-end properties. New or renovated homes in the city centre reach peaks of €7,500 per sqm. The modest but steady growth in prices (+1/+3%) is accompanied by rapid average sales times, from one to six months depending on the quality and location of the property. Demand is focused on high-quality apartments, penthouses, and villas, with a strong focus on terraces, gardens, views, and energy performance. Buyers are showing increasing financial rationality, with partial recourse to mortgages and a significant international component.
In 2025, the residential rental market in Bologna was characterized by a marked imbalance between supply and demand, with sustained rental pressure resulting in an
800K -1,2M €
PURCHASES WITHOUT HOME LOAN
%
annual increase in rents of around 5%. Demand was concentrated primarily in the historic centre and the neighbourhoods immediately outside the walls, such as San Mamolo, Murri, and Saragozza, appreciated for their proximity to the centre, the quality of the urban environment, and the good provision of services. Renovated and move-in ready properties are particularly sought after, preferably with outdoor spaces and located in well-connected residential areas. Given the limited availability of property, tenants' interest has gradually extended to less central or less well-served areas, provided they are accessible and convenient for urban travel. The outlook for 2026 H2 indicates stable demand in the intermediate segment and an increase in prime and highend, driven by demographic and infrastructural factors and the city's consolidated attractiveness, confirming Bologna as a structurally solid and competitive market. Leasing demand is expected to increase with values oriented towards moderate growth.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
3,5-4,2K €/sqm +1/+3% 500-800K € 4,5K €/sqm 85 % 60 %
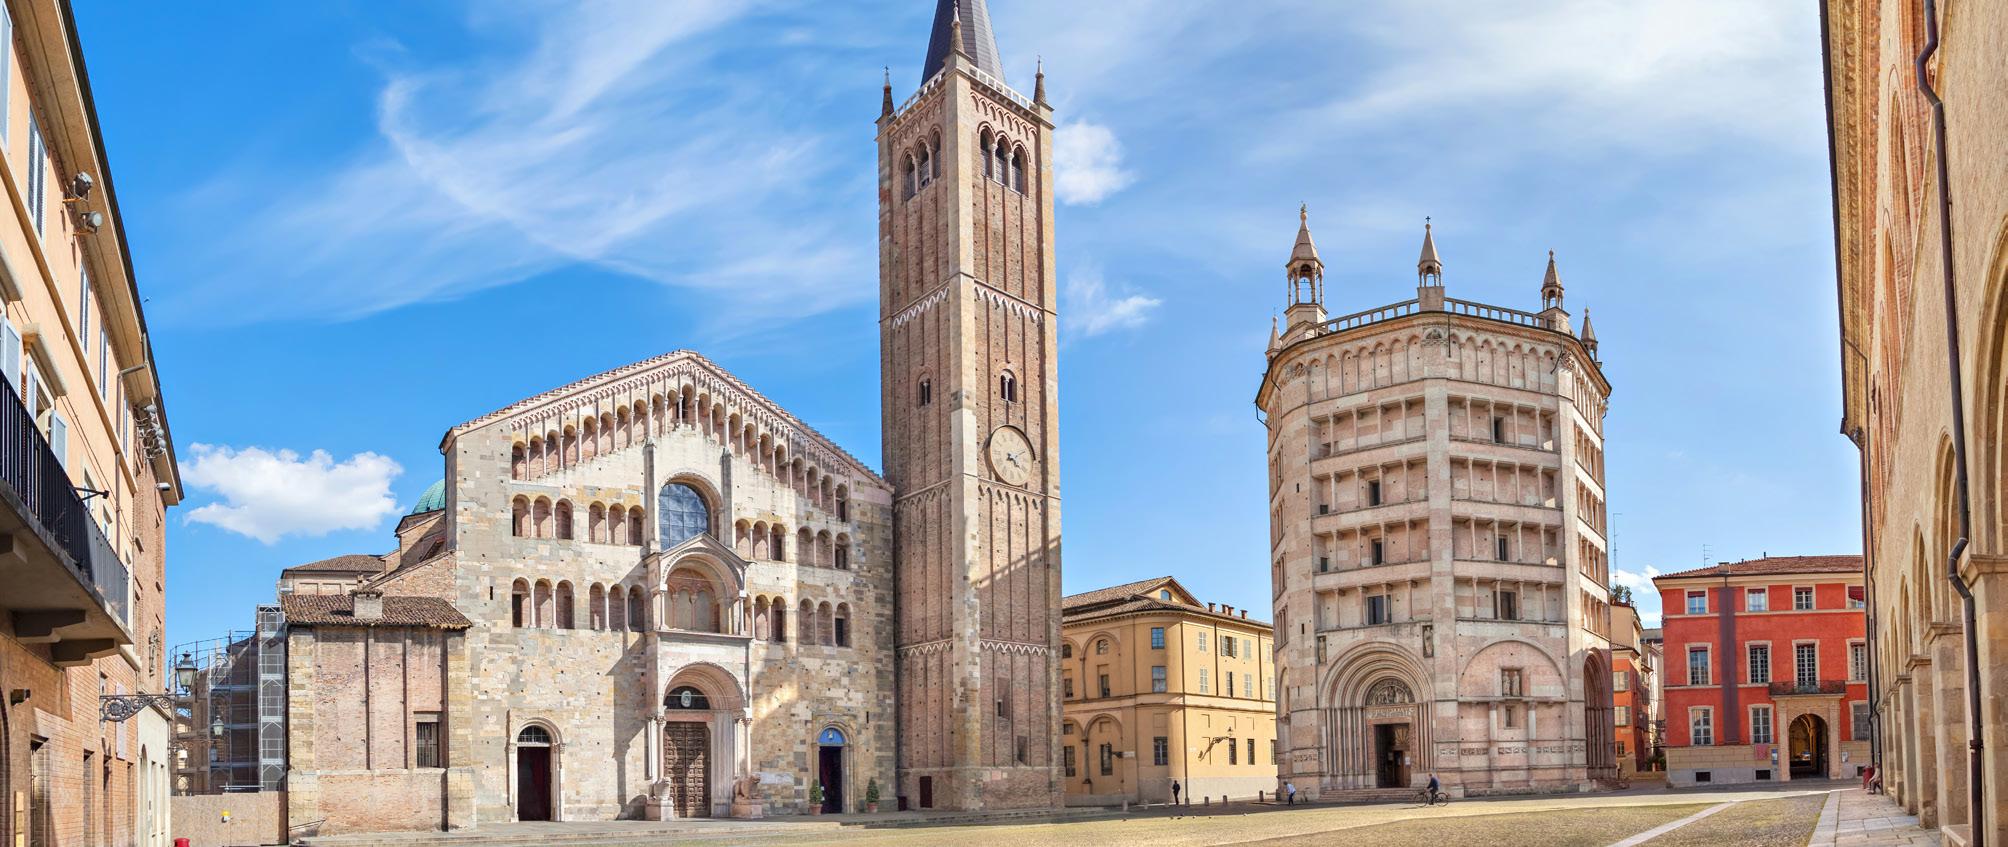
Parma's prime residential market is showing overall stable trends, supported by moderately growing demand while supply remains unchanged. Transactions are concentrated in the intermediate segment, which represents 55% of sales, while the prime sector maintains a significant weight (40%) with prices slightly increasing, in line with the growing interest in new or renovated properties with high energy ratings. Average prices show a marked gap between the city centre and the semi-centre: in the most sought-after areas, new homes range between €3,500 and €4,200 per sqm, with peaks of up to €4,500 per sqm. Demand is driven primarily by Italian buyers, mostly in the 35–44 age group, who are looking for city apartments with a balcony or terrace, garage, and energy-efficient features. Sales times vary significantly from area to area: from 1–3 months in the centre, up to over 6 months in the rest of the market. Demand is expected to grow slightly in 2026 H2, with
Sales by type of investment
2025 Data possible variations linked to interest rate trends and the international scenario.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
3,5-5,4K €/sqm +4/+7%
TOP PRICE
AVERAGE BUDGET IN PRIME SEGMENT
500-800K € 5,5K €/sqm 90 % 82 %
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
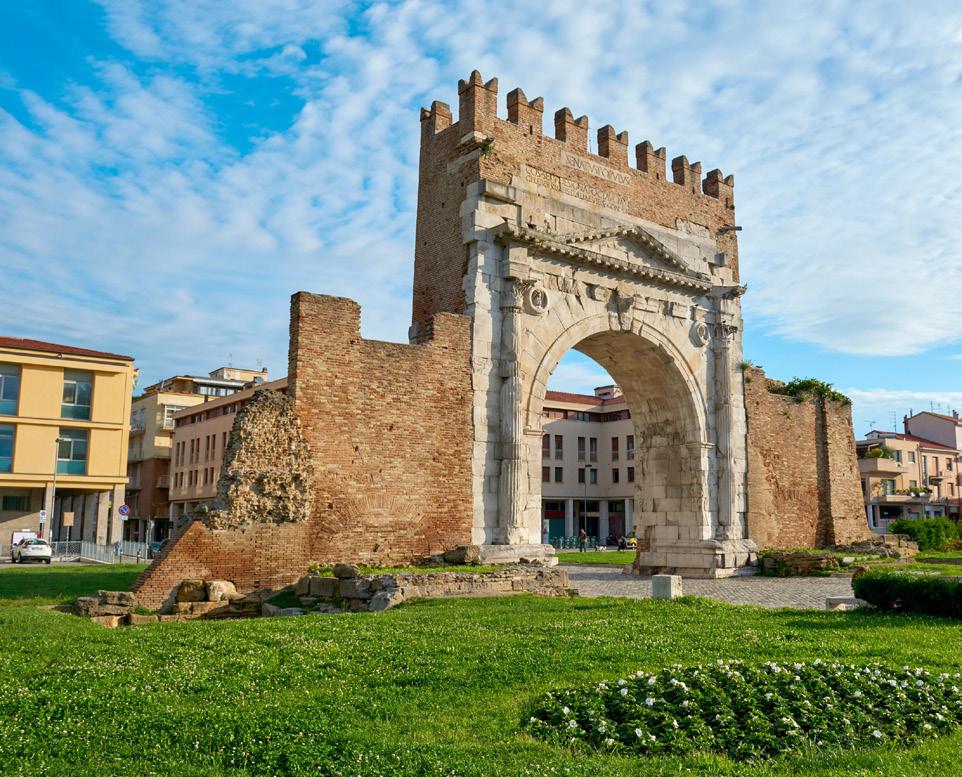
Rimini's residential market is expected to grow overall in 2025, with consolidating values especially in the central and seafront areas. Prices in the prime segment range from a minimum of €2,500 per sqm to a maximum of €3,000 per sqm, while high-end ranges from €4,200 to €5,500 per sqm. Average sales times are rapid in central areas, while in semi-central areas and the rest of the market they range between 3 and 6 months. The factors that have the greatest impact today are the quality of the properties and the quality of life offered by the area. The demand is mainly made up of first home replacements (40%) and second home purchases (35%). The most sought-after types are apartments, penthouses, and villas, with a preference for new or newly renovated properties. Must-haves include a terrace or balcony, parking space/garage, elevator, and silence/privacy. The buyers are 90% Italian and 10% international, and the prevailing age is 45–54. Stability is expected in the intermediate and prime segments for 2026 H2, with possible further growth in high-end. Factors that
could impact the scenario include the trend in interest rates, international stability, and regulatory/urban planning developments.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
5,5-7K €/sqm -1/0% 500-800K €
PURCHASES WITHOUT HOME LOAN
8K €/sqm
Source: Istat e Engel & Völkers
90 %
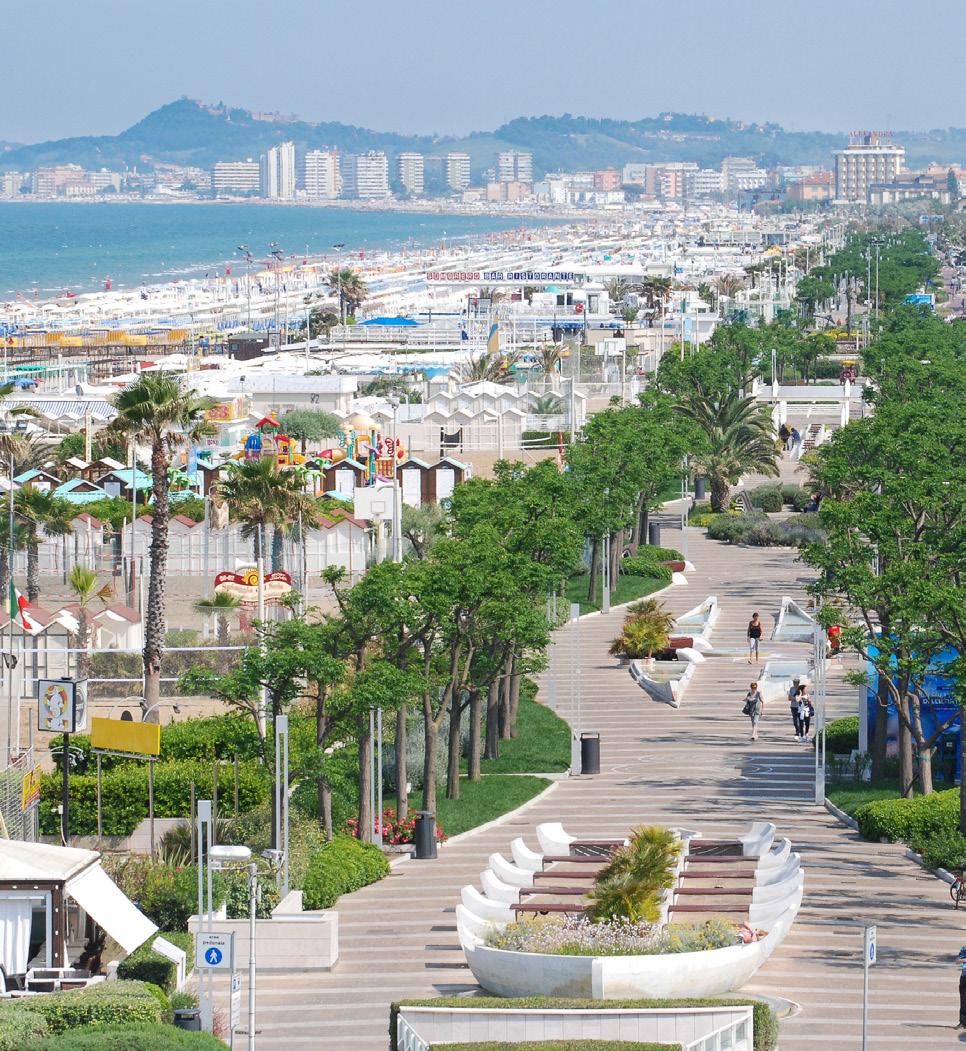
Riccione's prime residential market shows overall stable dynamics, with supply and demand balanced. Sales are concentrated in the prime segment, which represents 45% of the total, followed by the intermediate segment (35%) and high-end(20%). Prices are substantially unchanged compared to 2024 both for the prime segment, for which they are around 100%, and for the high-end segment. Demand is driven mainly by Italian buyers (80%), with a growing share of foreign buyers (20%), oriented above all towards quality second homes, penthouses, villas and new buildings with high energy efficiency, with terraces, panoramic views and privacy. Sales times remain short in the central areas (1–3 months) and extend to 3–6 months in the other areas. For 2026 H2, substantial stability in values is expected, with a possible strengthening of the prime segment depending on the fiscal and international scenario.
80 %
ENGEL & VÖLKERS MARKETS TOP PRICE 2025
10
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
INTERNATIONAL DEMAND (OVER PREVIOUS YEAR)
15,000 €/sqm 59%
INVESTMENT PURCHASES
15
PURCHASES WITHOUT HOME LOAN
67 %
Source: Istat e Engel & Völkers
The markets of Central Italy show an overall solid picture, supported by international demand and the growing pursuit of quality of life.
In Tuscany, rural and coastal areas are consolidating their attractiveness for second homes and tourism investments, with interest in renovated properties, outdoor spaces, and authentic settings. In the Tuscan Hills and Chianti, top prices are up to €15,000 per sqm, while in Siena they reach €13,000 per sqm, confirming the scarcity of quality products. The coast remains dynamic: Elba Island shows prices up to €10,000 per sqm, while Monte Argentario and Castiglione della Pescaia reach €7,000 per sqm for new or renovated units. In Florence, demand remains selective but resilient, with top prices at €10,000 per sqm, supported by the return of foreign buyers oriented towards modern comforts and central micro-locations. Pisa also shows widespread vibrancy, driven by accessibility and the
development of healthcare and university centres.
In Umbria, Orvieto and Todi are experiencing stability and growing international interest, with top prices up to €6,500 per sqm, rewarding quality and well-located properties.
In Lazio, Rome confirms a polarization between prime and secondary products, with top prices up to €12,000 per sqm, while Tuscia emerges as a moderately growing market thanks to authentic rural contexts and greater international visibility. Overall, common drivers are limited supply, real estate quality, and international demand, with prospects for stability or selective growth in 2026.
The outlook for the rest of 2026 indicates an overall stable scenario in the Central Italian markets, with selective growth dynamics concentrated in prime segments and locations with greater international appeal. Foreign demand will continue to support high-quality rural areas, cities of art, and coastal destinations, while the availability
Italian and foreign buyers
Source: Engel & Völkers Italy
of renovated and efficient properties will remain key. In urban markets, we expect fiercer pricing competition and increasingly informed and value-oriented demand. The main drivers include interest rate trends, the geopolitical context, and regulatory developments, which could impact absorption volumes and timing. Overall, we expect a consolidation of values in prime locations and greater selectivity in the rest of the market.
4,8-6,5K €/sqm +1 /+3%
EUROPEAN BUYERS OVER
800K-1,5M €
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Florence's residential market is showing an overall stable trend, with substantially balanced supply and demand and moderate growth in values. Prices range between €3,000 and €4,500 per sqm in the intermediate segment, between €5,000 and €7,000 per sqm in the prime segment, and between €7,500 and €10,000 per sqm in the high-end segment. For new or renovated homes in central areas, average prices range between €4,800 and €6,500 per sqm, with peaks of up to €10,000 per sqm for particularly sought-after units.
Over the course of the year, prices show modest increases, in the order of 1-3%, while the average sales time is between 3 and 6 months. Demand is primarily oriented towards newly renovated properties, with growing attention to outdoor spaces, high energy efficiency, and living comfort. An important role is played by the international component, which represents approximately 65% of buyers.
The rental sector is experiencing a decline in traditional contracts, both free market and rent-controlled, partly due to the reduction in available inventory and rising rent levels. At the same time, the short-term rental segment is strengthening, supported by the growing presence of specialized operators, especially in the historic centre. Demand for long-term rentals is primarily oriented towards renovated homes, with a progressive extension towards the neighbourhoods surrounding the centre, where there is greater availability of property. Overall, the number of contracts shows a decrease compared to the previous year, while rents show a widespread growth trend: for renovated homes, the average values are around €23 per sqm in the centre, €17 per sqm in the semi-centre and around €18 per sqm in the rest of the market.
The outlook for 2026 indicates stable purchasing demand in the intermediate segment and growing demand in the
Italian and foreign buyers
Source: Engel & Völkers Italy
prime and high-end segments. Leasing demand is expected to remain robust, while supply is expected to remain limited,
with further upward pressure on rents, especially in central areas and the first semi-central area.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
4,5-10K €/sqm +4/+7% >1,5M € 13K €/sqm 50 % 80 %
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Siena's prime market is experiencing moderately growing demand, while supply is progressively declining, and is positioned as a market specializing in quality products. The international component is predominant and represents approximately 70% of buyers, with an increasing weight in 2025 and mainly from non-European origins. Prices show a differentiated trend: the intermediate segment records a slight decrease, while the prime segment grows between +4% and +7%, with values between €3,000 and €5,000 per sqm. The high-end segment is even more dynamic, exceeding +10% and reaching €10,000 per sqm. Sales times remain short in the historic centre, between one and three months, while they lengthen in the peripheral areas. The most popular type of property is the farmhouse; demand favours properties with outdoor spaces, views, high energy efficiency, and quiet, private settings. The use of mortgages remains limited, around 20%, while the speed of negotiations in the high-end segments confirms a market supported by buyers with high liquidity.
Italian and foreign buyers
Source: Engel & Völkers Italy
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
Source: Istat e Engel & Völkers
The real estate market is experiencing moderate growth in demand while supply is declining, with the prime segment dominating, recording an average annual increase in values of between 4% and 7%. Prices for new and renovated homes in the most sought-after areas range between €5,000 and €10,000 per sqm, with peaks of up to €15,000 per sqm; in the semi-central area, prices range between €3,000 and €5,500 per sqm. International demand is significant, accounting for 80% of the total, and increasing, while Italian demand remains stable. The main reasons for purchasing a property are second homes; in central areas, sales times range from 1 to 3 months. The research focuses on villas and farmhouses with gardens with high energy efficiency. Buyers are increasingly attracted to rural areas, far from pollutants and stressful lifestyles. For 2026 H2, growth in demand is expected in the prime and high-end
segments, supported by the foreign component and strong interest in prime rural contexts. NEW/RENOVATED, 2026 PRIME PRICE
Italian and foreign buyers
Source: Engel & Völkers
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3,8-7K €/sqm +4/+7% 500K-1,2M € 10K €/sqm 75 % 90 %
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The residential market on the Island of Elba and the Etruscan Coast continues to expand, with rapidly growing demand and substantially stable supply. Sales are distributed as follows: 40% in the intermediate, 30% in the prime and 30% in the high-end segment. The market is showing an increase in the central areas, stability in the semi-central areas and a slight decline in the rest of the territory. Prices for prime areas range between €3,000 and €4,500 per sqm, while high-end areas range between €4,500 and €6,000 per sqm. Average sales times range between 1 and 3 months in prime areas, 3-6 months in the semi-central area, and over 6 months in the rest of the market. Demand is driven primarily by Italian buyers (60%), with a limited foreign component (40%), almost exclusively European. The most sought-after types are apartments, villas, and farmhouses, with strong interest in new constructions or renovated properties. The most soughtafter features are a terrace or balcony, garden, view, and
Sales by type of investment
2025 Data parking space. Further growth is expected in the intermediate and prime segments in 2026 H2, with stability in the high-end segment.
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
3,5-6K €/sqm +1/+3% 500K-1,2M € 7K €/sqm 80 % 80 %
Source: Istat e Engel & Völkers
The Monte Argentario and Castiglione della Pescaia market is dominated by the prime segment (70%), in a context characterized by moderately growing demand and increasing supply. As for new or renovated homes, the trend in 2025 remained stable in all areas, from the centre to the peripheral areas. Average sales times vary from 1 to 3 months in top-tier areas to 3-6 months in other areas, with prices between €2,700 and €6,000 per sqm for prime properties and €5,000 and €7,000 per sqm for high-end ones. With around 10-20 transactions annually, the market is driven by second home purchases (50%), followed by first homes (30%), investments (10%), and first home replacements (10%) and is supported by stable Italian demand and an increasing foreign component compared to last year. The focus is on habitable used properties, with must-haves such as a terrace, garden, view, and high energy efficiency. For the rest of 2026, growth is expected to focus
Italian and foreign buyers
Source: Engel & Völkers Italy
on areas with strong tourist appeal, ensuring price resilience in the prime segment.
Source: Istat e Engel & Völkers 3,5-4,5K
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
PURCHASES WITHOUT HOME LOAN
The Viareggio and Massarosa markets are stable, with continued strong demand, especially for well-maintained, strategically located, habitable used properties. Properties near the sea and with outdoor spaces continue to be the most sought-after, while less desirable properties struggle to maintain value. Prices for renovated homes in the most sought-after areas range between €3,500 and €4,500 per sqm, with peaks of up to €6,500 per sqm for top-end properties. Demand is primarily composed of foreign buyers, while the Italian component shows a more selective attitude, influenced by stable interest rates and the search for quality housing. Almost all transactions are concentrated in the prime segment, which accounts for 80% of sales and, along with the high-end segment, is seeing a slight increase in prices. Second homes represent the main reason for transactions, with a preference for penthouses, villas and farmhouses. Sales lead times range from 1–3 months in the centre and up to over 6 months in the peripheral areas.
Italian and foreign buyers
Source: Engel & Völkers Italy NEW/RENOVATED,
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
3,2-5,5K €/sqm +1/+3%
TOP PRICE
AVERAGE BUDGET IN PRIME SEGMENT
500-800K € 7K €/sqm 70 % 30 %
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Pisa's prime residential market continues its moderate growth trajectory, with prices recording a uniform positive variation (+1-3%) across all segments, a sign of a market that is advancing gradually. The intermediate segment represents the dominant share of sales (75%), with prices between €1,200 and €1,800 per sqm, while the prime segment — which covers the remaining 25% — is between €1,600 and €2,500 per sqm. Demand is mainly oriented towards first homes (50%) and replacements (25%), with 70% of buyers having recourse to mortgages. There's growing interest in properties in peripheral and semi-urban areas, which are more accessible than the city centre and meet space constraints. The consolidation of the university district and the attractiveness of the coastline—popular not just as a vacation destination but as a permanent residence—are fuelling a steady flow of new buyers. Foreign demand, although a minority at 25%, is increasing and comes largely from Europe, with a North American
share of between 11% and 20%. Interest is focused on apartments, villas and farmhouses, with a preference for habitable used products.
Sales by type of investment
2025 Data
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
2,5-3,5K
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The Orvieto and Todi market is showing a stable trend, with supply and demand in balance and prices virtually unchanged in the medium-low and prime segments, while the high-end segment is recording slight growth (+1-3%). The prime segment dominates sales (65%), with values between €1,500 and €2,500 per sqm, while the high-end segment rises up to €5,000 per sqm, with peaks of €6,500 per sqm for the most exclusive properties. Demand is strongly oriented towards second homes (70%), with a foreign component representing 80% of buyers, mainly of European origin. Sales times are extended, exceeding six months in central and peripheral areas. The most soughtafter types are apartments, villas, and farmhouses; essential requirements include a garden/outdoor space, a view, a high energy rating, and peace and quiet/privacy. The Orvieto and Todi area remains a sought-after market, with
international demand for properties that combine quality living, scenic beauty, and privacy.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3,2-5,5K €/sqm +1/+3% 500-800K € 6K €/sqm 60 %
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
65 %
Source: Istat e Engel & Völkers
The Tuscia market is experiencing increasing demand in the face of growing supply, with prices showing diverging trends by segment: the intermediate segment has seen an estimated contraction of around -5%, while the prime and high-end segments have seen a positive change in the order of 1-3%. The prime segment ranges between €3,200 and €5,500 per sqm, while high-end prices range between €5,800 and €6,100 per sqm. The market is structurally oriented towards the intermediate segment, which absorbs all sales, with a predominantly residential purpose. Foreign demand, mainly from Europe, is growing and represents 50% of buyers. Demand is concentrated on villas, farmhouses and apartments. Sales times in the central areas are quick (less than a month), while they are longer in the rest of the market. For 2026 H2, the forecast indicates growth in the prime segment, supported by steadily increasing international visibility and an evolving buyer profile, increasingly attracted by rural settings, quality of life, and medium- to long-term investment opportunities.
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Rome's prime market has shown moderate growth in demand, while supply has remained substantially stable. Prices range between €1,900 and €3,800 per sqm in the intermediate segment, between €3,000 and €6,000 per sqm in the prime segment, and between €8,000 and €12,000 per sqm in the high-end segment. Prices showed limited variations in the intermediate market segments and in the prime segment (+1/+3%), while high-end showed more sustained increases (+4/+7%). Average sales times range from 1 to 6 months depending on the location and quality of the product. Demand is primarily geared toward newly renovated properties, with a strong focus on terraces, energy efficiency, and parking availability. The international component, equal to approximately 20% of buyers, is growing and is mainly concentrated on quality properties in central areas.
The rental market has shown a lively trend, supported by stable demand and a progressive increase in supply, also thanks to the return to the residential sector of part of the
stock previously destined for tourist rentals. Demand was mainly focused on renovated and well-equipped properties, with particular interest in central and semi-central areas such as Prati, Trieste-Salario, and Ostiense. At the same time, there is growing dynamism in areas undergoing urban and infrastructural redevelopment, often supported by public investment programs, which are strengthening the attractiveness of well-connected, semi-central neighbourhoods with still competitive values. Part of the demand is also oriented towards university areas, also for investment purposes. In 2025, fees for renovated homes averaged around €350/sqm/year in central areas and €230/sqm/year in semi-central areas.
The outlook for 2026 H2 indicates stable purchasing demand in the less valuable segments of the market and increasing in the prime and high-end ranges. The leasing demand may grow in some areas, but tightening regulations on short-term rentals could further rebalance supply in the traditional residential market.
Italian and foreign buyers
Source: Engel & Völkers Italy
ENGEL & VÖLKERS MARKETS TOP PRICE 2025
25
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
67%
Source: Istat e Engel & Völkers
INVESTMENT PURCHASES
24 %
The prime real estate market in the South and the Islands presents a heterogeneous but overall resilient picture, supported by international tourist appeal, a high quality of life, and prices that remain competitive compared to other European destinations.
Prime locations and top-tier islands are experiencing selective demand and limited supply, while urban and secondary markets are growing thanks to urban redevelopment, infrastructure, and new purchasing motivations related to relocation and tourism investment.
In Campania , Capri and the Sorrento Peninsula represent an absolute point of reference for the prime real estate market. The island of Capri maintains top prices of up to €14,000 per sqm for villas and penthouses with sea views, privacy, and luxury finishes. In Anacapri, prices are slightly
47,000 €/sqm
PURCHASES WITHOUT HOME LOAN
68 %
lower, but the offering still allows for the purchase of exclusive properties with driveway access. The island's lifestyle, characterized by historic residences and high-end B&B opportunities, continues to attract international buyers seeking quality of life, tranquillity, and unique environments. On the Amalfi Coast, Amalfi and Capri consolidate their status as top destinations, with prices up to €10,000 per sqm. Market dynamics highlight a limited supply compared to a steady demand from international buyers, ready to invest in turnkey or renovated properties, enhancing the area's historical and landscape heritage.
In Puglia, Bari and Salento confirm their charm as centres of prime residences. In Bari's historic centre and waterfront areas, top prices reach €5,000 per sqm, attracting investors seeking properties with high tourist revenue and
architectural quality. Salento, with its historic farmhouses, palaces, and villas nestled in the countryside or along the coast, offers prices up to €5,000 per sqm. The area is captivating with its Mediterranean lifestyle, characterised by tranquillity, privacy, and authentic tradition, attracting especially foreign buyers who see their purchase not just as a holiday home, but as a true-life project. Market dynamics are supported by growing international demand and attention to the overall quality of housing.
In Sicily, Taormina, the Ionian Coast and the Aeolian Islands remain prime destinations for those seeking high-end properties with strong international appeal. In Taormina, top prices reach €9,000 per sqm for villas with panoramic views, large outdoor spaces, and high-quality finishes. The
Source: Engel & Völkers
Catania and Messina area is also seeing a growing market, with top prices of up to €7,000 per sqm and €5,000 per sqm respectively, thanks to urban redevelopment projects and a demand increasingly oriented towards tourism investments or second homes. The Aeolian Islands and the Tyrrhenian Coast attract international buyers for their combination of extraordinary natural settings, privacy, and turnkey villas, with top prices up to €8,000 per sqm. Here, the lifestyle is shaped by the sea, local culture, and the opportunity to live in unique settings, often far from mass tourism.
In Sardinia, Porto Cervo and the Costa Smeralda continue to represent the excellence of the Italian prime real estate market. Villas, penthouses, and beachfront properties reach top prices of up to €35,000 per sqm, confirming their strong international appeal.
The island combines scenic beauty, exclusive services, and privacy, creating a lifestyle centred on discreet luxury, outdoor experiences, and highly selective international networking. Market dynamics show sustained demand from foreign buyers seeking exclusive residences, with interest in ready-to-move properties with distinctive features, such as sea views, gardens, and panoramic terraces.
The outlook for the rest of 2026 sees stable sales volumes with selective growth in the prime and high-end segments. The key drivers of the market are foreign demand, taxation, and the regulation of short-term rentals. The scarcity of quality products will continue to support values in prime locations, while in secondary markets, correct pricing remains crucial to the sector's dynamism.
Source: Istat e Engel & Völkers 1,8-2,6K
EUROPEAN BUYERS OVER
L'Aquila's residential market is experiencing strong growth in demand, accompanied by an increase in supply. The prices for the intermediate segment range between €700 and €1,500 per sqm; between €1,900 and €2,700 per sqm for the prime segment and between €3,000 and €4,000 per sqm for the high-end one. The distribution of sales shows a prevalence of the prime segment (50%), followed by the intermediate segment (40%) and the high-end segment (10%). Sales times range between 1 and 3 months in the central and semi-central areas, exceeding 6 months in the rest of the market. Demand is made up of 80% Italian buyers and 20% international buyers. Among the latter, Europe prevails (51-60%), followed by North America (1120%), with marginal shares from other areas. 35% resort to a mortgage, while 65% purchase with cash. The market is driven mainly by investment (35%) and first homes (30%), followed by second homes (20%) and first home replacements (15%). The most requested types are
AVERAGE BUDGET IN
PURCHASES WITHOUT HOME LOAN
penthouses, villas and new buildings. The most soughtafter must-haves: terrace or balcony, outdoor spaces, parking space or garage, elevator, and high energy rating. The main critical issues concern off-market prices, urban planning/cadastral compliance, and sellers' expectations. Growth is expected across all segments for 2026 H2. The factors that could have the greatest impact are fiscal policies, new infrastructure and media trends. The main driver remains the visibility linked to its role as Italian Capital of Culture 2026, which is strengthening the historic centre's attractiveness, encouraging the return of residents and growing interest from foreign buyers.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
VARIAZIONE PREZZI NEL SEGMENTO DI PREGIO (Y-O-Y %) +4 /+7%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
500K-1,2M € 10K €/sqm
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
Naples's prime market has shown marked resilience in 2025, with demand shifting toward the higher end of the market. For new or newly renovated properties in central areas, average prices reach €7,500 per sqm, with top prices of up to €10,000 per sqm reflecting the scarcity of exclusive assets in historic or scenic settings. Demand, which is growing moderately, is driven by 85% domestic demand and 15% international investors, mainly from EU and EFTA countries. The typical buyer profile, with a prevalent age between 45 and 54, orients its preferences towards large apartments, penthouses and villas, where the presence of habitable outdoor spaces, prestigious views and car access constitute essential decision-making drivers. Despite the use of bank financing, which affects approximately 95% of the operations, the market shows a friction linked to the limited quality of the available stock and to price requests, which are often not aligned with current market conditions.
There has also been an increase in interest in used but already habitable properties, particularly in central and semi-central areas well served by transport, while in secondary areas there is greater price sensitivity and longer decision-making times. Overall supply remains stable, but with increasing competition between similar properties, strengthening the negotiating power of the most qualified buyers. For 2026, an overall stable scenario is expected in the high-end segments, with demand slightly growing but volumes affected by regulatory developments, local urban planning dynamics, and the international macroeconomic context. Naples thus confirms its solid positioning as a prime urban market, capable of attracting both families looking to replace their first home and longterm investors.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
9-10K €/sqm +1/+3% 800K-1,2M €
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
12K €/sqm 50 % 70 %
Source: Istat e Engel & Völkers
Capri's prime market has shown overall stable trends, despite a moderate decline in demand and a decreasing supply. Prices showed a slight increase in all segments, most marked in the high-end segment, where the increase is estimated to reach 4–7%. New or renovated properties in central areas reach prices of up to €10,000 per sqm, with a peak price of €12,000 per sqm. Sales lead times are generally long, exceeding six months in most areas. The clientèle is made up of 60% Italian buyers, while the foreign one still presents a significant composition: in addition to the European prevalence, a significant share of North American buyers emerges (41–50% of foreign buyers). Demand is mainly focused on habitable used properties, with terraces, gardens, and views being the main musthaves. Interest rates, purchasing power, and foreign demand are the main factors that influence the market. For 2026, the outlook is for stability in all segments.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
5-10K €/sqm -1/0%
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
800K-1,2M €
PURCHASES WITHOUT HOME LOAN
12K €/sqm 45 % 75 %
Source: Istat e Engel & Völkers
The Amalfi Coast's prime market is characterized by stable trends and a supply structure clearly oriented upwards, with prime and high-end properties together accounting for 90% of sales concluded in 2025. The prime segment is between €4,000 and €6,000 per sqm, while the high-end segment is between €5,000 and €10,000 per sqm, with peak transactions above €12,000 per sqm for particularly important properties. The foreign component of buyers is equal to 40% of the total and is increasing compared to the previous year. Mortgage rates remain at 25%, confirming the high spending power of the clientèle. The most soughtafter types are apartments, villas, and farmhouses, with a strong preference for properties with a terrace or outdoor space, a view, an adequate energy rating, and quiet. For 2026 H2, demand is expected to grow in the prime segment, while high-end and intermediate segments remain stable.
Sales by type of investment
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
5-8K €/sqm +1/0% 800K-1,2M €
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The Sorrento Peninsula real estate market is characterized by a predominance of international buyers, who represent approximately 70% of demand, mainly from North America and Europe. In 2025, Italian demand remained stable, while the foreign component grew, while supply remained substantially unchanged. During 2025, transaction activity focused primarily on the prime segment, which accounted for 70% of sales, while the high-end sector covered approximately 20% of the total. New or renovated homes remain the most sought-after product: in the centre, prices ranged between €5,000 and €8,000 per sqm, with peaks of up to €9,000 per sqm, while in the semi-centre they fluctuated between €4,000 and €6,000 per sqm. Demand remained particularly strong for villas, with average sales times between 3 and 6 months. For 2026 H2, substantial stability is expected in the intermediate and high-end segments, and growth in the prime sector.
Sales by type of investment
2025 Data
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
2-3,4K €/sqm -1/0% 500-800K €
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS PURCHASES WITHOUT HOME LOAN
3,7K €/sqm 65 % 67 %
Source: Istat e Engel & Völkers
In Ischia and Procida, the market is dominated by the prime segment (80%), while high-end and mid-range properties each account for 10% of the total, with a clear preference for habitable used properties. In the prime segment , prices fluctuate between €2,300 and €3,500 per sqm. With a maximum of 5 transactions per year, the market maintains stable volumes and supply compared to the previous year, although the average sales time remains above 6 months. The target audience is 70% Italian; foreign demand is mainly from Europe and, to a lesser extent, North America. The search focuses on apartments, villas, and farmhouses with a terrace or balcony, garden, panoramic view, and parking space or garage. In 2026, the market will reflect the islands' diverse identities: while Ischia focuses on resilience and a diverse offering, Procida will consolidate its position as an exclusive lifestyle destination for a specific niche. In this scenario, correct pricing and full urban planning compliance accelerate the sales process.
3,5-4,5K €/sqm +10%
500-800K €
PURCHASES
4,5K €/sqm
Source: Istat e Engel & Völkers
Bari's prime market has shown moderate growth in demand amidst a contraction in supply, a trend that is driving rising values, especially in the prime segment, which accounts for about 90% of monitored sales. In the city centre, prices show significant increases, with the prime segment recording estimated variations of more than 10%, while the intermediate segment shows increases of between +4% and +7%. Demand shows a marked preference for purchasing apartments and penthouses with a terrace or balcony, considered key elements for enhancing the investment.
The customer base is substantially balanced, with a slight prevalence of the international component (51%), driven in particular by European buyers interested in investment opportunities and second homes. In terms of motivation, the most prevalent reasons are purchasing as a first home (more than 50%) and as an investment (about 20%).
Sales times range between 3 and 6 months in central and
semi-central areas, exceeding 6 months in the more peripheral areas, where greater stock availability affects absorption times.
There is also a growing interest in used but already habitable properties, which allow for quicker entry into the shortterm or tourist rental market. New infrastructure and urban redevelopment projects are helping to redesign the attractiveness of some neighbourhoods, expanding the scope of areas considered to be of interest for the mediumhigh segment.
For 2026 H2, demand is expected to remain stable in the mid-range segment and to grow further in the prime and high-end segments, in a context primarily influenced by interest rate trends, credit access conditions, and local regulatory developments. Bari thus consolidates its transformation into a residential and tourist hub for Southern Italy.
Italian and foreign buyers
Source: Engel & Völkers Italy
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
TOP PRICE
Source: Istat e Engel & Völkers
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
The Itria Valley prime market operates in a lively but increasingly selective environment. Demand is growing, largely driven by international buyers, while supply is shrinking, especially for properties renovated to highquality standards. Prices show a moderate increase in the intermediate and prime segment (+4–7%), with an indicative range between €3,500 and €5,500 per sqm and a recognized value for architectural quality, landscape context, and privacy. Trulli and farmhouses constitute a separate segment, with prices determined by their configuration, integrity, and quality of context, capturing selective international demand. At the same time, newly built or renovated villas, contemporary or hybrid, are gaining greater importance in response to the need for comfort, efficiency, and flexibility of use. Villas, farmhouses and renovated units account for the majority of transactions, with short sales times.
Italian and foreign buyers
Source: Engel & Völkers Italy
PURCHASES WITHOUT HOME LOAN
Demand for second homes remains prevalent, supported by favourable territorial factors. Further consolidation of the premium segment is expected in 2026 H2.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
3-4 K €/sqm +4/+7% 500K-1,2M €
TOP PRICE
4,5K €/sqm
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Salento's prime market saw strong demand growth in 2025, driven particularly by foreign buyers, amid growing supply. The distribution of sales shows a clear predominance of the prime segment (60%), followed by intermediate (20%) and high-end (20%). The market is mainly driven by second homes (70%) and investments (30%). The most soughtafter property types are sea-view villas, farmhouses and historic buildings in cities and villages, as well as farmhouses with annexed land, typical of the Apulian countryside. Must-haves include outdoor spaces, bright rooms, and authentic Salento style and materials. Rigorous property selection speeds up sales, often closing within 1 month. Often, a short stay is the first driver of interest in the area, whose environmental and cultural qualities then generate a demand for second homes or the transfer of residence to the province.
The factors that could have the greatest impact are the
return of professionals from abroad, new infrastructure, and the reputational impact linked to international trends.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
1,8-4,2K €/sqm +4/+7%
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
500K-1,2M €
PURCHASES WITHOUT HOME LOAN
4,5K €/sqm 70% 65 %
Source: Istat e Engel & Völkers
Palermo's prime market has shown signs of moderate growth, with increasing demand and substantially stable supply. The intermediate segment of the market stands between €1,400 and €2,300 per sqm, with increases of between +1% and +3% on an annual basis, while the prime sector is between €1,850 and €4,300 per sqm, recording more significant increases of 4-7%. The high-end segment, with prices between €2,000 and €4,500 per sqm, is driven by interest in new or renovated properties in the city centre and the most prestigious areas. Buyers favour apartments, penthouses, and villas, with terraces, gardens, views, and parking spaces among the main requirements. International demand, mainly from Central Europe, represents around 25% of transactions, fuelling the second home component and contributing to the share of purchases without resorting to credit (65%). Average sales times vary from 1 to 3 months in the centre and from 3 to 6 months in other areas. Among the factors that mainly influence the prime
real estate market are purchasing power, property quality, and foreign attractiveness. Stability is expected in the lowmedium segment for 2026 H2, along with further growth in the prime and high-end segments, influenced by interest rates, fiscal policies, and the international scenario. Palermo thus confirms its ability to attract both domestic buyers and foreign investors interested in prime properties and second homes.
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
4,5-5K €/sqm +1/+3% 500-800K € 7K €/sqm 70 % 57 %
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The Catania market appears to be undergoing a structural transition: the growing tourist industry, supported by the airport and Sicily's overall attractiveness, is reshaping the composition of demand, with an expanding share of investment purchases, particularly B&Bs and holiday homes, and a growing foreign presence, predominantly European. In terms of prices, the prime segment is growing by 1% to 3%, with prices ranging from €1,800 to €2,400 per sqm, the intermediate segment has remained essentially constant, ranging from -1% to 0%, while the high-end segment is showing the most positive trend, with increases between +4% and +7%. Demand is focused on penthouses and newly built units, with a strong focus on construction quality, energy efficiency and essential requirements such as a terrace or balcony, outdoor spaces, views and parking spaces. Forecasts for 2026 H2 indicate further growth in the prime segment, confirming the market's attractiveness for both local and international buyers.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS PURCHASES WITHOUT HOME LOAN
2,9-4,5K €/sqm +1/+3% 500K-1,2M € 6,5K €/sqm 55 % 61 %
Source: Istat e Engel & Völkers
The prime real estate market in Trapani and the surrounding islands is showing moderate growth in demand while supply remains stable. The trend is substantially stable in all areas on an annual basis. Demand is driven mainly by Italian buyers (89%), but with a selective international component (11%), particularly European and North American, looking for apartments, villas and farmhouses. Sales times range between 3 and 6 months in central and semi-central areas, exceeding 6 months in the more peripheral areas. The highend market is more dynamic and selective than the traditional one, with prices slightly increasing thanks also to international demand and the scarcity of supply. Prime properties with distinctive features, including sea views and direct access, restored historic buildings, and villas with swimming pools, are favoured. For 2026 H2, stability is expected in the intermediate segment and growth in the prime and high-end ones, with
possible impacts linked to interest rate trends, international stability and a return to the local area.
Sales by type of investment
2025 Data
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,5-3K €/sqm +1/+3%
TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
The Messina market shows moderately growing demand while supply remains stable, with prices slightly increasing across all segments. Sales are concentrated in the intermediate (50%) and prime (40%) segments, while the high-end one remains a niche. Average prices range between €800 and €1,300 per sqm for the intermediate segment and between €1,500 and €2,000 per sqm for the prime segment. Buyers' interest is focused on habitable used properties, particularly apartments, villas, and penthouses, with a strong demand for terraces, gardens, parking spaces, and energy efficiency ratings. The target is made up almost exclusively of Italians (95%), with a prevalent age between 35 and 44 years. Sales times are 1-3 months in the centre and prime areas and 3-6 months in other areas. Among the factors influencing the market are the quality of life, infrastructure and transport, as well as the ongoing urban redevelopment. Forecasts for 2026
AVERAGE BUDGET IN PRIME SEGMENT
€
PURCHASES WITHOUT HOME LOAN
indicate stable demand for the intermediate segment and growing demand for the prime one.
Sales by type of investment
2025 Data
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,5-4,5K €/sqm +1/+3%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
€
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The prime market of the Aeolian Islands and the Tyrrhenian coast of Messina is experiencing moderate growth in demand, accompanied by a progressive increase in the availability of properties on the market. The area benefits from the growing interest of international clients attracted by the quality of the landscape, natural setting, and prices that are still relatively competitive compared to other Mediterranean destinations. Overall, the market trend is stable in all macro-areas. Demand is mainly made up of Italian buyers (around 65%), while international customers represent 35% of the total. Among foreign buyers, Europe clearly prevails (over 70%), followed by North America with a share of between 20% and 30%. The most sought-after types of properties are penthouses, villas and farmhouses, often intended for seasonal residence or for development projects. For 2026 H2, expectations indicate a stable demand in all market segments.
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
1,6-3,5K €/sqm +4/+7%
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The Ragusa and Modica market is characterized by moderately growing demand and stable supply, with marked interest in properties that have already been renovated or are in excellent condition. The push comes in significant measure from abroad, attracted by the quality of life, the rural landscape and the charm of the Baroque. Sales are evenly split between the intermediate and prime segments; the market is primarily driven by second home purchases (60%). Prices in the most sought-after areas reach €3,500–€4,000 per sqm for new or renovated properties, while the high-end segment is experiencing further growth, with prices rising more than 10%, driven by demand for villas, farmhouses, and detached properties with gardens, views, and privacy. Sales times are rapid in the most dynamic areas, often less than a month, while in less central areas they can extend up to 3–6 months. The outlook for 2026 H2 is essentially one of stability for the prime and high-end segments.
Italian and foreign buyers
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
3,5-6K €/sqm +4/+7%
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
AVERAGE BUDGET IN PRIME SEGMENT
500-800K €
PURCHASES WITHOUT HOME LOAN
Source: Istat e Engel & Völkers
The prime market in the Syracuse and Noto area has shown moderately growing demand while supply has remained substantially stable. Interest is focused primarily on properties that have already been renovated or are newly built, particularly in historic centres and the most soughtafter coastal locations. International demand plays a significant role and continues to grow, attracted by the area's quality of life, historical-baroque heritage, and tourism potential. Sales are mainly concentrated in the prime segment, which represents around 70% of transactions and sees prices ranging between €2,000 and €3,500 per sqm, while the intermediate segment covers a more limited share (20%) and the high-end one remains selective (10%). Demand favours apartments and villas with terraces, gardens, and sea views, with a growing focus on property quality and historic architectural features.
For 2026 H2, stable demand is expected in the intermediate segment and growth in the prime and high-end segments.
Sales by type of investment
Source: Engel & Völkers Italy
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
4,7-9K €/sqm +1/+3% 500K-1,2M €
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
Taormina's prime market operates in a dynamic and selective context. Demand is growing moderately, while supply tends to decrease, especially for properties in good condition and with sea views, which are increasingly rare. The prime and high-end segments, which account for almost all transactions (70% and 25% respectively), saw a slight increase in prices, between 1% and 3%. Prime properties reach €9,000 per sqm, with peaks of €12,000 per sqm for high-end ones. The international component, equal to 30%, continues to play a significant role in the most qualified requests, but the majority of buyers remain Italian. The market is driven by high-end second homes, characterised by panoramic terraces, gardens and privileged locations. Sales times in the most attractive areas remain short (from 1 to 3 months), while in less central areas they reach up to 6 months. Stability is expected across all segments for 2026 H2.
Sales by type of investment
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
2,5-3,2K €/sqm +1/+3% 500-800K €
AVERAGE BUDGET IN PRIME SEGMENT TOP PRICE
EUROPEAN BUYERS OVER INTERNATIONAL BUYERS
PURCHASES WITHOUT HOME LOAN
3,5K €/sqm
Source: Istat e Engel & Völkers
In the real estate market on Etna and the Ionian Coast, demand is driven by predominantly Italian buyers (70%), aged between 35 and 44, oriented towards villas and farmhouses with outdoor spaces and excellent energy performance. The local market has been stable for several years now, following strong increases in previous years, mainly due to the revaluation of wine-growing areas.
Prices average around €2,000 per sqm for the prime segment, with peaks of up to €5,000 per sqm and an annual variation of between 1% and 3%. In 2025, supply and demand remained stable and average sales times in central areas were between 1 and 3 months, with a peak of up to 6 months in the semi-central areas. The incidence of purchases with a mortgage remains extremely low, equal to 10% of buyers.
For 2026 H2, expectations converge on substantial market stability in both the prime and high-end segments.
Source: Istat e Engel & Völkers
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
growth in prices, supported by construction quality, connectivity, and the opening of the Sardinia International School, a new hub for international families. NEW/RENOVATED,
EUROPEAN BUYERS OVER
PURCHASES WITHOUT HOME LOAN
Real estate demand in Olbia and the surrounding area is strongly oriented towards the high-end segment, which accounts for 50% of the market, while the prime segment makes up 40% of it. In the high-end segment, prices range between €12,000 and €23,000 per sqm, while for prime properties the range is between €9,000 and €15,000 per sqm. The market is experiencing moderate growth, with average sales times between 3 and 6 months in the peak areas and over 6 months in the remaining areas. The typical buyer profile is between 45 and 54 years old, with an international component of 60% (half of which is European) and an Italian component of 40%. Preferences focus on habitable used properties, particularly apartments, villas, and farmhouses, with essential requirements such as sea views, outdoor spaces, and privacy, in contexts located a short distance from airports and international schools. The outlook for 2026 suggests
Sales by type of investment
NEW/RENOVATED, 2026 PRIME PRICE
PRICE VARIATION IN PRIME SEGMENT (Y-O-Y %)
AVERAGE BUDGET IN PRIME SEGMENT
Source: Istat e Engel & Völkers
The Costa Smeralda market confirms a positioning clearly oriented upwards: the high-end segment represents 60% of sales and prime 30%, with prices ranging between €29,000 and €35,000 per sqm and between €16,000 and €22,000 per sqm respectively. Despite stable supply, demand has shown moderate growth, driven almost entirely by the international component—predominantly European—which orients purchases toward second homes and investments, each accounting for 40%, with a clientèle concentrated in the 55-64 age group. Interest is focused on exclusive properties that guarantee privacy, waterfront location, or stunning views, with villas, penthouses, and farmhouses as the preferred typologies, and views, gardens, and terraces as essential requirements. Decision-making times range from 3 to 6 months in prime areas, extending beyond 6 months in the rest of the market.
Forecasts for 2026 H2 indicate that the growth trend for the prime and high-end segments will continue.
Italian and foreign buyers
Source: Engel & Völkers Italy
Milano, Marzo 2026