Solutions Manual for Taxation for Business Entities 2026 1st Edition by Carnes, Youngberg
ISBN: 9781119744184
Carnes/Youngberg: Taxation of Business Entities, 2026 Edition
Chapter 1: Basics of Business Entity Taxation
End-of-Chapter Solutions
Discussion Questions
1. Describe the entity theory.
Title: Discussion Question 1
Difficulty: Easy
Learning Objective 1: 1.1
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.1
Solution:
The entity theory provides that a business is a distinct entity from its owners. Thus, any time that cash or property passes between the entity and the owners, there are potential tax consequences.
Time on Task: 2 minutes
2. Explain the difference between an operating distribution and a liquidating distribution.
Title: Discussion Question 2
Difficulty: Easy
Learning Objective 1: 1.1
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.1
Solution:
If an operating distribution is made to the owners, then the recipient continues to be an owner after the distribution. If a liquidating distribution is received, then the recipient is no longer an owner after the distribution. The entity will remain in existence as long as it has other owners. If all owners receive liquidating distributions, then the entity is dissolved.
Time on Task: 2 minutes
3. What is the due date for partnerships and S corporations to file their income tax returns?
Title: Discussion Question 3
Difficulty: Easy
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.2
Solution:
Partnership tax returns and S corporation tax returns are due two and one-half months after the end of the tax year, which is March 15 for a calendar-year business. Extensions for partnership and S corporations are for six months, which is September 15 for a calendar-year business.
4. Define statute of limitations and explain how it applies to tax assessment and refunds.
Title: Discussion Question 4
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.2
Solution:
The statute of limitations sets the period during which one party can pursue a cause of action against another party. The statute of limitations regarding tax assessment runs for three years from the later of (1) the due date of the return, or (2) the date the return was filed.
Time On Task: 3 minutes
5. Describe the failure to pay penalty and the failure to file a tax return penalty.
Title: Discussion Question 5
Difficulty: Hard
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.2
Solution:
The failure to file a tax return penalty is imposed on the tax balance due at 5% per month (up to 25%) with a minimum penalty amount of the lesser of $525 (2025) or the amount of tax due. If there is no balance due with the tax return, there is no failure to file penalty imposed. The minimum penalty applies only if the taxpayer does not file the tax return within 60 days of the due date and the computed penalty amount is less than the minimum penalty.
Additionally, S corporations and partnerships must also pay a penalty equal to $255 (2025) per shareholder/partner for each month, or part of a month, that the return is late. The penalty is assessed for no more than 12 months.
The failure to pay the tax due penalty is imposed on the tax balance due at 0.5% per month (up to 25%). If there is no balance due with the tax return, there is no failure to pay penalty imposed. A fraction of a month counts as a full month for both penalties. If both the failure to pay penalty
and the failure to file penalty potentially apply, the maximum penalty for both is limited to 5% of the tax due per month.
Time On Task: 8 minutes
6. What is meant by the term substantial authority?
Title: Discussion Question 6
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.2
Solution:
Substantial authority is based upon weighing the supporting evidence and authority for taking a position on the tax return. Substantial authority indicates a probability that the taxpayer’s position will be sustained upon audit or litigation and is generally held to be 40% or less. The “more likely than not” standard is defined as a greater than 50% chance of a position being sustained on its merits.
Time On Task: 4 minutes
7. Provide two examples of an accuracy-related penalty.
Title: Discussion Question 7
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.2
Solution:
Examples of an accuracy related penalty include errors from negligence, substantial understatement of a taxpayer’s tax liability, as well as substantial or gross misvaluation. The most serious civil accuracy penalty the IRS can assess a taxpayer is for fraud.
Time On Task: 4 minutes
8. What does the tax law include in amount realized?
Title: Discussion Question 8
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
Conceptually, amount realized represents the value that the owner of the property receives because of the disposition. Computing amount realized is a four-step process:
Step 1. Cash received
Step 2. Plus: Fair market value of any property and services received
Step 3. Plus: Liabilities assumed by the buyer, reduced by debts of buyer assumed by seller
Step 4. Less: Selling or disposition expenses
Time On Task: 4 minutes
9. What is the difference between realized gain or loss and recognized gain or loss?
Title: Discussion Question 9
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
The taxpayer must compute a realized gain or loss every time there is a sale or disposition of property. Realized gain or loss is amount realized less adjusted basis. A recognized gain or loss is one that the taxpayer includes in the computation of taxable income.
Time On Task: 4 minutes
10. Provide two reasons why realized gain might be deferred for tax purposes.
Title: Discussion Question 10
Difficulty: Hard
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solutions:
Two reasons why Congress allows gains to be deferred are:
1. The transaction did not generate any cash for the taxpayer, so if the taxpayer did have to pay taxes, the cash must come from other sources.
2. The taxpayer’s economic situation has not changed significantly because of the transaction, so Congress does not believe it is appropriate to tax gains at that time Time On Task: 4 minutes
11. Provide a definition for boot.
Title: Discussion Question 11
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
The law defines boot as any property exchanged that is not qualified property, including cash. Time On Task: 2 minutes
12. How does a tax-deferred transaction impact the holding period of an asset?
Title: Discussion Question 12
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
For a tax-deferred transaction, the holding period of property received always includes the holding period of the property transferred. Because the taxpayer is deferring gain or loss that has accrued on the asset transferred, then the holding period of the asset received should include the time period during which the deferred gain or loss accrued.
Time On Task: 4 minutes
13. Define related-party transaction.
Title: Discussion Question 13
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
A related-party transaction is an agreement between two parties that have a preexisting business relationship or familial relationship. The term related party includes the following family members: spouse, children, grandchildren/other descendants, parents, grandparents/other ancestors, and brothers and sisters. Aunts, uncles, and cousins are not related parties, and neither are in-laws. A business relationship can include ownership of more than 50% (directly or indirectly) of a corporation or partnership.
Time On Task: 2 min
14 Does the related-party loss disallowance rule apply even when the selling price is equal to the fair market value and can be substantiated by a qualified appraisal?
Title: Discussion Question 14
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
Yes, the related party loss rule applies regardless of whether the selling price and fair market value are the same or different amounts. The disallowance rule applies if a loss is realized, even if a qualified appraisal verifies the taxpayer sold the asset for its actual value.
Time On Task: 3 min
15. Why is it important to differentiate among ordinary assets, Section 1231 assets, and capital assets?
Title: Discussion Question 15
Difficulty: Medium
Learning Objective 1: 1 3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
It is important to identify an asset as ordinary, Section 1231, or capital because each category is treated differently for tax purposes. The character of the asset determines whether the asset is depreciable, whether gain is taxed at ordinary or preferential rates, and whether losses can be deducted.
Time On Task: 3 minutes
16. Distinguish between realty and personalty
Title: Discussion Question 16
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
Realty is land and any structure that is permanently attached to the land. The most common type of asset that is permanently attached to land is buildings. Individuals often refer to realty as real property. Personalty is any asset that is not realty. Taxpayers often refer to personalty as personal property.
Time On Task: 3 minutes
17. When is an asset deemed long-term for holding-period purposes? Why is this important?
Title: Discussion Question 17
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
The tax law treats an asset as long-term when the asset has been held for more than one year. It is important because if the taxpayer sells an asset and generates a long-term capital gain, then the individual uses a preferential long-term capital gain rate when calculating liability. Corporations do not have a preferential rate for long-term capital gains. It is also important in a trade or business because a long-term asset is characterized as a Section 1231 asset.
Time On Task: 3 minutes
18. If a business-use asset held long-term is sold at a loss, and it is the only business-use asset sold during the year, what is the character of that loss?
Title: Discussion Question 18
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
A business-use asset held long-term is a Section 1231 asset. If this is the only asset sold in the current year, a Section 1231 asset sold at a loss is characterized as an ordinary loss.
Time On Task: 3 minutes
19. Explain the five-year lookback rule regarding Section 1231 net gains.
Title: Discussion Question 19
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
When a taxpayer sells business-use assets, recognized gains and losses occur. The taxpayer nets all Section 1231 gains and losses. If a net Section 1231 gain results, the taxpayer must look back five years to determine if any net Section 1231 losses occurred that were treated as ordinary
losses. To the extent of those previous ordinary losses, the current Section 1231 gain is treated as ordinary. Any remaining Section 1231 gain is treated as a long-term capital gain.
Time On Task: 4 minutes
20. Does the lookback rule apply to both net Section 1231 gains and losses generated in the current year?
Title: Discussion Question 20
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
The five-year lookback rule applies only to net Section 1231 gains generated in the current year. A net Section 1231 loss is always an ordinary loss in the current year.
Time On Task: 2 minutes
21. What is a Section 1245 asset?
Title: Discussion Question 21
Difficulty: Medium
Learning Objective 1: 1 4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
A Section 1245 asset is tangible, depreciable, or amortizable property other than land or buildings that is used in a trade or business and has been owned for more than one year. If a Section 1245 asset is sold at a gain, the amount is characterized as ordinary to the extent of the accumulated depreciation taken, but not to exceed the recognized gain. This is referred to as Section 1245 depreciation recapture. If the gain is in excess of the accumulated depreciation, the remaining amount would be considered Section 1231, long-term capital gain. If a Section 1245 asset is sold at a loss, the recapture rules do not apply, and the loss is a Section 1231 loss.
Time On Task: 5 minutes
22. If Section 197 intangible assets are purchased as part of an acquisition of a business, how are they treated when they are sold?
Title: Discussion Question 22
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
Section 197 intangible assets (e.g., patents, copyrights, purchased goodwill) are amortized, and amortization expense is deducted each year. When a Section 197 asset is sold, Section 1245 recapture applies to the lesser of the recognized gain or the amortization taken on the asset. If there is any remaining gain after recapture, it is treated as a Section 1231 gain because the asset was used in a trade or business and held for more than one year.
Time On Task: 3 minutes
23. What is a Section 1250 asset?
Title: Discussion Question 23
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
A Section 1250 asset is a building used in a trade or business and owned for more than one year. If a Section 1250 asset is sold at a gain, the gain could be taxed in three different ways. First, the amount is characterized as ordinary income to the extent of the excess of accelerated depreciation taken over what straight line depreciation would have been, but not to exceed the recognized gain. Under current law, a Section 1250 asset is depreciated using straight-line depreciation so there is no excess depreciation. Second, for individuals, the gain that is not subject to Section 1250 recapture is next treated as unrecaptured Section 1250 gain to the extent of straight-line depreciation. Second, for corporations, the gain not subject to Section 1250 recapture is next treated as Section 291 gain. Section 291 is taxed as ordinary income and is generally 20% of the recapture that would have been recognized if the property was Section 1245 property. Third, the remaining gain, if any, is treated as Section 1231 gain. If a Section 1250 asset is sold at a loss, the recapture rules do not apply, and the entire loss is characterized as Section 1231.
Time On Task: 5 minutes
24. What is unrecaptured Section 1250 gain?
Title: Discussion Question 24
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
Unrecaptured Section 1250 gain represents the portion of gain that is attributable to straight-line depreciation taken on a building used in a trade or business. For individuals, gain attributable to unrecaptured Section 1250 gains is taxed at a maximum tax rate of 25%.
Time On Task: 3 minutes
25. On what tax form does a taxpayer report the sale of business-use assets?
Title: Discussion Question 25
Difficulty: Easy
Learning Objective 1: 1 4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
Form 4797, Sale of Business Property, is used for sales of business use property. If a corporation has net Section 1231 gains, it is transferred to Form 1120, Schedule D.
Time On Task: 1 minute
26. Provide some examples where the recapture rules do not apply.
Title: Discussion Question 26
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
In the case of a sale of an asset that was received as a gift, the recapture potential carries over to the donee. The recapture provision does not apply to the donor. In the case of a sale of an asset that was received through inheritance, the recapture potential is eliminated. In the case of charitable contribution of property that would have generated depreciation recapture if it had been sold, the amount that would have been recaptured reduces the charitable contribution deduction. In the case of a sale of an asset that was received through certain tax-free exchanges, recapture potential carries over to the new owner with the property received in the exchange.
Time On Task: 4 minutes
27. What is a specified service business activity?
Title: Discussion Question 27
Difficulty: Easy
Learning Objective 1: 1.5
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.5
Solution:
A specified service business activity is any trade or business involving the performance of services in the fields of health, law, accounting, actuarial science, performing arts, consulting, athletics, financial services, brokerage services, or any trade or business where the principal asset of such trade or business is the reputation or skill of an employee or owner. Time On Task: 3 minutes
Multiple Choice Questions
1. A C corporation files which tax form to report its income, expenses, and credits?
a. Form 1120
b. Form 1040
c. Form 1065
d. Form 1120-S
Answer: a
Title: Multiple Choice Question 1
Difficulty: Hard
Learning Objective 1: 1.1
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.1
Solution:
A C Corporation is an incorporated entity that has not made an election to be taxed as an S corporation and files Form 1120, U.S. Corporation Income Tax Return. Time On Task: 1 minute
2. Form 1041 is used to file a tax return for which entity?
a. Corporation
b. Partnership
c. Trust
d. Limited liability company
Answer: c
Title: Multiple Choice Question 2
Difficulty: Hard
Learning Objective 1: 1.1
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.1
Solution:
Business trusts file Form 1041, U.S. Income Tax Return for Estates and Trusts.
Time On Task: 1 minute
3. On what day, in general, is Form 1120 due for a calendar year-end corporation, not including extensions and without incurring a possible penalty?
a. March 15
b. April 1
c. April 15
d. June 30
Answer: c
Title: Multiple Choice Question 3
Difficulty: Easy
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1 2
Solution:
The correct answer is April 15.
Form 1120 for a calendar year end corporation is due on April 15 unless April 15 falls on a Saturday, Sunday or holiday. Then, the next business day that is not a holiday will be used.
Time On Task: 2 minutes
4. If Burger Inc. (a calendar year-end corporation) filed its Year 3 tax return on February 14, Year 4, when does the statute of limitations expire for assessing additional tax?
a. February 14, Year 6
b. April 15, Year 6
c. February 14, Year 7
d. April 15, Year 7
Answer: d
Title: Multiple Choice Question 4
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge Section Reference 1: 1.2
Solution:
The correct answer is April 15, Year 7.
If Burger Inc. filed its tax return on February 14, Year 4, the statute of limitations for assessing additional liability is three years from the later of (1) the due date the tax return, or (2) the date the tax return was filed.
Time On Task: 3 minutes
5. Heather Inc. inadvertently failed to e-file its Year 10 tax return on April 15, Year 11, but it did pay its balance due of $1,500 on time. Heather Inc. e-filed on June 3, Year 11. What late filing penalty does Heather Inc. incur?
a. $0
b. $150
c. $215
d. $500
Answer: b
Title: Multiple Choice Question 5
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
The correct answer is $150.
The penalty for failure to file is 5% of the tax due per month (or partial month). The maximum penalty is 25%. Heather Inc.’s penalty is $150 ($1,500 5% 2 months).
Time On Task: 4 minutes
6. Rico Inc. sells a parcel of investment real estate and receives $120,000 cash and stock with a fair market value of $100,000 and basis of $60,000. Additionally, the $50,000 mortgage on the property is assumed by the buyer. Rico Inc. paid an attorney $1,000 to execute the sale. The week before the sale, Rico paid $75 to have a fence repaired on the property. The basis in the parcel of investment real estate is $200,000. What is Rico Inc.’s amount realized from selling the property?
a. $219,000
b. $268,925
c. $269,000
d. $270,000
Answer: c
Title: Multiple Choice Question 6
Difficulty: Hard
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
The correct answer is $269,000
The amount realized from selling the property is equal to:
Cash received
$120,000
Plus: FMV of other property received 100,000
Plus: Liabilities assumed by the buyer 50,000
Less: Selling expenses (1,000)
Amount realized
$269,000
The $75 for the fence is a repair and does not impact the amount realized.
Time On Task: 5 minutes
7. Which of the following fall under the related-party relationship rules for loss disallowance on sale of an asset? Select all that apply.
a. Two cousins
b. A shareholder who owns 60% of a corporation’s stock
c. Brother and sister
d. Mother-in-law and daughter-in-law
Answer: b, c
Title: Multiple Choice Question 7
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
The correct answers are:
• A shareholder who owns 60% of a corporation’s stock, and
• Brother and sister.
Both meet the definition of a related party. The two cousins do not meet the family membership definition for related parties. Family members include brothers, sisters, spouses, parents, grandparents and lineal descendants (children and grandchildren) of the taxpayer. In-laws are also not considered to be related parties for this purpose (although in-laws are eligible to be claimed as dependents).
Time On Task: 2 minutes
8. On April 16, Year 10, Alvin Inc. sold 200 shares of Chipmunk stock to its 100% shareholder, Tang, for $18,000. Alvin Inc. purchased the stock in Year 5 for $23,000. Tang sold the stock to Amber, an unrelated third party, for $30,000 on December 28, Year 10. What amount of gain from the sale of the stock to Amber should Tang report on his Year 10 income tax return?
a. $0
b. $2,000
c. $5,000
d. $7,000
Answer: d
Title: Multiple Choice Question 8
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
The correct answer is $7,000.
The loss on sale to Tang of $5,000 (Amount realized $18,000 – Adjusted basis $23,000) is not recognized due to related party rules. Tang owns more than 50% of Alvin Inc. stock. However, it does create a right of offset for $5,000. Thus, when Tang subsequently sells the stock, there is a realized gain of $12,000 (Amount realized $30,000 – Adjusted basis $18,000). The $5,000 right of offset reduces Tang’s recognized gain from $12,000 to $7,000.
Time On Task: 4 minutes
9. Which of the following is an ordinary asset?
a. Computer
b. Delivery truck
c. Accounts receivable
d. Equipment
Answer: c
Title: Multiple Choice Question 9
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1 3
Solution:
The correct answer is Accounts receivable
Accounts receivable is an ordinary asset that produces ordinary income. The computer, delivery truck, and equipment are all Section 1231 assets if used in a trade or business and held longterm.
Time On Task: 2 minutes
10. Which of the following assets would be classified as ordinary for purposes of determining the character of gain or loss?
I. Personal residence
a. II
b. II, III
c. I, II
II. Inventory
III. Asset sold by a business that had been owned for eight months
d. I, II, III
Answer: b
Title: Multiple Choice Question 10
Difficulty: Easy
Learning Objective 1: 1 3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
The correct answer is II, III
Both inventory and assets used in a trade or business but held short term are ordinary assets. A personal residence is a capital asset.
Time On Task: 3 minutes
11. Which of the following assets would be classified as capital for purposes of determining the character of gain or loss?
I. Equipment used in a business
II. Land owned by a dealer in real estate
III. Stock owned by a corporation
IV. Copyright owned by author of book
a. III
b. IV
c. II, III
d. I, II, III, IV
Answer: a
Title: Multiple Choice Question 11
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1 3
Solution:
The correct answer is III
Stock owned by a corporation is a capital asset because it is held for investment purposes. Equipment used in a trade or business and held long term is a Section 1231 asset. Land owned by
a dealer in real estate is inventory. A copyright owned by an author of a book is an intangible ordinary asset.
Time On Task: 3 minutes
12. Which of the following is an example of realty?
a. Storefront property
b. Land
c. Apartment building
d. Warehouse
e. All of these
Answer: e
Title: Multiple Choice Question 12
Difficulty: Easy
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.3
Solution:
The correct answer is All of these All of the choices are correct because they are land or buildings.
Time On Task: 2 minutes
13. Wolf, Inc. had the following net Section 1231 gains/losses for its first four years of operations:
Year 1 $10,000
Year 2 $ 4,000
Year 3 $12,000
Year 4 ($18,000)
In Year 5, Wolf has a net Section 1231 gain of $30,000. How will this gain be taxed according to the following classification?
a.
c.
d. $12,000 $18,000
Answer: a
Title: Multiple Choice Question 13
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
The correct answer is Ordinary income – $18,000, Long-term capital gain – $12,000.
A gain is taxed as ordinary income to the extent of unrecaptured Section 1231 losses from the last five years. Year 4 had a net Section 1231 loss of $18,000 which is recaptured in Year 5. The remaining Year 5 net Section 1231 gain is long-term capital gain.
Time On Task: 5 minutes
14. On January 1, Year 8, Whitehouse Corp. placed into service five-year MACRS equipment with an initial tax basis of $10,000. On December 31, Year 10, Whitehouse sold the property for $8,000, after having taken $6,000 in MACRS depreciation deductions. What amount of the gain should Whitehouse recapture as ordinary income under the Section 1245 recapture rules?
a. $0
b. $2,000
c. $4,000
d. $6,000
Answer: c
Title: Multiple Choice Question14
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1 4
Solution:
The correct answer is $4,000.
Recognized gain is $4,000 (Amount realized $8,000 Adjusted basis $4,000), recaptured to the extent of depreciation claimed of $6,000. Time On Task: 4 minutes
15 Tanner Company purchased and placed into service seven-year furniture on March 15, Year 2. The furniture cost $3,600 and was sold in Year 4 for $4,000 after taking $1,711 in MACRS depreciation deductions. What amount should Tanner recapture as ordinary income under the Section 1245 recapture rules?
a. $0
b. $1,711
c. $1,889
d. $2,111
Answer: b
Title: Multiple Choice Question 15
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1 4
Solution:
The correct answer is $1,711.
Recognized gain is $2,111 (Amount realized $4,000 Adjusted basis $1,889), recaptured to the extent of the depreciation claimed of $1,711.
Time On Task: 4 minutes
16. Becker Company sold a business-use computer for $1,000 in December of the current year. Becker Company had purchased the computer several years earlier for $2,800 and had taken $1,500 of MACRS depreciation deductions as of the date of the sale. What amount is subject to Section 1245 depreciation recapture?
a. $0
b. $1,300
c. $1,500
d. ($300)
Answer: a
Title: Multiple Choice Question 16
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1 4
Solution:
The correct answer is $0.
The recognized loss is ($300) (Amount realized $1,000 Adjusted basis $1,300). Depreciation recapture does not apply to losses.
Time On Task: 3 minutes
17. Carmella LLC purchased a commercial building on June 1, Year 3, for $200,000. The building was depreciated using regular MACRS straight-line depreciation. The apartment building was sold on December 31, Year 8, for $330,000 when its adjusted tax basis was $160,000 (assume that $40,000 of depreciation had been claimed). How much gain from the sale of the building is subject to the 25% rate as unrecaptured Section 1250 gain, and how much gain qualifies as Section 1250 depreciation recapture?
Unrecaptured Section 1250 gain at 25% rate
a. $ 0
b. $ 40,000
Section 1250 recapture
$170,000
$130,000
c. $ 40,000
d. $170,000
Answer: c
Title: Multiple Choice Question 17
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
0
0
The correct answer is Unrecaptured Section 1250 gain at 25% rate $40,000, Section 1250 recapture $0.
There is no Section 1250 recapture on realty depreciated under the straight-line method. The unrecaptured Section 1250 gain is taxed at 25% to the extent of straight-line depreciation claimed.
Time On Task: 4 minutes
18. Anthony Inc., an S corporation, purchased a rental apartment building for $325,000 in April 1984. The corporation elected to depreciate it using the 150% declining balance method with a useful life of 50 years, resulting in accelerated depreciation taken of $260,000. Straight-line depreciation would have been $220,000. Anthony Inc. sold the building in November 2025, for $400,000. What portion of the gain is subject to Section 1250 recapture?
a. $0
b. $40,000
c. $65,000
d. $335,000
Answer: b
Title: Multiple Choice Question 18
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1 4
Solution:
The correct answer is $40,000. The gain recognized is $335,000 (Amount realized $400,000 Adjusted basis $65,000). The Section 1250 recapture is $40,000 (Accelerated depreciation $260,000 Straight line depreciation $220,000). The straight-line depreciation of $220,000 is taxed at 25% and the remaining gain of $75,000 is Section 1231 gain.
Time On Task: 4 minutes
19. Section 291 recaptures applies to which of the following entity types?
a. S corporation
b. C corporation
c. LLC that has not elected to be treated as a corporation
d. Partnership
Answer: b
Title: Multiple Choice Question 19
Difficulty: Easy
Learning Objective 1: 1.4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.4
Solution:
The correct answer is C corporation.
For Section 1250 property (buildings) for corporations, the accumulated depreciation claimed in excess of straight-line depreciation is subject to being recaptured as ordinary income, just as with individuals. However, the unrecaptured Section 1250 gain rule does not apply for corporations. Instead, Section 291 depreciation recapture applies and is computed by assuming the property is actually Section 1245 property.
Time On Task: 4 minutes
20. Where does the QBI deduction appear on Form 1040?
a. It is an itemized deduction taken on Schedule A of Form 1040.
b. It is a deduction from AGI on Form 1040 taken after the deduction for the greater of itemized deductions or the standard deduction.
c. It is a business deduction and is taken on Schedule C of Form 1040.
d. It is a deduction that reduces self-employment income and is taken on Schedule SE of Form 1040.
Answer: b
Title: Multiple Choice Question 20
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.5
Solution:
The correct answer is It is a deduction from AGI on Form 1040 taken after the deduction for the greater of itemized deductions or the standard deduction.
The QBI deduction is a deduction from AGI and is the last deduction taken in determining taxable income.
Time On Task: 3 minutes
21. Abe is the sole shareholder and president of Lincoln, Inc., an S corporation that is a qualified trade or business. In 2025, Lincoln has net income of $330,000 after deducting Abe’s salary of $75,000. What is Abe’s qualified business income?
a. $0
b. $75,000
c. $330,000
d. $405,000
Answer: c
Title: Multiple Choice Question 21
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
The correct answer is $330,000.
Abe’s qualified business income from Lincoln, Inc. is $330,000. Qualified business income does not include wages received.
Time On Task: 3 minutes
22. Which of the following is not a specified service activity for the purpose of calculating the qualified business income deduction?
a. Accounting
b. Financial services
c. Athletics
d. Architecture
Answer: d
Title: Multiple Choice Question 22
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.5
Solution:
The correct answer is Architecture.
Architecture is not considered a specified service activity in determining the QBI deduction.
Time On Task: 2 minutes
23. In 2025, Cal, who is single, earns sole proprietor income of $245,000 generated from his law practice. He does not have any employees or qualified assets. Cal’s modified taxable income is $285,000. How much is his QBI deduction?
a. $0
b. $49,000
c. $54,490
d. $57,000
Answer: a
Title: Multiple Choice Question 23
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
The correct answer is $0.
Since Cal’s modified taxable income exceeds $247,300, his specified service business generates zero QBI deduction. The wage/property limit does not apply in this example.
Time On Task: 3 minutes
Brief Exercises
1. Describe the three foundational principles for property transactions.
Title: Brief Exercise 1
Difficulty: Easy
Learning Objective 1: 1.1
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1.1
Solution:
Property Transactions Gain or Loss. You must compute a realized gain or loss every time there is a sale or disposition of property. The gain or loss could either be recognized and included in taxable income, deferred, or excluded. A taxpayer must recognize all realized gains and losses unless a tax law provides otherwise.
Property Transactions Basis. The basis of the asset received is the same as the basis in the asset transferred to the extent the taxpayer defers the realized gain or loss. For fully taxable transactions, the basis in the asset received is always the property’s fair market value.
Property Transactions Holding Period. For a tax-deferred transaction, the holding period of property received always includes the holding period of the property transferred. For a fully taxable transaction, the holding period of property received never includes the holding period of the property transferred.
Time On Task: 6 minutes
2. TennisNow is an S corporation with a calendar year-end. TennisNow filed its Form 1120-S for 2025 on December 26, 2026. TennisNow has eight shareholders. What is TennisNow’s penalty for late filing of its tax return?
Title: Brief Exercise 2
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
TennisNow’s Form 1120-S for 2025 was due on March 15, 2026, and it was filed on December 26, 2026, which is ten months late (nine full months and one partial month). TennisNow’s penalty is computed as follows:
$255 × 8 shareholders × 10 months = $20,400
3. Bennett owns 100% of Garrand Corporation, which does estate planning and consulting. After completing Garrand’s tax return this year, Bennett realized that Garrand owed $24,000 in taxes. Instead of paying the taxes as owed, Bennett reduced Garrand’s income by $100,000. How would the IRS respond to this situation?
Title: Brief Exercise 3
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
If the IRS later audited Garrand’s return and Bennet could not produce any evidence for the reduction in income, the IRS could assess a 75% fraud penalty against Garrand. If the IRS felt that it could prove beyond a reasonable doubt that Bennett intentionally and knowingly violated the tax law, it may also choose to pursue criminal sanctions against Bennett.
4. Shane Inc. exchanged its investment land (basis $43,000, FMV $56,000) for farming land (basis $44,000, FMV $51,000) and $5,000 cash. Assume this exchange qualifies as a taxdeferred transaction. What is Shane Inc.’s recognized gain, if any?
Title: Brief Exercise 4
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
The problem states that this exchange of investment land for farming land qualifies for deferral of gain. Shane Inc’s recognized gain is $5,000, calculated as follows:
Amount realized
$56,000 ($51,000 FMV of land received + $5,000 cash)
Less: Adjusted basis (43,000) (Adjusted basis of land given up)
Realized gain
$13,000
Recognized gain = Lesser of 1) Realized gain $13,000, or 2) Boot received (cash) $5,000
Time On Task: 6 minutes
5. Harriet owns 500 shares of Coca-Cola stock and paid $36 per share in 2018. She sold it in the current year for $30 per share to Ethyl Company, a partnership in which she has a capital interest of 35%. Ethyl Company later sold the stock to an unrelated third party for $50 per share. What is Harriet’s recognized gain or loss on the sale? What is Ethyl Company’s recognized gain or loss on the sale?
Title: Brief Exercise 5
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
Harriet will recognize a loss of $3,000 (Amount realized $15,000 – Adjusted basis $18,000). The loss is recognized because Ethyl Company is not a related party. Harriet owns only 35%, not more than 50%. Ethyl Company will recognize a gain of $10,000 (Amount realized $25,000 –Adjusted basis $15,000). Because the loss on the original sale was recognized, no right of offset was created, and Ethyl Company will recognize its entire gain.
Time On Task: 5 minutes
6. Harriet owns 500 shares of Coca-Cola stock and paid $36 per share in 2018. She sold it in the current year for $30 per share to Ethan Company, a partnership in which she has a capital interest of 65%. Ethan Company later sold the stock for $50 per share. What is Harriet’s recognized gain or loss on the sale? What is Ethan Company’s recognized gain or loss on the sale?
Title: Brief Exercise 6
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
Harriet will realize a loss of $3,000 (Amount realized $15,000 – Adjusted basis $18,000). Because Harriet sold the 500 shares to a partnership of which she owns more than 50%, this would be considered a related party sale, and her $3,000 loss would be disallowed. This creates a $3,000 right of offset that Ethan Company can use to offset its $10,000 gain (Amount realized $25,000 – Adjusted basis $15,000), resulting in a net gain of $7,000.
Time On Task: 5 minutes
7. Tito Company purchased equipment to be used in its business on January 9 of the current year. In December, Tito is considering selling the equipment. If Tito sells in December, what is the asset’s classification? If Tito sells it on January 10 of next year, what is the asset’s classification?
Title: Brief Exercise 7
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
If Tito Company sells the equipment in December, it would have held the asset for a year or less and it would be considered an ordinary asset. If Tito sells the equipment on January 10 of next year, it would have held the asset for more than 12 months and it would be considered a Section 1231 asset.
Time On Task: 4 minutes
8. Daewoon Company owns a popular restaurant on Main Street. During the current year, it sold various assets, resulting in net Section 1231 gains of $22,000 and net Section 1231 losses of $11,000. Daewoon Company also sold stock, which generated a capital loss of $9,000. What is the net effect of these transactions?
Title: Brief Exercise 8
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Application Section Reference 1: 1.4
Solution:
The $22,000 Section 1231 gain is netted with the $11,000 Section 1231 loss. The net Section 1231 gain of $11,000 is a Section 1231 gain which is a long-term capital gain. The stock loss of $9,000 can be used to offset the capital gain resulting in a net long-term capital gain of $2,000.
Time On Task: 3 minutes
9. Toucan owns Fit for U (FFU), an exercise facility. FFU sells weightlifting equipment for $44,000. FFU purchased the equipment four years ago for $75,000 and has accumulated
depreciation of $60,000. What is FFU’s realized and recognized gain or loss? What is the character of the gain or loss?
Title: Brief Exercise 9
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Amount realized
$44,000
Less: Adjusted basis (15,000) ($75,000 $60,000)
Recognized gain
$29,000
Section 1245 recapture = Lesser of: Recognized gain $29,000 or Depreciation taken $60,000
All the $29,000 recognized gain will be characterized as ordinary income under the Section 1245 recapture provision.
Time On Task: 5 minutes
10. Giada received a building to expand her pizza restaurant business as a gift from her Uncle Joey. The building had a fair market value of $225,000 and an adjusted basis of $100,000. Is Joey subject to the recapture provisions on the gift? Is Giada subject to the recapture provisions if she decides to sell the gifted building?
Title: Brief Exercise 10
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1 4
Solution:
The gift does not subject Uncle Joey to the recapture provisions. The recapture potential carries over to Giada, the recipient donee.
Time On Task: 2 minutes
11. Enid operates, as a sole proprietor, an animal shelter that generates net revenue of $88,000. Enid has also made a self-employed health insurance payment of $6,000. What is Enidʼs qualified business income?
Title: Brief Exercise 11
Difficulty: Easy
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
Enid’s qualified business income is $82,000 ($88,000 – $6,000). Enid reduces her QBI by the self-employed health insurance deduction. Time On Task: 2 minutes
12. Theo, single, is the sole shareholder of Theoʼs Tool and Dye, Inc., a tool and dye manufacturing company operating as an S corporation. Theo reports qualified business income of $118,000, and he has no employees. He also has qualified dividend income of $4,400. He has no itemized deductions and claims the standard deduction of $15,000 on his 2025 Form 1040. What is Theoʼs qualified business income deduction?
Title: Brief Exercise 12
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
Theo’s modified taxable income can be calculated as follows:
AGI Standard deduction – Qualified dividend income = Modified taxable income
AGI ($118,000 +4,400)
$122,400
Less: Standard deduction (15,000)
Less: Qualified dividend income (4,400)
Modified taxable income
QBI deduction is calculated as the lesser of:
• 20% QBI = 20% $118,000 = $23,600
$103,000
• 20% modified taxable income = 20% $103,000 = $20,600
In this case, Theo’s qualified business income deduction is $20,600. Time On Task: 5 minutes
Application Problems
1. Cain Inc. (a calendar year-end corporation) filed its 2025 Form 1120 on February 14, 2026. a. When will the statute of limitations for its 2025 return expire?
b. When will the statute of limitations expire if it filed its tax return on August 15, 2026?
c. When will the statute of limitations expire if Cain Inc. never filed its return?
Title: Application Problem 1
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
a. The statute of limitations for Cain Inc.’s 2025 return will expire on April 15, 2029. The primary statute of limitations runs for three years from the later of the due date of the tax return or the date the return is filed.
b. If Cain Inc. filed its tax return on August 15, 2026, the statute of limitations will expire on August 15, 2029. The primary statute of limitations runs for three years from the later of the due date of the tax return or the date the return is filed.
c. If Cain Inc. never filed its tax return, then the statute of limitations never begins running. So, the 2025 tax year will always be an open year that the IRS can audit.
Time On Task: 6 minutes
2. Granite Inc. filed its 2025 tax return on May 29, 2026, and never properly extended its tax return. Granite owed $6,400, which was paid on April 15, 2026.
a. How much is its failure to file penalty?
b. If it filed its return on December 15, 2026, what is its failure to file penalty?
Title: Application Problem 2
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
a. Granite’s failure to file penalty is $640 ($6,400 5% 2 months).
b. Granite’s failure to file penalty is $1,600 ($6,400 5% 8 months, limited to 25%).
Time On Task: 6 minutes
3. Granite Inc. filed its 2025 tax return on April 15, 2026. Granite Inc. owed $6,400 for its 2025 tax return, which was not paid when the return was filed.
a. How much is Granite’s failure to pay penalty if it filed its return on April 15, 202, and paid the balance due on May 29, 2026?
b. If Granite filed its return on April 15, 2026, and paid the balance due on December 15, 2026, what is its failure to pay penalty?
Title: Application Problem 3
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Application Section Reference 1: 1.2
Solution:
a. Granite’s failure to pay penalty is $64 ($6,400 0.5% 2 months).
b. Granite’s failure to pay penalty is $256 ($6,400 0.5% 8 months).
Time On Task: 6 minutes
4. Granite Inc. filed its 2025 tax return late and never properly extended its tax return. Granite’s failure to file its return on time was determined to be intentional and fraudulent. Granite owed $6,400 for its 2025 tax return.
a. How much is its failure to file penalty if it filed its return on May 29, 2026?
b. If it filed its return on December 15, 2026, what is its failure to file penalty?
Title: Application Problem 4
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
a. Granite’s failure to file penalty is $1,920 ($6,400 15% 2 months).
b. Granite’s failure to file penalty is $4,800 ($6,400 15% 8 months, limited to 75%).
Time On Task: 6 minutes
5. Asher Inc. is a medical supply corporation with a calendar year-end. Its tax liability is $56,000 for 2025 and $50,000 for 2024. How much must Asher Inc. pay in estimated income taxes in 2025 to avoid an underpayment penalty for 2025? Assume the annualization exception is not beneficial to Asher.
Title: Application Problem 5
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
To avoid an underpayment penalty Asher Inc. must pay estimated taxes at least equal to the lower of 100% of the 2025 tax liability or 100% of the 2024 tax liability. Therefore, Asher must
pay at least $50,000 of estimated taxes. If Asher Inc. does so, and the 2025 tax liability is $56,000, Asher must pay the remaining $6,000 ($56,000 - $50,000) by the due date of the tax return.
6. Decker Corporation owes $18,500 in tax liability with its 2025 tax return due on April 15, 2026. Decker filed its return, but unfortunately, Decker was not able to pay its liability until July 1, 2026. Assume that the federal short-term interest rate is 4%. How much will the IRS assess Decker for interest and penalties?
Title: Application Problem 6
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
Decker Corporation will owe $548. The interest rate is the short-term interest rate of 4% plus 3%, or 7%. It will pay interest of $270 ($18,500 7% 76/365). The failure to pay penalty will be 1.5% (0.5% 3 months), resulting in a penalty of $278 ($18,500 1.5%).
Time On Task: 5 minutes
7. Enthusiasm Learning Center is a partnership with a calendar year-end. Enthusiasm filed its Form 1065 for 2025 on October 5, 2026. Enthusiasm has 24 limited partners and one general partner. What is Enthusiasm’s penalty for late filing of its tax return?
Title: Application Problem 7
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.2
Solution:
Enthusiasm’s Form 1065 for 2025 was due on March 15, 2026, and it was filed on October 5, 2026, which is eight months late (seven full months and one partial month). Enthusiasm’s penalty is computed as follows:
$255 × 25 shareholders × 8 months = $51,000
8. Elijah Inc. owns an apartment building that it purchased 10 years ago for $345,000. Its current adjusted basis is $220,000, and the outstanding mortgage is $250,000. Elijah Inc. sells the building for cash of $300,000 plus assumption of the mortgage. Elijah Inc. pays commissions on the sale of $30,000, title transfer fees of $500, and an attorney at closing $1,000. What is Elijah Inc.’s realized and recognized gain?
Title: Application Problem 8
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
Cash received
$300,000
Plus: FMV of other property received 0
Plus: Liabilities assumed by the buyer
250,000
Less: Selling expenses (31,500) ($30,000 + $1,000 +$500)
Amount realized
$518,500
Less: Adjusted basis (220,000)
Realized and recognized gain
Time On Task: 8 minutes
$298,500
9. Chase Company would like to exchange land that it owns (adjusted basis $140,000 and FMV of $172,000) for land in a neighboring county (adjusted basis $120,000 and FMV $142,000) plus cash of $30,000. Assume that the parcels of land are qualified property for treating this as a deferred transaction, and that the cash is boot.
a. What is Chase’s realized gain?
b. What is Chase’s recognized gain?
c. What is Chase’s deferred gain?
d. What is Chase’s basis in the property received?
e. What is Chase’s holding period in the new property?
Title: Application Problem 9
Difficulty: Hard
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
a.
Amount realized
$172,000 ($142,000 + $30,000)
Less: Adjusted basis (140,000)
Realized gain $ 32,000
b. Recognized gain, $30,000 = Lesser of: Realized gain $32,000, or fair market value of boot received $30,000
c. Deferred gain ($2,000) = Realized gain ($32,000) less recognized gain ($30,000)
d.
Adjusted basis in property transferred
$140,000
Plus: Recognized gain 30,000
Less: Fair market value of boot received ( 30,000)
Less: Debt relief ( 0)
Basis in property received
Alternate Formula 2 is computed as follows:
Fair Market value of property received
$140,000
$142,000
Less: Deferred gain ( 2,000)
Plus: Deferred loss 0
Basis in property received
$140,000
e. For a tax-deferred transaction, the holding period of property received always includes the holding period of the property transferred.
Time On Task: 13 minutes
10. Evan owns investment land with an adjusted basis of $52,000 and fair market value of $42,000. He sells the land to Stan Corporation, an S Corporation for which he is an 80% shareholder, for $39,000. Stan Corporation then sells the land to an unrelated third party for $65,000.
a. What is Evan’s realized gain/loss and recognized gain/loss? What is Stan Corporation’s basis in the land purchased?
b. What is Stan Corporation’s realized gain/loss and recognized gain/loss?
c. Assume the same facts except Stan Corporation then sells the land to an unrelated third party for $45,000. What is Stan Corporation’s realized gain/ loss and recognized gain/loss?
d. Assume the same facts except Stan Corporation then sells the land to an unrelated third party for $35,000. What is Stan’s realized gain/loss and recognized gain/loss?
Title: Application Problem 10
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.3
Solution:
a. Amount realized $39,000
Less: Adjusted basis ( 52,000)
Realized loss ($13,000)
Because Evan owns more than 50% of Stan Corporation, they are considered related parties under §267. Realized losses from the sale or exchange of property between certain related parties are disallowed and not recognized. Evan’s recognized loss is $0. Stan Corporation’s basis in the land purchased is its purchase price of $39,000.
b. The loss of $13,000 from the sale from Evan to Stan Corporation is disallowed and not recognized by Evan. This creates a right of offset of $13,000 that Stan Corporation can use to reduce any realized gain when he sells the property to zero. When Stan Corporation sells the land, it has a realized gain of $26,000:
Amount realized
$65,000
Less: Adjusted basis (39,000)
Realized gain $26,000
Stan Corporation’s gain is reduced by the right of offset to $13,000 ($26,000 $13,000; see calculation in part a). Therefore, Stan Corporation’s recognized gain is $13,000.
c. The loss of $13,000 from the sale from Evan to Stan Corporation is disallowed and not recognized by Evan. This creates a right of offset of $13,000 that Stan Corporation can use to reduce any realized gain when it sells the property to zero. When Stan Corporation sells the land, it has a realized gain of $6,000:
Amount realized $45,000
Less: Adjusted basis (39,000)
Realized gain $ 6,000
Stan Corporation’s gain is reduced by the right of offset, but only to the extent of Stan Corporation’s realized gain of $6,000. The right of offset cannot create or increase a loss. Stan Corporation’s recognized gain is $0. The remaining right of offset of $7,000 ($13,000 $6,000) is gone forever.
d. The loss of $13,000 from the sale from Evan to Stan Corporation is disallowed and not recognized by Evan. This creates a right of offset of $13,000 that Stan Corporation can use to reduce any realized gain when it sells the property to zero. When Stan Corporation sells the land, it has a realized loss of $4,000:
Amount realized $35,000
Less: Adjusted basis (39,000)
Realized loss ($4,000)
The right of offset cannot create or increase a loss so none of it can be used. Stan Corporation’s recognized loss is $4,000. The $13,000 right of offset is gone forever.
Time On Task: 10 minutes
11. Classify each of the following assets as realty, personalty (tangible), personalty (intangible asset), or natural resource.
a. Extracted coal
b. Covenant not to compete
c. Warehouse used to store chemicals
d. Trademark used to sell a product
e. Dump truck used at a construction site
f. Printer used in an office
Title: Application Problem 11
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1 3
Solution:
a. Natural resource
b. Personalty (intangible asset)
c. Realty
d. Personalty (intangible asset)
e. Personalty (tangible)
f. Personalty (tangible)
Time On Task: 6 minutes
12. Classify each of the following assets as ordinary, Section 1231, or capital.
a. Notes receivable
b. One parcel of land held for investment
c. Automobile used 100% for business and held for three years
d. 1967 Ford Mustang owned for personal pleasure
e. Desk and chair used in business and sold after three months
f. Land used as a playground for a day care center
Title: Application Problem 12
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Knowledge
Section Reference 1: 1 3
Solution:
a. Ordinary
b. Capital
c. Section 1231
d. Capital
e. Ordinary
f. Section 1231
Time On Task: 6 minutes
13. Sven Inc. sold several business assets in the current year. The sales resulted in Section 1231 gains of $12,000 and Section 1231 losses of $15,000. What is the character of the Section 1231 gains and losses?
Title: Application Problem 13
Difficulty: Easy
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
The $12,000 Section 1231 gain is netted with the $15,000 Section 1231 loss. The net Section 1231 loss of $3,000 is ordinary.
Time On Task: 3 minutes
14. Boris is the sole owner of a single-member LLC that reports its tax items on Schedule C. The LLC had several transactions during the year.
• Land held for investment for 13 months and sold at a gain of $45,000
• Inventory used in the LLC and sold for a loss of $23,000
• Casualty loss from a fire in the warehouse of $55,000
• Parking lot adjacent to the business sold at a gain of $20,000 after being held for more than one year
Determine the tax consequences of these transactions. Assume that the LLC had no prior Section 1231 losses in previous years and no other sales of Section 1231 assets this year.
Title: Application Problem 14
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
The $45,000 gain from the land held for investment is a long-term capital gain because the land is an investment asset which is a capital asset.
The loss from the inventory of $23,000 is an ordinary loss because inventory is an ordinary asset.
The loss from the casualty is a $55,000 Section 1231 loss because the warehouse is a Section 1231 asset.
The gain from the sale of the parking lot of $20,000 is a Section 1231 gain. Because land is not depreciable, there is no depreciation recapture.
The $55,000 Section 1231 loss and the $20,000 Section 1231 gain are netted to produce a net Section 1231 loss. This loss is treated as an ordinary loss. The LLC also has an ordinary loss
from the inventory of $23,000, so its total ordinary loss is $58,000 ($23,000 + $35,000). The LLC also has a long-term capital gain of $45,000.
Time On Task: 5 minutes
15. Daisy Company had several pieces of land that it sold in the current year:
Land
Land #1 used in its business
Land #2 used in its business
What are the tax consequences of the asset sales? Assume that Daisy Company does not have any net Section 1231 losses in prior years and that these are all the Section 1231 transactions for this year.
Title: Application Problem 15
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Land #1 used in her business
Land #2 used in her business
Land held for investment is always a capital asset.
LT Capital gain
($ 5,000) ST Ordinary loss
$ 7,000 LT Section 1231 gain
Land used in a trade or business but held short-term is an ordinary asset. Therefore, the loss is ordinary.
The Section 1231 gain would be considered a long-term capital gain because there are no net Section 1231 losses from previous years.
Time On Task: 8 minutes
16. Li Company started its ice cream parlor in Year 1. In Year 4, Li sold one business-use asset for a Section 1231 gain of $5,000 and sold another business-use asset for a Section 1231 loss of $2,200. If Li Company had a net Section 1231 loss of $1,000 in Year 3, what is the amount and character of the assets sold in Year 4?
Title: Application Problem 16
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Li Company has a net Section 1231 gain of $2,800 ($5,000 $2,200) in Year 4. Because of the five-year lookback rule, Li must treat the Section 1231 gain in Year 4 as ordinary to the extent of the unrecaptured Section 1231 loss in Year 3. Therefore, Li Company has ordinary income of $1,000 and a long-term capital gain of $1,800.
Time On Task: 5 minutes
17. Rhys Inc. sold various business-use assets in Year 10 resulting in a net Section 1231 gain of $7,000. Rhys Inc. had the following net Section 1231 gains and losses in the previous years:
Year 4 ($2,000)
Year 5 ($1,500)
Year 6 $2,500
Year 7 $ 800
Year 8 ($4,500)
Year 9 $3,000
How is the Year 10 net Section 1231 gain of $7,000 treated?
Title: Application Problem 17
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Because Rhys Inc. has a net Section 1231 gain in Year 10, it must look back for any unrecaptured net Section 1231 losses that were treated as ordinary in the previous five years.
Year 4 had a net Section 1231 loss of $2,000 that would have been treated as ordinary, and year 5 had the same for $1,500.
In Year 6, Rhys Inc. would have treated the entire $2,500 Section 1231 gain as ordinary due to the unrecaptured loss of $2,000 from Year 4 and $500 in Year 5. There is $1,000 of remaining unrecaptured losses from Year 5.
In Year 7, the net Section 1231 gain of $800 would also have been treated as ordinary due to the remaining $1,000 of unrecaptured losses from Year 5. This leaves $200 of unrecaptured loss from Year 5 to be dealt with for the next four years.
In Year 8, the $4,500 of net Section 1231 losses would have been treated as ordinary.
In Year 9, the net Section 1231 gain of $3,000 would have been ordinary due to the unrecaptured losses of $200 from Year 5 and $2,800 from Year 8. This leaves $1,700 of unrecaptured loss from Year 8 to be dealt with in Year 10.
In Year 10, the net Section 1231 gain of $7,000 would be considered $1,700 ordinary income due to the unrecaptured loss of $1,700 from Year 8 and $5,300 capital gain.
Year 4: $2,000 Loss
Year 5: $1,500 Loss
Year 6: $2,500 Gain
Year 7: $ 800 Gain
Year 8: $4,500 Loss
Year 9: $3,000 Gain
Year 10: $7,000 Gain
Time On Task: 12 minutes
$2,000
$1,500
$4,500
$2,500
Recaptured by $2,000 loss from Year 4
Recaptured by $500 loss from Year 5
$800
Recaptured by $800 loss from Year 5
$3,000
Recaptured by $200 loss from Year 5
Recaptured by $2,800 loss from Year 8
$1,700
Recaptured by $1,700 loss from Year 8
$5,300
18. Sandra Company sold land that it used in its business for $125,000 in the current year. Sandra Company purchased the land several years ago for $138,000.
a. What is the amount and character of Sandra’s recognized gain/loss?
b. What if Sandra Company sold the asset for $150,000? Assume it did not have any prior net Section 1231 losses in the past five years and that there were no other Section 1231 transactions this year.
Title: Application Problem 18
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
a.
Amount realized $125,000 Less: Adjusted basis ( 138,000)
Recognized loss ($ 13,000)
The land was used in a trade or business and held long-term so the net Section 1231 loss would be recognized as an ordinary loss.
b.
Amount realized
$150,000
Less: Adjusted basis (138,000)
Recognized gain $ 12,000
The land was used in a trade or business and held long-term so the gain would be recognized as a Section 1231 gain. Because there were no other Section 1231 transactions this year, the net $12,000 Section 1231 gain is treated as a long-term capital gain. Section 1250 recapture does not apply because land is not depreciable. The lookback does not apply because there have been no Section 1231 losses in the previous five years.
Time On Task: 8 minutes
19. Sasha Inc. owns business-use equipment with an initial purchase price of $50,000. The asset’s accumulated depreciation is $30,000. Assume that Sasha Inc. sells the equipment for $25,000 and that its tax rate is 21%.
a. Compute Sasha Inc.’s tax gain or loss on the sale and the character of the gain or loss.
b. Compute Sasha Inc.’s after-tax cash flow from the sale.
Title: Application Problem 19
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
a.
Amount realized
$25,000
Less: Adjusted basis ( 20,000) ($50,000 Cost $30,000 Depreciation) Tax gain $ 5,000
Section 1245 recapture = Lesser of: Recognized gain of $5,000, or depreciation taken of $30,000. Sasha Inc. recognizes $5,000 of ordinary income.
b. The $5,000 of recapture income is taxed at the corporation’s tax rate of 21%. The tax that is due is $1,050 ($5,000 21%).
Cash received from sale $25,000
Less: Tax cost ( 1,050)
After tax cash flow $23,950
Time On Task: 8 minutes
20. Bohai owns Dig Deep Company (DDC), specializing in manufacturing colonoscopy equipment. In the current year, DDC sold a machine for $28,000. DDC purchased the machine in 2021 for $38,000 and deducted depreciation expense of $23,000.
a. What is the amount and character of the gain/loss?
b. What if the machine was sold for $49,000?
c. What if the machine was sold for $12,000?
Title: Application Problem 20
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1 4
Solution:
a.
Amount realized
$28,000
Less: Adjusted basis ( 15,000) ($38,000 cost $23,000 depreciation)
Recognized gain
$13,000
Section 1245 recapture = Lesser of: Recognized gain
$13,000 or Depreciation taken $23,000
All the $13,000 recognized gain will be characterized as ordinary income under the Section 1245 recapture provision.
b.
Amount realized
$49,000
Less: Adjusted basis (15,000)
Recognized gain
$34,000
Section 1245 recapture = Lesser of: Recognized gain
$34,000 or Depreciation taken $23,000
Of the $34,000 recognized gain, $23,000 is characterized as ordinary income to the extent of the accumulated depreciation taken and the remaining $11,000 is a Section 1231 gain.
c.
Amount realized
$12,000
Less: Adjusted basis ( 15,000)
Recognized loss ($ 3,000) (Section 1231 loss)
Section 1245 recapture does not apply to losses. The $3,000 recognized loss would be characterized as a Section 1231 loss. If this was the only asset sold during the current year, then the loss would be an ordinary loss.
Time On Task: 12 minutes
21. MaryAnn Company purchased Tanger Corporation five years ago for $780,000. As part of the purchase, MaryAnn Company acquired two patents, which had a value of $50,000. In the current year, the company sells both patents for $65,000. Total amortization claimed on the patents through the date of sale was $16,800. What are the tax consequences of this sale?
Title: Application Problem 21
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Amount realized
$65,000
Less: Adjusted basis (33,200) ($50,000 cost less $16,800 accumulated amortization)
Recognized gain $31,800
A patent purchased as part of the acquisition of a business, rather than created by the owner, is a Section 1245 asset, so Section 1245 recapture applies. Section 1245 recapture is $16,800, the lesser of:
Recognized gain
$31,800 or Amortization taken $16,800
The remaining gain of $15,000 is a Section 1231 gain because the asset is used in a trade or business and was owned for more than one year.
Time On Task: 8 minutes
22. Daisy LLC has owned an apartment building since 1985, which it purchased for $232,000. Daisy LLC sold the apartment building in 1989 for $248,000. Accumulated depreciation as of the date of sale was $34,000, of which $6,000 was in excess of straight-line depreciation. How much of the gain is considered ordinary income?
Title: Application Problem 22
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Amount realized $248,000
Less: Adjusted basis (198,000) ($232,000 cost $34,000 accumulated depreciation)
Recognized gain $ 50,000
The apartment building is realty, and subject to Section 1250 recapture. Section 1250 recapture is the lesser of:
Recognized gain
$50,000 or Accelerated depreciation in excess of straight line $ 6,000
Daisy LLC will have ordinary income of $6,000, $28,000 of unrecaptured Section 1250 gain, and Section 1231 gain of $16,000.
Recognized gain
$50,000
Section 1250 recapture
Excess depreciation: $6,000
Time On Task: 8 minutes
Unrecaptured Section 1250 gain Section 1231 gain
Straight-line depreciation: $28,000
Remaining gain: $16,000
23. Eric LLC purchased a commercial building five years ago for $365,000. In the current year, Eric LLC sold the building for $100,000 cash and the buyer’s assumption of Eric’s debt on the building of $300,000. Through the date of sale, Eric LLC deducted $47,000 straight-line depreciation on the building. Compute Eric LLC’s recognized gain on the sale and the character of the gain.
Title: Application Problem 23
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Less: Adjusted basis:
$365,000
Less: Accumulated depreciation ( 47,000)
Adjusted basis (318,000)
Realized and recognized gain
$ 82,000
Eric LLC deducted straight line depreciation and therefore, has no Section 1250 recapture. The unrecaptured 25% gain is $47,000 and $35,000 is a Section 1231 gain. If this is the only Section 1231 asset sold this year, the $35,000 gain would be a long-term capital gain.
Section 1250 recapture
Excess depreciation:
$0
Time On Task: 8 minutes
Recognized gain
$82,000
Unrecaptured Section 1250 gain
Straight-line depreciation: $47,000
Section 1231 gain
Remaining gain: $35,000
24. Delgado Corporation purchased an apartment building on August 3, 2021, for $980,000 and sold the building on March 9, 2025, for $1,300,000. Delgado deducted straight-line depreciation of $127,689 for years 2021–2025. Determine the recognized gain and its character.
Title: Application Problem 24
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Step 1. First, we calculate the recognized gain or loss from the disposition:
Amount realized
$1,300,000
Less: Adjusted basis ( 852,311) ($980,000 $127,689)
Recognized gain $ 447,689
Step 2. Next, we determine if the asset sold is a Section 1250 asset. Delgado sold a depreciable building held for more than one year, so this is a Section 1250 asset.
Step 3. Now we calculate any excess depreciation, as follows:
Depreciation claimed
$127,689
Less: Straight-line depreciation (127,689)
Excess depreciation $ 0
Step 4. Next, we determine the Section 1250 recapture, which is the lesser of:
• The recognized gain ($447,689), or
• The excess depreciation ($0)
The lesser amount is $0, so this is the Section 1250 recapture.
Step 5. The remaining gain is next taxed as Section 291 recapture and is treated as ordinary income, in addition to any Section 1250 recapture. If the building was Section 1245 property,
the Section 1245 recapture would be $127,689, which is the lower of the depreciation claimed of $127,689 or the recognized gain of $447,689. The Section 291 recapture is computed as follows:
Section 1245 recapture IF the property had been Section 1245 property
$127,689
Less: Actual Section 1250 recapture 0
Excess Amount
$127,689 × 20% × 20%
Section 291 recapture $ 25,538
Step 6.
Finally, whatever gain from the disposition that remains (if any) is considered a Section 1231 gain, because the asset was used in a trade or business and was owned for more than a year. It can be calculated as follows:
Recognized gain
$447,689
Less: Section 1250 recapture ( 0)
Less: Section 291 recapture ( 25,538)
Section 1231 gain
$422,151
25. Upon her death, Latif’s grandmother bequeathed him the apartment building that she had rented out for the last 12 years. He does not want the hassle of maintaining the building, so he intends to sell the building right away. What are his tax consequences based on the following information?
• Fair market value as of the date of death was $625,000.
• Original cost was $400,000.
• Straight-line depreciation taken was $175,000 through the date of sale.
• Latif sells the building for $650,000.
Title: Application Problem 25
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Latif will not recognize any taxable income on the receipt of the inheritance, but he will have a taxable gain when he sells the apartment building. Because Latif inherited the apartment building from his grandmother, his basis in the building is the fair market value as of the date of death. His gain on the sale will be:
Amount realized $650,000
Less: Adjusted basis (625,000)
Recognized gain $ 25,000
The depreciation recapture potential does not carryover from the decedent to the beneficiary for assets received due to death. The depreciation recapture potential is eliminated at the death of the owner of the property. Therefore, the $25,000 gain is a Section 1231 gain.
Time On Task: 6 minutes
26. Susan owns a floral shop as a sole proprietorship and has net earnings of $100,000 on Schedule C. Susan is allowed a self-employment tax deduction for AGI of $7,065 ($100,000 × 0.9235 × 15.3% × 50%). What is her qualified business income?
Title: Application Problem 26
Difficulty: Easy
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
Susan’s qualified business income is $92,935 ($100,000 – $7,065). Susan reduces her QBI by one half of the self-employment tax.
Time On Task: 2 minutes
27. Roger, a single taxpayer, owns and operates a video game store. He does not have any employees and reported qualified business income of $125,000 through a sole proprietorship in 2025. Roger has AGI of $155,000, including $2,000 interest income, has no itemized deductions, and claimed the standard deduction of $15,000 on his 2025 Form 1040. His modified taxable income is $140,000 ($155,000 − $15,000). What is Roger’s QBI deduction?
Title: Application Problem 27
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
Roger’s QBI deduction is $25,000, the lesser of:
• 20% QBI = 20% $125,000 = $25,000, or
• 20% modified taxable income = 20% $140,000 = 28,000
Time On Task: 5 minutes
28. Kate, a single taxpayer, owns and operates an ice cream shop. She does not have any employees and reported qualified business income of $125,000 through a sole proprietorship in 2025. Kate has AGI of $155,000, including $20,000 of net capital gain, has no itemized deductions, and claimed the standard deduction of $15,000 on her 2025 Form 1040. Her modified taxable income is $120,000 ($155,000 − $15,000 − $20,000). What is Kate’s QBI deduction?
Title: Application Problem 28
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
Kate’s QBI deduction is $24,080, the lesser of:
• 20% QBI = 20% $125,000 = $25,000, or
• 20% modified taxable income = 20% $120,000 = $24,000
Time On Task: 5 minutes
29. Jaewoo is a CPA and operates his own CPA firm as a single-member LLC. His qualified business income from his accounting firm was $555,000 for 2025. Jaewoo paid wages of $162,000 this year, and the unadjusted basis of the property used in the LLC was $400,000. Jaewoo is married, and the taxable income before the QBI deduction is $500,000 for him and his spouse. What is Jaewoo’s QBI deduction?
Title: Application Problem 29
Difficulty: Medium
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
Jaewoo is not entitled to a QBI deduction in 2025 because his accounting firm is a specified service business and he and his spouse’s taxable income before the QBI deduction ($500,000) is greater than the $494,600 threshold for 2025.
Time On Task: 4 minutes
30. Lexi, a single taxpayer, owns and operates a computer repair shop. She pays one employee $15,000 in wages and has no qualified property. Lexi reported qualified business income through a sole proprietorship of $145,000 in 2025. She has AGI of $285,000, has no itemized deductions, and claimed the standard deduction of $15,000 on her 2025 Form 1040. Her modified taxable income is $270,000 ($285,000 − $15,000).
a. What is Lexi’s QBI deduction?
b. Assume Lexi has machinery and equipment with an unadjusted basis of $160,000. What is her QBI deduction?
Title: Application Problem 30
Difficulty: Hard
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
a. Because Lexi’s modified taxable income of $270,000 exceeds the $197,300 phase in threshold by more than $50,000, the wage/property limit fully applies and is the greater of:
• 50% of the wages paid with respect to the qualified trade or business (50% $15,000 = $7,500) or
• The sum of 25% of the wages paid in the trade or business plus 2.5% of any unadjusted basis immediately after the acquisition of all qualified property in the qualified trade or business.
(25% $15,000 = $3,750 + 2.5% of qualified property ($0) = $3,750)
Lexiʼs QBI deduction is then computed as the lower of:
• $145,000 × 20% = $29,000 or
• Wage/property limitation of $7,500.
Therefore, the QBI deduction is limited to $7,500.
The final QBI deduction cannot exceed 20% × modified taxable income ($270,000), or $54,000, which it does not.
b. Because Lexi’s modified taxable income of $270,000 exceeds the $197,300 phase in threshold by more than $50,000, the wage/property limit fully applies and is the greater of:
• 50% of the wages paid with respect to the qualified trade or business (50% $15,000 = $7,500), or
• The sum of 25% of the wages paid in the trade or business plus 2.5% of any unadjusted basis immediately after the acquisition of all qualified property in the qualified trade or business:
(25% $15,000 = $3,750 + $4,000 [2.5% of qualified property ($160,000)] = $7,750)
Lexiʼs QBI deduction is then computed as the lower of:
• $145,000 × 20% = $29,000 or
• Wage/property limitation of $7,750.
Therefore, the QBI deduction is limited to $7,750.
The final QBI deduction cannot exceed 20% × modified taxable income ($270,000), or $54,000, which it does not.
Time On Task: 12 minutes
31. Grant, a single taxpayer, has qualified business income and the following qualified business deductions after considering the wage limitation and the specified services limitation:
Sunshine LLC
Monsoon S Corporation
Landslide LLP
$25,000
$18,000
$15,000
Grant’s modified taxable income is $275,000, which includes net capital gains of $5,000 and qualified dividend income of $2,500. What is his allowable QBI deduction?
Title: Application Problem 31
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.4
Solution:
Unadjusted modified taxable income
$275,000
Net capital gains (5,000)
Qualified dividend income (2,500)
Adjusted modified taxable income
20%
Overall limitation
$267,500
20%
$ 53,500
Total QBI deduction is $58,000, but it is limited to $53,500.
Time on Task: 5 minutes
32. Alexander, a single taxpayer, owns and operates a fishing supply store. He pays one employee $15,000 in wages and has qualified property with an unadjusted basis of $160,000. He reported qualified business income through a sole proprietorship of $145,000 in 2025. Alexander has taxable income of $205,350, which is also his modified taxable income.
a. What is Alexander’s QBI deduction?
b. If Alexander were a tennis professional, what would be his QBI deduction?
c. If Alexander were a tennis professional with a taxable income of $250,000, what would be his QBI deduction?
Title: Application Problem 32
Difficulty: Hard
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Reporting
Standard 3: Bloom's || Application
Section Reference 1: 1.5
Solution:
a. We use the following process in this computation:
The specified service limitation does not apply to Alexander. The modified taxable income of Alexander falls into the range (2025) shown in Column 2 of Illustration 5.5:
Single > $197,300 and < $247,300
This means that the specified services and wage/property limitations potentially need to be phased in. Therefore, the QBI deduction is computed as follows:
1. No reduction is necessary for this step because Alexander is not operating a specified trade or business, so the applicable percentage is not used to reduce the amounts. 20% QBI = 20% $145,000 = $29,000; the QBI deduction is $29,000.
2. Because Alexander is in Column 2 and the wages/property limitation is reducing the deduction, the general QBI deduction is used, but reduced as follows, but not to exceed $7,750, which is the greater of:
• 50% Wages ($15,000) = $7,500 or
• 25% Wages ($15,000) + 2.5% Property ($160,000) = $7,750
a. Determine the excess between the general 20% QBI deduction of $29,000 in part 1 above and the full wages/property limitation of $7,750 in part 2 above: $21,250 ($29,000 $7,750).
b. Determine the reduction ratio: TaxableincomebeforetheQBIdeduction Applicablethreshold
$100,000(MFJ)or$50,000(Others)
$205,350 $197,300 $50,000 =16.1%
c. Determine the reduction in the wages/property limitation:
Excess $21,250 from part 2a reduction ratio 16.1% from part 2b = $3,421 (rounded)
3. Determine the final QBI deduction amount:
General 20% QBI deduction amount from 1 $29,000
Less: Reduction from 2c ( 3,421)
Final QBI deduction amount $25,579
4.The final QBI deduction cannot exceed 20% × modified taxable income ($205,350), or 41,070, which it does not.
b. The specified service limitation does apply now because Alexander is providing tennis lessons. The modified taxable income of Alexander falls into the range (2025) shown in Column 2 of Illustration 5.5:
Single > $197,300 and < $247,300
This means that the specified services and wage/property limitations potentially need to be phased in. Therefore, the QBI deduction is computed as follows:
1. If a taxpayer has qualified business income from a specified service trade or business, the taxpayer includes only the applicable percentage of QBI and adjusts the components of the wages/property limitation by the applicable percentage, as follows:
a. Determine the applicable percentage.
Applicable Percentage =
100%=TaxableincomebeforetheQBIdeduction Applicablethreshold $100,000(MFJ)or$50,000(Others)
In Alexander’s example, because he is in a specified service trade or business:
Applicablepercentage=100%
$205,350 $197,300 $50,000 =83.9%
b. Determine reduced components of QBI deduction. This can be determined as follows:
1. 20% QBI applicable percentage = 20% $145,000 83.9% = $24,331
2. But not in excess of the greater of:
• 50% wages ($15,000) applicable percentage = $7,500 83.9% = $6,293, or
• (25% × wages ($15,000)) + (2.5% × unadjusted basis of qualified property ($160,000)) 83.9% = $6,502
Note: If the specified service limitation does not apply, then the amounts do not have to be reduced by the applicable percentage.
The reduced QBI deduction is $24,331 after reduction for the specified services limitation. The reduced wage/property limitation is $6,502.
2. Because Alexander is in Column 2 of Illustration 5.5 and the wages/property limitation is reducing the deduction, the general QBI deduction is used, but is reduced as follows:
a. Determine the excess between the general 20% QBI deduction as reduced in 1 above ($24,331) and the full wages/property limitation ($6,502): $17,829 ($24,331 $6,502).
b. Determine Alexander’s reduction ratio: TaxableincomebeforetheQBIdeduction Applicablethreshold $100,000(MFJ)or$50,000(Others)
$205,350 $197,300 $50,000 =16.1%
c. Determine the reduction in Alexander’s wages/property limitation: Excess from part 2a ($17,829) reduction ratio (16.1%) = $2,870
3. Determine Alexander’s final QBI deduction amount:
General 20% QBI deduction amount from 1 $24,331
Less: Reduction from 2c ( 2,870)
Final QBI amount
$21,461
4. Finally, we check if Alexander’s final QBI deduction of $21,461 exceeds 20% × his modified taxable income ($205,350), or $41,070. Because it does not, Alexander’s final QBI amount remains $21,461.
c. If Alexander’s taxable income had been $250,000, he would not have been entitled to any QBI deduction because his modified taxable income exceeded the $247,300 threshold for single taxpayers, and he was in a specified service business.
Time On Task: 20 minutes
Tax Planning Problems
1. Benjamin owns equipment that is used 100% in his business with a fair market value of $11,000 and an adjusted basis of $15,000. He would like to sell the equipment and is looking for the best net after-tax cash flow. His tax rate is 35%. Would it be better to sell the equipment to his dad for $11,000 or his best friend for $10,000? Why?
Title: Tax Planning Problem 1
Difficulty: Hard
Learning Objective 1: 1.3
Standard 1: AACSB || Analytic
Standard 2: AICPA || PC: Decision Making
Standard 3: Bloom's || Analysis
Section Reference 1: 1.3
Solution:
If Benjamin sells the asset to his dad, he has a realized loss of $4,000 (Amount realized $11,000 – Adjusted basis $15,000). Benjamin and his dad are defined as related parties for purposes of the related party loss rule. Realized losses from the sale or exchange of property between certain
related parties are disallowed and not recognized. Therefore, Benjamin’s recognized loss is $0. He would have a net cash flow of:
Tax savings from loss 0
Net cash flow
$11,000
If Benjamin sells the equipment to his best friend, he has a realized loss of $5,000 (Amount realized $10,000 – Adjusted basis $15,000). Benjamin and his best friend are not related, so Benjamin can deduct the loss on his tax return. His recognized loss is $5,000. Benjamin’s tax savings from the loss will be the amount of the deduction multiplied by his marginal tax rate. Benjamin would have a net cash flow of:
Cash received
$10,000
Tax savings from loss 1,750 (Loss of $5,000 35% tax rate)
After tax net cash flow
$11,750
Ignoring the tax consequences, it appears that Benjamin should sell to his dad because he would receive $1,000 more for the equipment than if he sold to his friend. Once the tax consequences are considered, however, he is actually better off by $750 if he sells to his friend because the related party loss rules will not apply.
Time On Task: 10 minutes
2 Your client, Dwayne, owns Dwayne’s Manufacturing Company, and is looking to sell and replace his entire line of machinery and equipment, which is used to manufacture rugs. The machinery and equipment originally cost $500,000 and is fully depreciated. Dwayne expects to sell the machinery and equipment for its fair market value of $500,000. He has told you that he assumes he will recognize no gain because he is selling the machinery and equipment for the same amount he paid for them. Explain how the sale will be treated and why Congress created the depreciation recapture rules. Assume that Dwayne’s ordinary marginal tax rate is 37% and his LTCG rate is 20%.
Title: Tax Planning Problem 2
Difficulty: Difficult
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || PC: Decision Making
Standard 3: Bloom's || Analysis
Section Reference 1: 1.4
Solution:
Dwayne is mistaken. He will have a recognized gain because his adjusted basis in the machinery and equipment has been reduced to zero by the depreciation claimed.
Amount realized
Less: Adjusted basis
Cost $500,000
$500,000
Less: Accumulated depreciation (500,000) 0
Recognized gain
Section 1245 recapture = Lesser of:
Recognized gain
$500,000 or Depreciation taken
$500,000
$500,000
Section 1245 recapture recharacterizes the gain from Section 1231 gain to ordinary. If recapture didn’t apply, the $500,000 gain could be taxed as long-term capital gain taxed at a preferential rate of 20% resulting in a tax of $100,000 ($500,000 20%). With a marginal tax rate of 37%, the depreciation deduction benefit would have been $185,000 ($500,000 37%). Dwayne would have benefitted by $85,000($185,000 $100,000) simply due to the character difference of the depreciation deduction versus the long-term capital gain. Congress created the recapture rules, so the $500,000 gain is taxed as an ordinary gain at 37%. Dwayne’s tax liability upon sale equals the tax benefit from the depreciation deductions that have been taken over the years the machinery and equipment have been used: $185,000.
Time On Task: 10 minutes
3. Barret Company has been in business since 2014 and has never sold a Section 1231 asset. Barret has a net profit before asset sales of $350,000 this year. Barret has owned the following assets since inception of the business but is trying to decide if it is the right time to sell the assets before the end of the year.
What is the character of the gains/losses, and what is Barret’s profit after asset sales? Is there any advice you would give him with regard to the Section 1231 assets?
Title: Tax Planning Problem 3
Difficulty: Difficult
Learning Objective 1: 1.1, 3, 4
Standard 1: AACSB || Analytic
Standard 2: AICPA || PC: Decision Making
Standard 3: Bloom's || Analysis
Section Reference 1: 1.1, 3, 4
Solution:
(3)
(1) The furniture and computers were sold at a gain and subject to Section 1245 recapture. Section 1245 recapture is equal to the lesser of recognized gain or accumulated depreciation taken. Because the gain for both of these asset sales is less than the depreciation taken, all of the gain is subject to Section 1245 recapture and considered ordinary.
(2) The unrecaptured Section 1250 (25%) gain is $7,500. The unrecaptured Section 1250 gain is equal to the straight-line depreciation claimed.
(3) The Section 1231 gain is $25,000 ($32,500 total gain $7,500 unrecaptured Section 1250 gain).
Additional explanation:
• The artwork is a capital asset in Barret’s hands and the loss is a capital loss.
• The machinery is a Section 1231 asset and sold at a loss, so the Section 1245 recapture rules do not apply.
• The building is a Section 1231 asset but there would be no Section 1250 recapture because straight line deprecation would have been taken on this asset since it was purchased in 2012.
• The stock is a capital asset resulting in a long-term capital gain.
To compute Barrett’s net profit after asset sales, we need to separate the gains and losses based on their character:
Ordinary income and loss: Furniture
$7,000 Computers 1,500
Section 1231 gains and losses:
Building
$8,500
$25,000
Machinery ( 2,000)
$23,000
Because there is a net Section 1231 gain of $23,000, that is treated as a LTCG.
Capital gains and losses:
Building (25% gain)
$ 7,500
Section 1231 gain
Barrett’s net profit after assets sales is computed as:
Barret’s net profit before asset sales $350,000 Plus: Ordinary income
Plus: Net LTCG ($7,500 of this is 25% gain)
Barret’s profit after asset sales $414,000
For advice, if Barret does sell the building this year, he may want to delay selling the machinery until next year. The building has a $25,000 Section 1231 gain and the machinery has a $2,000 Section 1231 loss. If both are sold this year, the loss is reducing Section 1231 gain that is treated as LTCG that is taxed at preferential rates. If the loss is recognized next year, it may be able to offset ordinary income which is taxed at higher rates. The sale of the artwork also results in a capital loss that would reduce the capital gain from the sale of stock. This sale could be delayed until next year because the $2,000 loss is less than the $3,000 capital loss limit for individuals and could all be deducted next year.
Time On Task: 20 minutes
4. DeMarcus owns and operates a sporting goods store as a single member LLC. He is considering selling several assets (used in the business and held long-term) and would like to know the most advantageous tax result. These would be the only Section 1231 assets sold this year. Assume DeMarcus is in a 37% tax bracket and has never sold an asset in the past. The following information will help you decide the best course of action. Should Demarcus sell the assets this year or wait until next year?
Title: Tax Planning Problem 4
Difficulty: Difficult
Learning Objective 1: 1.1, 3, 4
Standard 1: AACSB || Analytic
Standard 2: AICPA || PC: Decision Making
Standard 3: Bloom's || Analysis
Section Reference 1: 1.1, 3, 4
Solution:
To properly advise DeMarcus, you must first calculate the character of the gain/loss if the assets are sold.
Building
$100,000 $75,000 $5,000
$70,000 $30,000 $5,000 25% gain
$25,000 Section 1231 gain
Land $ 25,000 $37,000 N/A $ 37,000 ($12,000) Section 1231 loss
If the two assets were sold in the same year, it would result in a net Section 1231 gain of $13,000 which would be treated as a long-term capital gain taxed at 20%. The $5,000 gain would be taxed at a maximum rate of 25%.
Unrecaptured Section 1250 (25%) gain tax
Section 1231 gain tax
Total
$1,250 ($5,000 25%)
$2,600 [($25,000 $12,000) 20%)]
$3,850
An alternative strategy is to sell the building in the current year and the land in the following year. The sale of the building would be treated as follows.
Unrecaptured Section 1250 (25%) gain tax
Section 1231 gain tax ($25,000 20%)
Total
$1,250
$5,000
$6,250
And the land sold in the following year would be treated as follows:
Section 1231 loss tax savings
$(4,440) ($12,000 37%)
The net result is a total tax for the two years of $1,810 ($6,250 $4,440).
It is more advantageous to sell the assets in two different years. Selling the building in the current year generates a tax, but the lookback rule does not apply because no Section 1231 assets have been previously sold. Thus, the LTCG rates apply. Selling the land in the following year allows DeMarcus to use the 37% ordinary rate on the Section 1231 ordinary loss resulting in a larger savings. DeMarcus will save a total of $2,040 ($3,850 $1,810) by selling the Section 1231 gain asset in the first year and selling the Section 1231 loss asset in the second year. Time On Task: 15 minutes
5 Sanjay has asked your advice on how to treat an asset sale that he will have in the near future. Sanjay is very close to his uncle, who is critically ill. His uncle has listed several assets in his will that Sanjay will inherit upon the uncle’s death. One of the assets is a warehouse that his uncle uses in his business and has owned for the last 10 years. Sanjay would like to know the tax consequences if the warehouse was gifted to him by his uncle or if he waits and receives it through inheritance. Calculate the gain, if any, and its character if Sanjay receives the gift today or if he waits until his uncle passes, based on the following information.
Fair market value today
Original cost
$500,000
$375,000
Straight-line depreciation claimed $ 96,000
Assume that the uncle dies, Sanjay sells the warehouse for $550,000, and the fair market value as of date of death is $500,000.
Title: Tax Planning Problem 5
Difficulty: Difficult
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || PC: Decision Making
Standard 3: Bloom's || Analysis
Section Reference 1: 1 4
Solution:
If received as a gift: Sanjay will not recognize any taxable income on the receipt of the gift, but he will have a taxable gain when he sells the warehouse. Sanjay’s basis in the warehouse is the same as the donor, his uncle.
Amount realized
$550,000
Less: Adjusted basis ( 279,000) (Cost $375,000 Depreciation $96,000)
Recognized gain
$271,000
The Section 1250 depreciation recapture potential is transferred with the property to the donee for a gift and will affect the character of the $271,000 gain. There is no Section 1250 recapture because straight-line depreciation was claimed. However, the unrecaptured Section 1250 (25%) gain applies to the extent of the straight-line depreciation of $96,000. The remaining gain of $175,000 is a Section 1231 gain.
If received through inheritance: Sanjay will not recognize any taxable income on the receipt of the inheritance, but he will have a taxable gain when he sells the warehouse. Sanjay’s basis is the fair market value as of the date of death.
Amount realized
$550,000
Less: Basis (FMV as of date of death) ( 500,000)
Recognized gain
$ 50,000
When the warehouse is sold, it does not have depreciation recapture potential, as the depreciation recapture is eliminated at the death of the owner of the property and the gain will be a Section 1231 gain. Recapture potential does not transfer to the beneficiary when an asset is transferred due to death.
You should advise Sanjay to tell his uncle to not gift the property at this time. Rather, he should bequeath it to Sanjay in his will.
Time On Task: 12 minutes
6. Candy Cane, single, owns and operates the following businesses in 2025. None of these are specified service businesses.
Treetop Decorations
Cookies $ 65,000 $ 0 $0
Candyʼs Snow Supplies ($ 45,000) $ 5,000 $0
Candy’s modified taxable income is $400,000. Can she ignore the loss from Candy’s Snow Supplies in calculating her QBI deduction?
Title: Tax Planning Problem 6
Difficulty: Hard
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || PC: Decision Making
Standard 3: Bloom's || Analysis
Section Reference 1: 1.5
Solution:
Candy must allocate the loss in proportion to the other businesses' positive QBI amounts.
Treetop Decorations Adjustment = $27,273 [$45,000 ($100,000/$165,000)]
Candy’s Cookies Adjustment = $17,727 [$45,000 ($65,000/$165,000)] Business
Candy’s combined QBI Deduction = $6,250 which is less than $80,000 ($400,000 modified taxable income 20%). Note that the wage limitation is applied separately to each QBI activity.
Time On Task: 8 minutes
Communication Problem
1. Decision on When to Sell Business-Use Assets Sylvia has owned her own beauty salon as a sole proprietorship in Alpharetta, Georgia, since 2017. The salon needs a makeover, and she is looking at selling her salon chairs, furniture, and pedicure basins. All of these assets have been held long-term. Sylvia has never sold any business assets in the past, and her current year AGI before the sale of assets is $150,000. Included in her AGI is a $10,000 short-term capital loss from the sale of stock that has been limited to $3,000. She would like your advice as to whether
the sale of these assets will help utilize her entire $10,000 loss. She provides you with the following information:
If Sylvia sells the assets at their fair market value (FMV), what will be the amount of recognized gain/loss and its character? Will the sale of assets help utilize her $10,000 short-term capital loss? Write a letter to Sylvia explaining your findings.
Title: Communication Problem: Decision When to Sell Business Use Assets
Difficulty: Medium
Learning Objective 1: 1.1, 3, 4
Standard 1: AACSB || Communication
Standard 2: AICPA || PC: Communication
Standard 3: Bloom's || Analysis
Section Reference 1: 1.1, 3, 4
Solution:
Hello Sylvia,
I have always enjoyed going to your salon for friendly and competent service. I am hoping to provide the same to you. You have asked for advice concerning the sale of some of your business assets to potentially purchase new assets and refresh your salon. Your goal is to utilize the shortterm capital loss of $10,000. Unfortunately, the sale will not help you in this regard. You need additional capital gains to offset the unused capital losses, but these sales would not generate capital gains. If you sell your assets, the tax results will be as follows:
You would have a net gain from the sale of the business assets, but the character of the gain will not help offset a short-term capital loss. Because you took depreciation on the assets and received an ordinary deduction from the depreciation taken, the gain on the sale of the assets will be recharacterized from capital to ordinary to the extent of the depreciation taken.
Asset Gain/loss Character
Chairs $ 6,000 All ordinary because the gain is less than the depreciation taken
Furniture
($2,000) Section 1231
Basins $ 4,000 $3,000 is ordinary because of the depreciation; $1,000 is Section 1231
Sales resulting in Section 1231 gains and losses must be netted against one another before the resulting character can be determined. You have a net Section 1231 loss of $1,000 ($1,000 gain from basins less $2,000 loss from furniture) which is treated as an ordinary loss.
Your new AGI would be determined as follows:
: Section 1231 loss ( 1,000)
I am sorry that I did not have better news for you. Please let me know if I can be of further assistance.
Sincerely,
Carnes & Youngberg, CPAs
Time On Task: 20 minutes
Ethics and Professional Responsibilities Problems
1. Underreported Income Anthony Johnson, who owns a local bar and works as its bartender, is a new client of yours and would like to meet to discuss his financial statements and tax return for the current year. He operates the bar as an S corporation and is the sole shareholder. Anthony indicates that business has been slow; he expects a loss and feels he shouldn’t owe any taxes this year. While reviewing the manual business records and Anthony’s personal tax information, you see that there are very few cash receipts and no recording of tips. Anthony also has a large mortgage on his home, generating $28,000 in mortgage interest expense, and $25,000 in property taxes. You continue to dig through previous tax returns for the S corporation and Anthony’s Form 1040 and notice very little income for the last five years. You wonder how Anthony can afford such a nice home. During your next meeting, you ask him about the cash receipts, the tips, and his large mortgage and property taxes. Anthony is vague and says no one in his line of work reports all the cash receipts and tips. What should you do?
In addition to the chapter content, see Statements on Standards for Tax Services at www.aicpa- cima.com/resources/landing/statements-on-standards-for-tax-services, Circular 230 at www.irs.gov/tax-professionals/office-of-professional-responsibility-and-circular-230, and Chapter 2, LO4, Tax Professional Responsibilities.
Title: Ethics and Professional Responsibilities Problem: Underreported Income Difficulty: Medium
Learning Objective 1: 1.1
Standard 1: AACSB || Ethics
Standard 2: AICPA || PC: Ethical Conduct
Standard 3: Bloom's || Evaluation
Section Reference 1: 1.1
Solution:
Although a tax practitioner can rely on his client’s records when preparing the tax return, under Statement on Standards for Tax Services No. 2.3.2, Reliance on Information from Others, member should not ignore the implications of information furnished and should make reasonable inquiries if the information furnished appears to be incorrect, incomplete, or inconsistent either on its face or on the basis of other facts known to the member. Also, Circular 230, §10.22 Diligence as to accuracy, states a practitioner must exercise due diligence in preparing or assisting in the preparation of, approving, and filing tax returns, documents, affidavits, and other papers relating to Internal Revenue Service matters. Because it is clear that Anthony is not reporting all the cash receipts and tips, you must inform him that under IRC §61(a) reportable income is from all sources, and he must report the cash receipts on his S corporation and the tips on his W-2 wages. If Anthony refuses to comply, the tax practitioner should disengage and not prepare his tax returns. The tax practitioner should inform Anthony of the liability, penalties, and interest that would be assessed by the Internal Revenue Service. The practitioner should also remember preparer penalties and the possible negative impact on their reputation and professional licensing if they prepare returns for a tax client where there is substantial understatement of income and where the practitioner as a professional had reasonable knowledge of the underreporting.
Time On Task: 10 minutes
2. Reliance on Workpapers of a Third Party Your CPA firm, Carnes and Youngberg, has been hired to help a new client in resolving a dispute with the IRS for a prior year’s tax return. Carnes and Youngberg did not prepare the return, and your client did not have the best record keeping in the past. When reviewing the correspondence from the IRS, as well as Form 4797, Form 8949, and Schedule D, you notice some discrepancies on the forms compared to the workpapers that your client did provide. You realize that the workpapers and tax return were prepared by Frank Fishy, an attorney who also prepares tax returns. With a little digging, you find out that Frank Fishy has been disbarred from practicing before the IRS, and this concerns you. May you ask for assistance from Frank or rely on his workpapers? What is your responsibility regarding representing the client before the IRS?
In addition to the chapter content, see Statements on Standards for Tax Services at www.aicpa-cima.com/resources/landing/statements-on-standards-for-tax-services, Circular 230 at www.irs.gov/tax-professionals/office-of-professional-responsibility-and-circular-230, and Chapter 2 LO4, Tax Professional Responsibilities.
Title: Ethics and Professional Responsibilities Problem: Reliance on Workpapers of a Third Party
Difficulty: Medium
Learning Objective 1: 1.1
Standard 1: AACSB || Ethics
Standard 2: AICPA || PC: Ethical Conduct
Standard 3: Bloom's || Evaluation
Section Reference 1: 1.1
Solution:
Circular 230 §10.24 provides that a practitioner may not knowingly, directly or indirectly, accept assistance from any person who is under disbarment or suspension from practice before the IRS if the assistance relates to a matter or matters constituting practice before the Internal Revenue Service. Under §10.22, a practitioner must exercise due diligence in preparing or assisting in the preparation of, approving, and filing tax returns, documents, affidavits, and other papers relating to Internal Revenue Service matters. You must try to find an accurate outside source to help verify the workpaper’s numbers such as the broker who sold the assets, or any original purchase invoices to determine the assets original cost.
Time On Task: 10 minutes
Research Problem
1. Timely Filing of Tax Return Collins Inc. is a calendar year-end C corporation owned 100% by Chase Collins. Chase was out of the country on the due date for filing the 2025 tax return, so he asked his CPA to file an extension. The CPA properly completed the extension form and queued it up to file electronically with her software. Unfortunately, the CPA never hit the submit button and did not realize the error until October 15 when she wanted to electronically file the tax return at the extension due date. As a result, the Collins Inc. tax return was not timely filed, and the IRS assessed a late filing penalty of $83,650 against the corporation. Collins Inc. paid the penalty and have filed a case in District Court to have the penalty abated. Chase Collins states that he relied on his CPA to properly file the extension, and the corporation should not be assessed the penalty. Conduct research to determine if Collins Inc. has reasonable cause to have the penalty abated.
Title: Research Problem: Timely Filing of Tax Return
Difficulty: Medium
Learning Objective 1: 1.2
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Research Standard 3: Bloom's || Analysis
Section Reference 1: 1.2
Solution:
The taxpayer is assessed a penalty if it fails to file a return, files it late, and/or fails to pay the tax due. These penalties do not apply if the taxpayer can prove a reasonable cause for the error. One question concerning reasonable cause is whether the taxpayer meets the reasonable-cause requirement if the corporation relied on the adviser to file the return or accepted the adviser's incorrect filing date?
The Supreme Court considered this question in Boyle (469 U.S. at 246) and the District Court decided this exact issue in Intress vs US. (404 F.Supp.3d 1174 (2019) In Boyle, the taxpayer relied on the tax advisor to file an estate tax return, and the return was accidentally filed late. In Intress, a similar fact pattern as Collins Inc. was presented and the court found the penalty applied. The Supreme Court in Boyle ruled against the taxpayer, stating that the return due date is a fixed date. Therefore, it is a bright line, and a taxpayer cannot reasonably fail to file on time by relying on an adviser to handle the paperwork. In Intress, the taxpayer argued that the Boyle case cannot be considered because e-filing did not exist at that time. In today’s environment, the
taxpayer relies on a CPA to e-file the extension and return because the CPA has the proper software. The district court, however, found that Boyle applied to Intress because, like the taxpayer in Boyle, they were not required to use tax preparation services.
Based on these decisions, it is reasonable to assume that the taxpayer will not be able to prove reasonable cause based on reliance on a tax adviser if the return was not filed on time or the liability was not paid. The IRS will penalize the taxpayer in these situations. Therefore, Collins Inc. will not have reasonable cause and will not be able to recoup the penalty.
Time On Task: 25 minutes
2. Potential Depreciation Recapture Grandma Sally died on November 5 of the current year. In her will, she left her granddaughter, Sienna, several assets that Sally had used in her farming business, including:
FMV at date of death
Silo
Farming equipment
$335,000
$ 80,000
Sally’s basis in the asset
$145,000
$110,000
Sienna would like to sell the assets immediately for their FMV. Does the depreciation recapture provision apply to either Sally or Sienna?
Title: Research Problem: Potential Depreciation Recapture?
Difficulty: Medium
Learning Objective 1: 1.4
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Research Standard 3: Bloom's || Analysis
Section Reference 1: 1.4
Solution:
IRC §1014(a)(1) states that the basis of property acquired by a decedent is equal to the asset’s fair market value as of the date of death. And IRC §1245(b)(2) states that recapture does not apply to a transfer at death. Therefore, the recapture potential is eliminated at death and does not carry over to the person who inherits the property (Siena). Siena’s basis in the assets inherited are the fair market value at death.
Time On Task: 10 minutes
Excel Problems
1. Related-Party Sale Chike owns 100 shares of stock in Belvidere Corporation. He purchased the stock for $40,000 three years ago. Chike sells the shares to Naomi Inc. in the current year for $32,000, resulting in a realized loss of $8,000 to Chike. Chike owns 75% of Naomi Inc. Create an Excel spreadsheet to indicate the recognized gain if Naomi Inc. sells the stock to an outside third party for:
1. $42,000
2. $36,000
3. $30,000
Title: Excel Problem: Related-Party Sale
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Technology
Standard 2: AICPA || AC: Technology and Tools
Standard 3: Bloom's || Synthesis
Section Reference 1: 1 3
Solution:
The disallowed loss from a related-party sale creates a right of offset, which taxpayers can use to reduce a gain upon the ultimate sale of the property to an unrelated taxpayer. The right of offset cannot create a loss, nor can it make a loss greater. Once the related-party buyer sells the asset to a third party, the buyer permanently loses any unused right of offset.
1. Input:
2. Input:
Amount realized 30,000
Amount realized $ 30,000
Less: Adjusted basis ( 32,000)
Realized loss ($ 2,000)
Less: Right of offset ( 0)
Recognized loss ($ 2,000)
Time On Task: 20 minutes
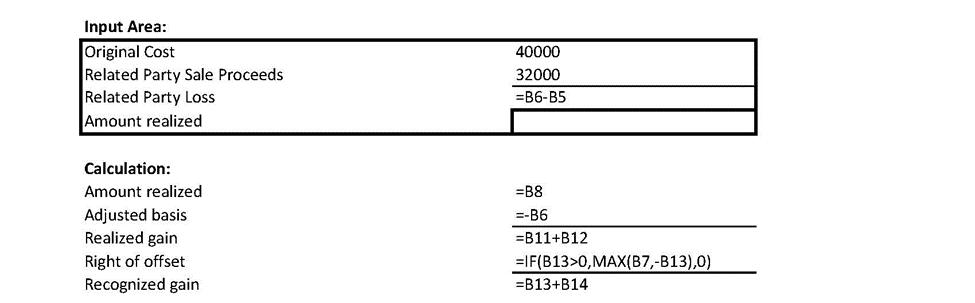
2. Lookback Rule Elonzo Corporation sold various business-use assets in Year 20, resulting in a net Section 1231 gain of $12,000. Year 14 was the first year of operations. Elonzo Corporation had the following net Section 1231 gains and losses in the previous years:
Year 14 $6,500
Year 15 ($2,000)
Year 16 ($4,500)
Year 17 $5,000
Year 18 ($2,500)
Year 19 ($1,000)
a. How is the Year 20 net Section 1231 gain of $12,000 treated?
b. How would your answer change if the Year 14 amount was ($6,500)?
c. Create an Excel spreadsheet that shows your results and that could also be used for the same question with different amounts.
Title: Excel Problem: Lookback Rule
Difficulty: Hard
Learning Objective 1: 1.4
Standard 1: AACSB || Technology
Standard 2: AICPA || AC: Technology and Tools
Standard 3: Bloom's || Synthesis
Section Reference 1: 1.4
Solution:
a. Because Elonzo Corporation has a net Section 1231 gain in Year 20, it must look back for any unrecaptured net Section 1231 losses that were treated as ordinary in the previous five years.
Year 14 had a net Section 1231 gain of $6,500 that would have been treated as long-term capital gain.
Year 15 had a net Section 1231 loss of $2,000 that would have been treated as an ordinary loss.
Year 16 had a net Section 1231 loss of $4,500 that also would have been ordinary.
In Year 17, Elonzo Corporation had a net Section 1231 gain of $5,000. It would have treated the entire $5,000 Section 1231 gain as ordinary due to the unrecaptured loss of $2,000 from Year 15 and $3,000 in Year 16. There is $1,500 of the remaining unrecaptured losses from Year 16.
In Year 18, the net Section 1231 loss of $2,500 would have been ordinary and in Year 19, the net 1231 loss of $1,000 would have been ordinary.
In Year 20, Elonzo Corporation had a net Section 1231 gain of $12,000. There is remaining unrecaptured losses from Year 16, 18, and 19 of $1,500, $2,500, and $1,000, respectively.
Therefore, in Year 20, $5,000 would be ordinary income and the remaining $7,000 would be long-term capital gain.
b. Because Elonzo Corporation has a net Section 1231 gain in Year 20, it must look back for any unrecaptured net Section 1231 losses that were treated as ordinary in the previous five years.
Years 14, 15, and 16 had a net Section 1231 loss of $6,500, $2,000, and $4,500 respectively, that would have been treated as an ordinary loss in each year.
In Year 17, Elonzo Corporation had a net Section 1231 gain of $5,000. It would have treated the entire $5,000 Section 1231 gain as ordinary due to the unrecaptured loss of $6,500 from Year 14. There is $1,500 of remaining unrecaptured losses from Year 14.
In Year 18, the net Section 1231 loss of $2,500 would have been ordinary and in Year 19, the net Section 1231 loss of $1,000 would have been ordinary.
In Year 20, Elonzo Corporation had a net Section 1231 gain of $12,000. There is remaining unrecaptured losses from Year 14, 15, and 16 of $1,500, $2,000, and $4,500, respectively. And there is remaining unrecaptured losses from Years 18 and 19 of $2,500 and $1,000, respectively. But the unrecaptured loss from Year 14 is expired. Therefore, total unrecaptured losses total $10,000.
Therefore, in Year 20, $10,000 would be ordinary income and the remaining $2,000 would be long-term capital gain.
Time On Task: 25 minutes
Input Area: Year Gain (Loss) Year 14 6,500 Year 15 (2,000) Year 16 (4,500) Year 17 5,000 Year 18 (2,500) Year 19 (1,000) Year 20 12,000
Calculation: Part a
Yr 14
Yr 15
=VLOOKUP(A16,$ A$6:$B$12,2) =IF(B16> 0,B16,0) =IF(B16< 0,B16,0) =D16 0
=VLOOKUP(A17,$ A$6:$B$12,2) =IF(B17> 0,B17,0) =IF(B17< 0,B17,0)
Yr 16 =VLOOKUP(A18,$ A$6:$B$12,2) =IF(B18> 0,B18,0) =IF(B18< 0,B18,0)
Yr 17 =VLOOKUP(A19,$ A$6:$B$12,2) =IF(B19> 0,B19,0) =IF(B19< 0,B19,0)
Yr 18 =VLOOKUP(A20,$ A$6:$B$12,2) =IF(B20> 0,B20,0) =IF(B20< 0,B20,0)
Yr 19 =VLOOKUP(A21,$ A$6:$B$12,2) =IF(B21> 0,B21,0) =IF(B21< 0,B21,0)
=IF(B17>=E16,0,E16+B 17)
=IF(B18>=E17,0,E17+B 18)
=IF(B19>=E18,0,E18+B 19)
=IF(B20>=E19,0,E19+B 20)
=IF(D17<0,0,MIN(B 17,-E16+F17))
=IF(D18<0,0,MIN(B 18,-E17+F18))
=IF(D19<0,0,MIN(B 19,-E18+F19))
=IF(D20<0,0,MIN(B 20,-E19+F20))
=IF(B16> G16,B16G16,0)
=IF(B17> G17,B17G17,0)
=IF(B18> G18,B18G18,0)
=IF(B19> G19,B19G19,0)
=IF(B20> G20,B20G20,0)
=IF(B21>=E20,0,E20+B 21) =IF(D21<0,0,MIN(B 21,-E20+F21)) =IF(B21> G21,B21G21,0)
Yr 20 =VLOOKUP(A22,$ A$6:$B$12,2) =IF(B22> 0,B22,0) =IF(B22< 0,B22,0) =IF(B22>=E21,0,E21+B 22) =MIN(SUM(D12:D16)+ SUM(C17:C21),0) =IF(D22<0,0,MIN(B 22,-E21+F22)) =IF(B22> G22,B22G22,0)
Calculation:
This problem is for 2025. The answer is reported on a 2024 Form 4797 because that was the most recent return available at the time of publication.
1. Sale of Assets Victor E. Husky (SSN: 123-45-6789) owns and operates Husky Ice Arena and Pro Shop as a sole proprietor. During 2025, the following transactions occurred:
1. A delivery truck used in the business was sold on January 2 for $3,500. The truck had been purchased on January 2, 2019, for $6,000. The asset was fully depreciated.
2. Unimproved land (which is considered a business-use asset) adjacent to the Ice Arena was sold for $15,000 on February 1. This land had been purchased on November 28, 2003, for $40,000.
3. Victor sold a rowing machine used by the hockey players at the ice arena on June 5 for $4,900. The rowing machine was purchased on July 29, 2016, for $5,200. The asset was fully depreciated.
4. Victor sold an apartment building on September 1 for $300,000. The rental property had been purchased on September 1, 2022, for $150,000. As of the date of the sale, the adjusted basis was $133,637.
5. A Zamboni used in the business was sold on October 10 for $85,000. The Zamboni had been purchased on October 10, 2023, for $100,000. As of the date of sale, the accumulated depreciation was $61,600.
6. Ice equipment used in the business was sold on October 14 for $5,000. The ice equipment had been purchased on October 16, 2022, for $35,000. As of the date of the sale, accumulated depreciation was $26,936.
Victor does not have any unrecovered Section 1231 lookback losses. Victor needs help completing his tax return in regard to these asset sales. Please complete Form 4797. The 2024 Form 4797 is used because it was the most recent form available at the time of publication.
Title: Tax Compliance and Reporting Problem: Sale of Assets
Difficulty: Medium
Learning Objective 1: 1.1, 3, 4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Measurement Analysis and Interpretation
Standard 3: Bloom's || Analysis
Section Reference 1: 1.1, 3, 4
Solution:
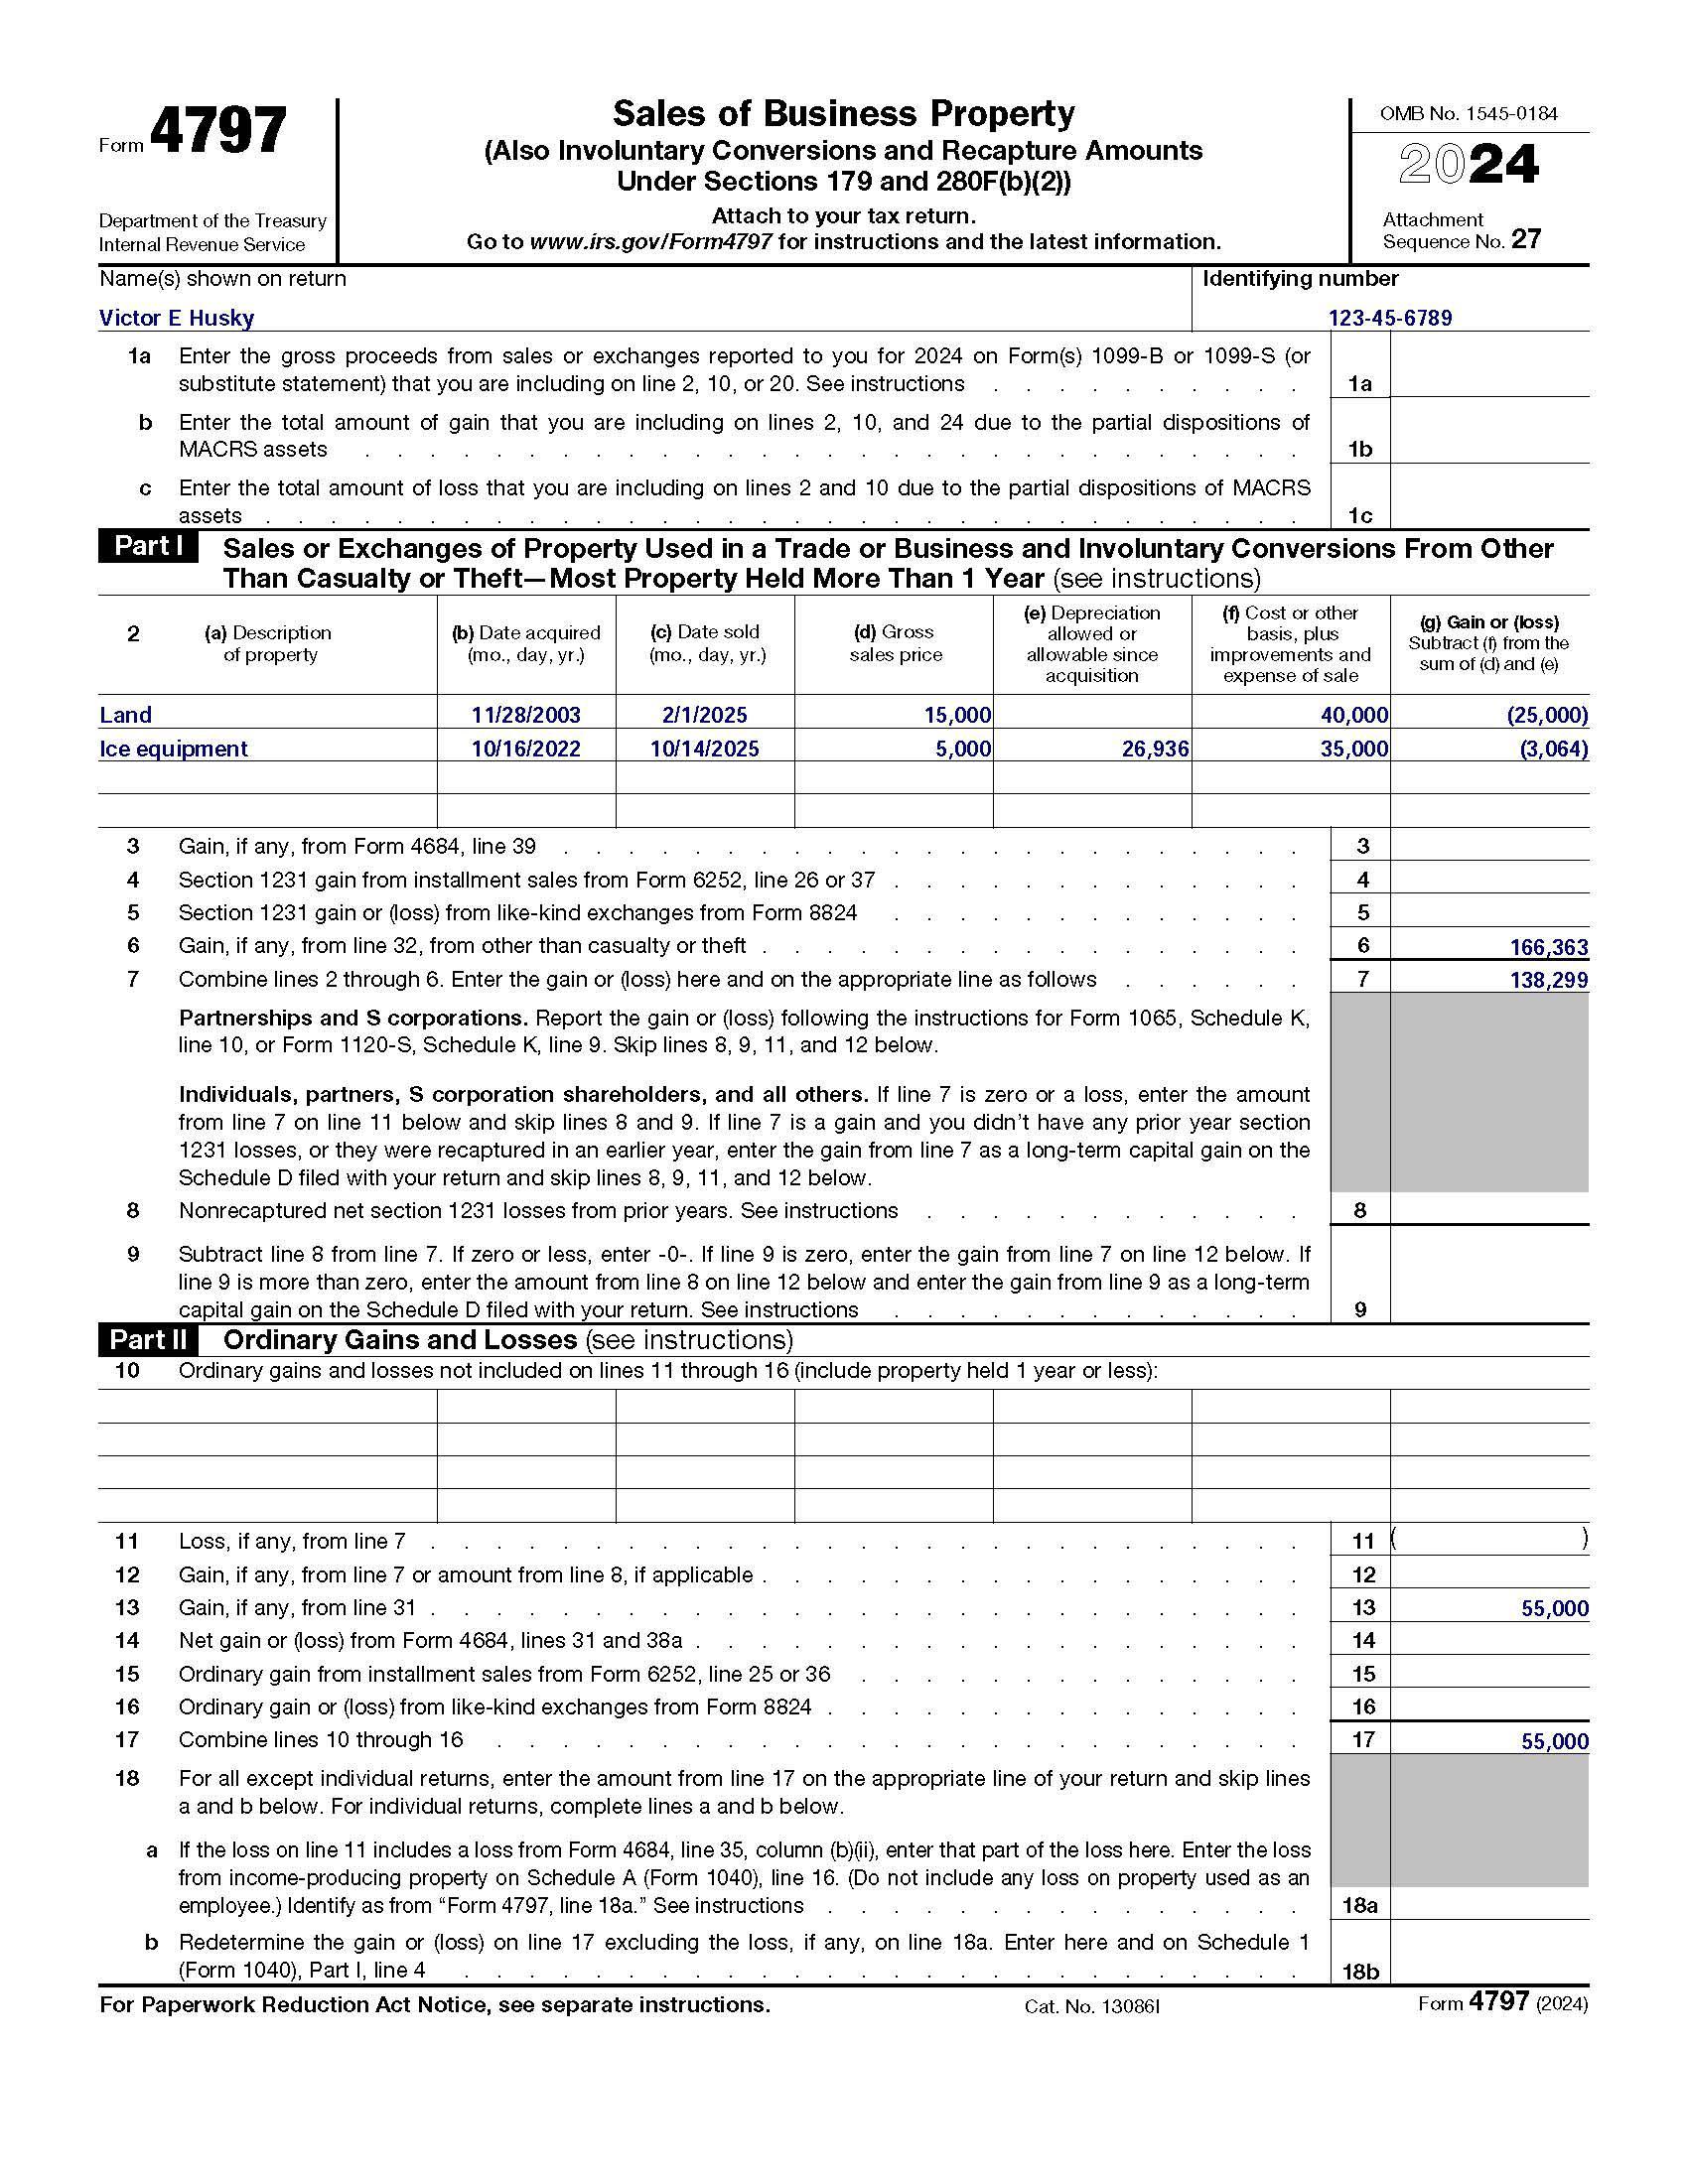
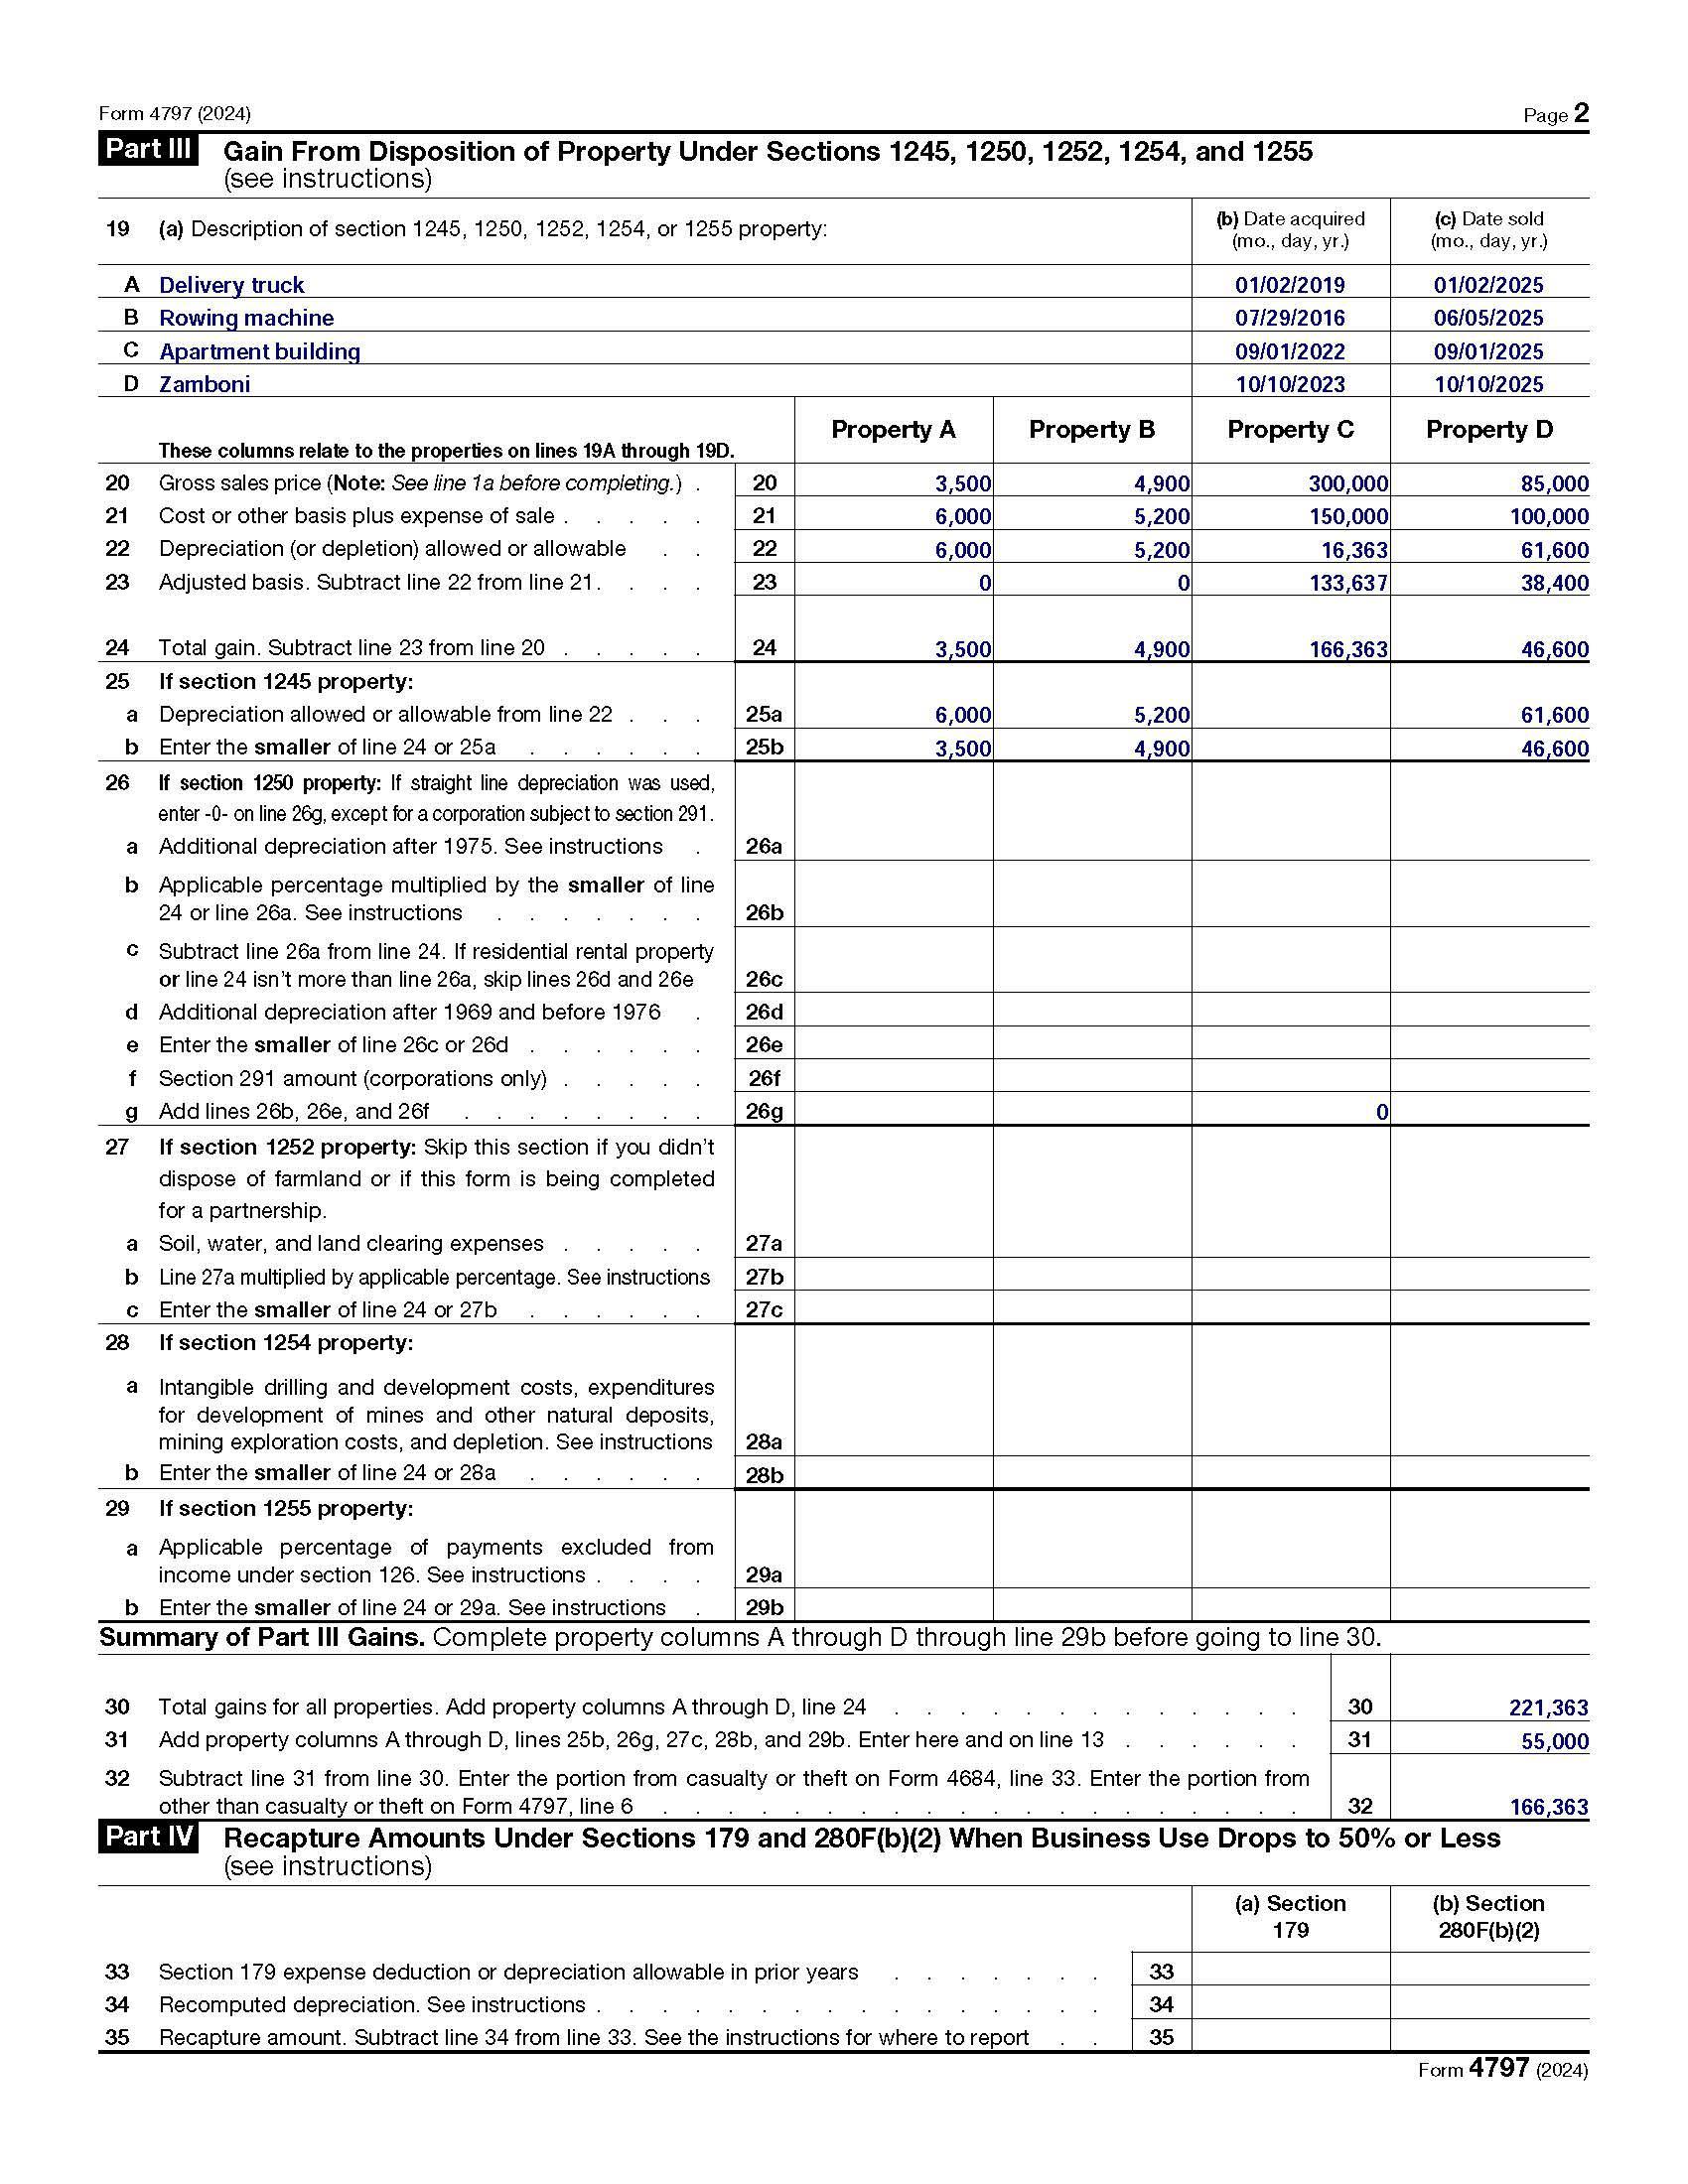
CPA Exam Preparation: Task-Based Simulation
1. Calculation of Realized Gain Hall Inc. is selling its current warehouse and purchasing another larger warehouse for its growing business. You will review a list of improvements provided by Hall Inc., as well as the settlement statements for purchase and sale, and determine the amount realized, adjusted basis, and realized gain on the sale.
Go to Wiley’s book companion site to complete the Task-Based Simulation.
Title: Task-Based Simulation: Calculation of Realized Gain
Difficulty: Medium
Learning Objective 1: 1.3
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Measurement Analysis and Interpretation
Standard 3: Bloom's || Analysis
Section Reference 1: 1.3
Solution:
What is Hall Inc.’s amount realized on the sale of its warehouse?
What is Hall Inc’s adjusted basis on the sale of its warehouse?
What is the realized gain on the sale?
Rationale:
Amount realized = Sales price
$273,400
$162,650
$110,750
$277,000
Less: Settlement charges (3,600) (from settlement statement)
Amount realized
$273,400
Property taxes are a business expense deduction and are not used in computing amount realized.
Adjusted basis = Purchase Price
$182,000
Plus: Settlement charges 4,150 (from settlement statement)
Plus: Capital improvements 27,500 ($25,000 + $2,500)
Less: Accumulated deprec. (51,000)
Adjusted basis
$162,650
Property taxes are a business expense deduction and are not used in computing adjusted basis. Capital improvements made to the warehouse increase the basis of the warehouse which includes the installed electric fence and the new roof. Repair and maintenance items are not considered capital improvements and are an ordinary and necessary business expense deduction.
Realized gain = Amount realized $273,400
Less: Adjusted basis (162,650)
Realized gain
$110,750
Time On Task: 12 minutes
2. Calculating Gain/Loss and Character on Sale of Assets Harry Clarke and Russell Addison own Nutty for U (NFU), a partnership located on Waverly Avenue in Windy City, Illinois. NFU is a very popular store for nuts, popcorn, and candy, but its owners would like to move their location closer to a popular ballpark. NFU will be selling some of its assets and would like to know the tax implications of each sale. You will calculate the gain or loss for assets like inventory, equipment, and real estate, and determine the character of each gain or loss.
Go to Wiley’s book companion site to complete the Task-Based Simulation.
Title: Task-Based Simulation: Calculating Gain/Loss and Character on Sale of Assets
Difficulty: Medium
Learning Objective 1: 1.1, 3, 4
Standard 1: AACSB || Knowledge
Standard 2: AICPA || AC: Measurement Analysis and Interpretation
Standard 3: Bloom's || Analysis
Section Reference 1: 1.1, 3, 4
Solution Calculate the
from the inventory sale
from the computer sale
from the machinery sale
Calculate the gain/loss and character from the equipment sale
Calculate the gain/loss and character from the building sale
Calculate the gain/loss and character from the truck sale
Calculate the gain/loss and character from the land sale
$51,000 25% gain, $35,000 1231 Capital
($500) Ordinary loss
Inventory
Inventory is an ordinary asset which results in ordinary gain or loss when sold.
Computer
Tangible Personalty held long term (more than one year) and used in a trade or business is a Section 1231 asset. The computer is Section 1231 property and the gain is Section 1231 gain, except for potential recapture under Section 1245. Recapture recharacterizes Section 1231 capital gain to ordinary income. Section 1245 recapture is equal to the lesser of the recognized gain ($1,000) or accumulated depreciation ($2,500). Because the accumulated depreciation taken on the computer exceeds the recognized gain, all of the gain ($1,000) is recharacterized as ordinary income.
Machinery
Machinery is also Section 1231 property because it was held for three years. The recognized gain is subject to Section 1245 recapture. Because the accumulated depreciation taken on the machinery ($27,000) exceeds the recognized gain ($3,000), all of the gain is recharacterized as ordinary income.
Equipment
Equipment is Section 1231 property because it was owned for four years. Because it is sold at a loss, it is not subject to the recapture provision under Section 1245. The equipment loss is a 1231 loss and can be netted against other 1231 gains.
Commercial Building
The building is a 1231 asset because its holding period is four years. Gains from the sale of buildings used in a business are subject to the Section 1250 recapture provisions. Under Section 1250, only the depreciation claimed in excess of straight-line depreciation is subject to recapture. Because the commercial building was placed in service after 1986, straight line depreciation was taken, so none of the $86,000 gain is recaptured.
To the extent of straight-line depreciation claimed ($51,000), the recognized gain is taxed at a maximum rate of 25%.
The remaining gain of $35,000 ($86,000 $51,000) is characterized as Section 1231 gain subject to a further netting process against any 1231 losses.
Delivery Truck
The truck is tangible personalty used in a business but because it is not owned more than a year, it is an ordinary asset (rather than Section 1231). Therefore, the loss of $500 is an ordinary loss.
Investment Land
The land is realty and depreciation is not allowed. Because the land was held for investment and not for business use, this land is a capital asset. The gain is a short-term capital gain. To be longterm, it would have to be owned more than one year.
Time On Task: 25 minutes
3. Saenz Qualified Business Income Javier and Maria Saenz, married filing jointly, have several business investments. Their adjusted gross income and taxable income for 2025 is $300,000 and $275,000, respectively, before any qualified business income deduction.
Referencing information from two Schedule K-1 forms and one Schedule C form, you will calculate their qualified business income deduction for three different deduction scenarios.
Go to Wiley’s book companion site to complete the Task-Based Simulation.
Title: CPA Exam Preparation: Task Based Simulation 2: Saenz Qualified Business Income
Difficulty: Hard
Learning Objective 1: 1.5
Standard 1: AACSB || Analytic
Standard 2: AICPA || AC: Measurement Analysis and Interpretation
Standard 3: Bloom's || Analysis
Section Reference 1: 1.5
Solution: Saenz Qualified Business Income
a. Calculate the qualified business income deduction. $19,091
b. Calculate the qualified business income deduction if Stay Fit is an athletic training business, the Saenzes are not partners or Scorporation shareholders in any businesses, and their taxable income before the QBI deduction is $495,000.
c. Assume Stay Fit is not an athletic training business but rather a sports retail store, and Stay Fit pays $5,000 in wages reducing QBI from Stay Fit to $29,800. Stay Fit has no qualified
$5,211
property. The Saenzes are not partners or S-corporation shareholders in any businesses. Calculate the qualified business income deduction for Stay Fit if their taxable income before the QBI deduction is $405,400.
a. Calculate the qualified business income deduction.
The Qualified Business Income (QBI) deduction is allowed as a deduction from AGI. The deduction applies to taxpayers with QBI from a partnership, S corporation, or sole proprietorship. Generally, without any further limitations, a taxpayer may deduct 20% of the taxpayer’s QBI from a qualified trade or business (after application of the wage limit and after subtracting one half of the applicable self-employment tax generated) for each qualified trade or business.
A qualified trade or business is any trade or business other than a specified service trade or business and other than the trade or business of being an employee. A specified service trade or business is any trade or business involving the performance of services in the fields of health, law, consulting, athletics, financial services, brokerage services, or any trade or business where the principal asset of such trade or business is the reputation or skill of an employee or owner. Architecture and engineering services are specifically excluded from the definition of specified service trade or business. QBI does not include guaranteed payments.
The wage/property limitation does not apply to the Saenzes because their modified taxable income does not exceed $394,600 (2025).
Electrolyte Partnership K-1: QBI Deduction
BMI Inc. K-1: QBI deduction is $12,000 × 20% = $2,400.
Income generated from an S Corporation is not subject to self-employment tax.
Stay Fit Schedule C: QBI Deduction
$32,341 ($34,800 – $2,459)
Once the QBI deduction is computed for each qualified business, the deductions are added together (businesses with losses have negative QBI) and the overall QBI deduction on the tax return is limited to 20% of the excess, if any, of taxable income over the taxpayer’s net capital gains (including qualified dividends)
The Saenzes’ QBI deduction equals $19,091, the lesser of:
a. $10,223 + $2,400 + $6,468 = $19,091, or
b. 20% × (TI – Qualified Dividends) = 20% × ($275,000 – 500) = $54,900
b. Calculate the qualified business income deduction if Stay Fit is an athletic training business, the Saenzes are not partners or S-corporation shareholders in any businesses, and their taxable income before the QBI deduction is $495,000.
If Stay Fit is an athletic training business, the business is considered a specified service trade or business.
For 2025, if the taxpayer’s modified taxable income (before the QBI deduction) is less than $197,300 ($394,600, MFJ), the exclusion for specified service trades or businesses will not apply. Therefore, a taxpayer operating a business that is a specified service trade or business still receives the QBI deduction if their modified taxable income does not exceed the thresholds. If the taxpayer has taxable income in excess of $197,300 ($394,600, MFJ), the exclusion phases in over a $50,000 range ($100,000, MFJ). The exclusion is fully phased in for taxpayers with taxable income in excess of $247,300 ($494,600, MFJ).
If the taxpayer has modified taxable income in excess of $247,300 ($494,600, MFJ) and is in a specified service trade or business, then no QBI deduction is allowed. Because the Saenzes’ modified taxable income is $495,000, their QBI deduction is $0.
c. Assume Stay Fit is not an athletic training business but rather a sports retail store, and Stay Fit pays $5,000 in wages, reducing QBI from Stay Fit to $29,800. Stay Fit has no qualified property. The Saenzes are not partners or S-corporation shareholders in any businesses. Calculate the qualified business income deduction for Stay Fit if their taxable income before the QBI deduction is $405,400.
1. First, calculate the QBI deduction without the wage limitation:
Schedule C income
$29,800 0.9235 Net Schedule C income
Self-employment tax rate
0.153 Self-employment tax $ 4,211 One half of SE tax $ 2,106
Net QBI
$27,694 ($29,800 – $2,106)
QBI deduction rate 0.20
QBI deduction $ 5,539
2. Then, calculate the reduction ratio, which is the amount of taxable income in excess of the threshold divided by the $100,000 range.
$405,400 – $394,600 = $10,800 ÷ $100,000 = 10.8%
3. Next, calculate the excess amount, which is the QBI deduction before the wage/property limitation less the QBI deduction with a fully phased-in wage and property limitation.
Wage/Property limitation is $2,500, the greater of:
a. 50% of the wages paid with respect to the qualified trade or business = $2,500 ($5,000 × 50%), or
b. The sum of 25% of the wages with respect to the qualified trade or business plus 2.5% of the unadjusted basis for all qualified property in the qualified trade or businesses = (25% × $5,000 + (2.5% × $0) = $1,250.
Therefore, the excess amount = $3,039 ($5,539 – $2,500).
4. Multiply the excess amount by the reduction ratio:
$3,039 × 10.8% = $328
5. Finally, calculate the QBI deduction after phase-outs:
Time On Task: 20 minutes
$5,539 – $328 = $5,211