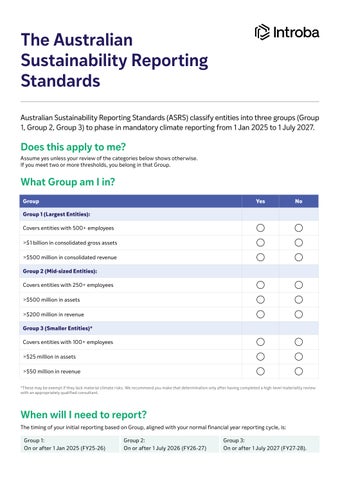
The Australian Sustainability Reporting Standards Australian Sustainability Reporting Standards (ASRS) classify entities into three groups (Group 1, Group 2, Group 3) to phase in mandatory climate reporting from 1 Jan 2025 to 1 July 2027.
Does this apply to me? Assume yes unless your review of the categories below shows otherwise. If you meet two or more thresholds, you belong in that Group.
What Group am I in? Group
Yes
No
Group 1 (Largest Entities): Covers entities with 500+ employees >$1 billion in consolidated gross assets >$500 million in consolidated revenue Group 2 (Mid-sized Entities): Covers entities with 250+ employees >$500 million in assets >$200 million in revenue Group 3 (Smaller Entities)* Covers entities with 100+ employees >$25 million in assets >$50 million in revenue *These may be exempt if they lack material climate risks. We recommend you make that determination only after having completed a high-level materiality review with an appropriately qualified consultant.
When will I need to report? The timing of your initial reporting based on Group, aligned with your normal financial year reporting cycle, is: Group 1: On or after 1 Jan 2025 (FY25-26)
Group 2: On or after 1 July 2026 (FY26-27)
Group 3: On or after 1 July 2027 (FY27-28).
The Australian Sustainability Reporting Standards
What will I need to report on? There are three categories you’ll need to provide information on: Category
Yep, I’ve got that
Requirement
Not sure/ Maybe some of that?
No, none of that
Policy on Climate Risk and Carbon Governance
Internal Processes for tracking performance on each of these, including Org Chart with roles and responsibilities List of credentials/expertise in Climate and Carbon within the leadership team of the organisation Process for assessing and reporting on climate related risks and opportunities which aligns with the requirements of the Corporations Act
Strategy
Process which links the outcomes of the above you’re your financial risk assessment process Evidence that the outcomes of this assessment have directly informed the organisation’s strategy which demonstrate an understanding of how these risks effect the financial position, performance and resilience of the business model Carbon emissions baseline addressing Scope 1, 2 and 3 emissions as defined by the GHG Emissions Protocol
Metrics and Targets
Targets for reductions for each of these scopes, including referenced standards, strategies which are being used to meet the targets, the extent and type of offsets being utilised to meet the targets, and third-party review process Basis of reporting for data being used to demonstrate progress against the targets
How long does it take to prepare this documentation?
If you have any of the above columns ticked with 'no', you will need more time, our general guidance would be:
Give us a call – we would be happy to talk through where you are and what you need and how we can help. SYDNEY: mary.casey@introba.com | +61 294 319 415
MELBOURNE: eben.simmons@introba.com | +61 392 490 242