STRENGTHENING FOUNDATIONS
Perspective and planning count as brokers grow their business p.8
ABORIGINAL TITLE OVER PRIVATE LANDS
Legal uncertainty after recent court decisions p.38
BUSINESS METRICS THAT MATTER
Intentional changes build success p.26
Perspective and planning count as brokers grow their business p.8
Legal uncertainty after recent court decisions p.38
Intentional changes build success p.26
Subtle differences come with the territory p.16
CMBA National provincial presidents’ update p.10
clusive Incubator Experience — Only at CMBA-BC! or an interac tive incubator ou'll build a personalized o perform at your best without burning out.


Intentional changes add up to meaningful success BY LISA GORDON
NAVIGATING COMPLEXITY, COAST TO COAST
The presidents of CMBA-Atlantic, CMBA-Ontario and CMBA-BC reflect on the key moments of 2025 and share what’s in store for the year to come BY SAMANTHA ASHENHURST
ONE INDUSTRY. ONE VOICE. A STRONGER FUTURE.
Mortgage brokers help Canadians navigate one of the most important financial decisions of their lives
BROKERING ACROSS BORDERS
Mortgage brokers who offer their services in more than one province find that subtle differences come with the territory BY LISA GORDON
AFTER THE SURGE: UNDERSTANDING THE GTA’S HOUSING MARKET DECLINE
Why falling prices, stalled projects and policy missteps signal a long reset for GTA developers BY SAM BILLARD
ABORIGINAL TITLE OVER PRIVATE LANDS
Legal uncertainty after recent court decisions BY ROY MILLEN, SAM ADKINS AND NICHOLAS TOLLEFSON
RESTRICTED INSURANCE LICENSING IN B.C.
What mortgage brokers need to know BY CARLA GILES
THE CANADIAN MORTGAGE BROKERS ASSOCIATION
EXECUTIVE DIRECTOR Carla Giles
CMBA - ATLANTIC
Mortgage Brokers Association of Atlantic Canada 12 M - 7095 Chebucto Road, Halifax, NS B3L 0A1
CMBA - BC
Mortgage Brokers Association of British Columbia 900-2025 Willingdon Avenue, Burnaby, BC V5C 0J3
CMBA - ONTARIO
Independent Mortgage Brokers Association of Ontario 7 - 40 Winges Road, Woodbridge, ON L4L 6B2
CMBA - QUEBEC L'Association des courtiers hypothecaires du Québec 5855 Taschereau #202, Brossard, QC J4Z 1A5
CANADIAN MORTGAGE BROKER magazine is produced by the Canadian Mortgage Brokers Association (CMBA National)
MANAGING
BILLING
Millen
Tollefson
The views expressed in CANADIAN MORTGAGE BROKER are those of the respective contributors and are not necessarily those of the publisher or staff.
Please return undeliverable Canadian addresses to 900-2025 Willingdon Ave., Burnaby, BC V5C 0J3
Why perspective and planning matter for brokers focused on growing their business
BY CARLA GILES, MBA, CAE, CEO OF CMBA-BC, MBIBC, EXECUTIVE DIRECTOR, CMBA NATIONAL
Periods of uncertainty tend to invite two unhelpful responses: waiting for clarity or reacting to every new signal. Neither serves mortgage brokers particularly well right now.
The current environment – defined by regulatory change, uneven housing markets, shifting interest-rate expectations and growing professional complexity – calls for something more deliberate. This is a moment to strengthen foundations: to be intentional about business planning, structure and strategy, rather than reactive to headlines or short-term swings.
That message was reinforced in remarks delivered by JeanFrançois Perrault, chief economist at Scotiabank, at a recent CMBA-BC event in Burnaby. Reflecting on what he described as a “bonkers” year, Perrault noted that much of the volatility stemmed from geopolitical and U.S. political noise rather than Canadian fundamentals. Despite that turbulence, Canada avoided recession and recorded moderate economic growth, supported by earlier rate cuts, expansionary fiscal policy and strong equity markets.
The takeaway was not that uncertainty has passed. It was that learning how to operate through it matters more than trying to predict its end.
Perrault emphasized that in an environment shaped by global politics, shifting trade dynamics and uneven inflation pressures, the most valuable service professionals can offer is perspective. Markets and households have become more resilient to headline risk, even as uncertainty remains elevated. His message was not to chase forecasts, but to focus on fundamentals – particularly for borrowers making real decisions in real time.
From a borrowing-cost perspective, his caution was clear. With the Bank of Canada closer to a pause than further rate cuts, borrowing costs are not on a one-way path lower. Global fiscal pressures, geopolitical risk and inflation dynamics suggest that longer-term borrowing costs could rise later in 2026. For brokers and their clients, the implication is straightforward: waiting for perfect conditions can carry its own risks. Clear advice, grounded in long-term fundamentals rather than short-term noise, matters more than ever.
That perspective aligns closely with what we are seeing across the profession. Economic volatility has not disappeared, and housing markets continue to vary widely by region. In many areas, prices appear to be stabilizing, but supply constraints remain unresolved. Population growth has slowed in the near term, yet pressures are likely to return as growth resumes. This is not a clean reset. It is a period of persistent complexity.
In this context, building a strong business foundation becomes a genuine competitive advantage.
The feature article in this issue on business planning and metrics (see p.26) illustrates this well. Brokers who track meaningful data, work backward from defined goals and deliberately structure their time and teams are not simply improving productivity; they are building resilience. Metrics, when used properly, provide visibility and clarity on where effort translates into outcomes and where it does not. In uncertain markets, that clarity allows for earlier course correction and more confident decision-making.
Just as importantly, structure creates space for leadership. Businesses that lack systems tend to operate in a constant state of urgency. When roles, processes and priorities are clear, brokers move out of reaction mode and into intentional management. That shift supports better client experiences, more sustainable growth, and longterm personal well-being – outcomes that matter as much in volatile periods as in strong ones.
The same theme runs through this issue’s article on interprovincial brokering. As more brokers consider licensing across multiple jurisdictions – whether to support mobile clients, follow opportunity or scale their practices – the operational and compliance demands become impossible to ignore. Disclosure regimes differ. Suitability requirements vary. Advertising rules, errors and omissions coverage, licensing obligations and continuing education cycles are not interchangeable.
Interprovincial brokering can be rewarding and strategically sound, but it is not simply an extension of existing practice. It requires infrastructure, governance maturity and ongoing education. It demands clear business cases and realistic assessments of administrative capacity.
In short, it reinforces the same lesson: growth without foundations increases risk.
This applies equally to specialization. As client needs diversify and lending segments become more distinct, many brokers are choosing to focus their practices more narrowly. When done intentionally, specialization can sharpen expertise and improve outcomes. When pursued without structure, it can strain systems and dilute service. Once again, planning makes the difference.
None of this is unique to mortgage brokering. Across professional services, expectations are rising around consistency, accountability and consumer protection. Experience alone is no longer sufficient without systems to support it. The industry is not standing still; it is becoming more disciplined.
Against that backdrop, Perrault’s advice to “control what you can control” resonates. No broker can dictate geopolitical outcomes, interest-rate paths or demographic trends. But brokers can control how their businesses are designed, how decisions are made and how clients are guided through uncertainty.
That guidance role may be more important now than at any point in recent memory. Housing affordability remains a structural challenge in Canada, and even ambitious policy efforts are unlikely to close the gap quickly. More households will rent for longer, and homeownership will look different than it has in the past. In that environment, clients do not benefit from headline-driven advice. They benefit from perspective.
Providing that perspective requires preparation. It requires brokers to understand not only products and policies, but also their own capacity, risk tolerance and strategic direction. Professional infrastructure – associations, education, shared standards and peer networks – plays a stabilizing role here, particularly during periods of transition.
This moment offers a choice. Brokers can wait for uncertainty to resolve itself, or they can use it as a catalyst to strengthen foundations: clarify goals, invest in planning and build systems that support long-term leadership.
Uncertainty is unlikely to disappear, but preparedness can be built. And in times like these, that may be the most reliable advantage available.
Flexi Line™ – a secured Home Owners Line of Credit
Finally a flexible credit product for your high value clients!
Ask your BDM about our Flexi Line™ today!
We offer 24 Hour turnaround on commitments – allowing you to present solutions for your clients sooner rather than later.
Equity Lending up to 2,000,000 1st and 2nd Mortgages
Purchase / Refinance, ETO up to 75% LTV
Special offers for 600+ Beacon Scores in large urban centres
Frank Wang BDM 604-690-4037 fwang@capitaldirect.ca
Robby Parmar BDM 604-690-4810 rparmar@capitaldirect.ca
Donna Hunter BDM 403-874-6348 dhunter@capitaldirect.ca
Kyla Hunter BDM 403-278-6200 khunter@capitaldirect.ca
Miro Rendine BDM 905-299-1706 mrendine@capitaldirect.ca
ATLANTIC CANADA
Greg Kakuno BDM 1-866-830-7734 / 902-455-7700 gkakuno@capitaldirect.ca
BY SAMANTHA ASHENHURST
THE PRESIDENTS OF CMBA-ATLANTIC, CMBA-ONTARIO AND CMBA-BC REFLECT ON THE KEY MOMENTS, REGIONAL REALITIES AND SHARED LESSONS OF 2025, AND SHARE WHAT’S IN STORE FOR THE YEAR TO COME
As 2025 came to a close, mortgage brokers across Canada reflected on a complex year marked by cautious consumers and regional shifts, but also by advocacy wins, opportunity and a clearer recognition of the broker’s role.
In this cross-country update, the presidents of CMBAAtlantic, CMBA-Ontario and CMBA-British Columbia reflect on the key moments and lessons that shaped the past year, from market dynamics and policy priorities to education, engagement and leadership transitions.
While each province faced distinct challenges, shared national themes emerged, underscoring the importance of collaboration. Together, these perspectives offer insight into what brokers should be watching as we head into 2026.
The past year was exceptionally strong and fast paced for mortgage brokers across Atlantic Canada. Continued inter-provincial migration into our region, combined with affordability relative to other parts of the country, kept housing demand steady throughout the year. Government programs and policy adjustments aimed at supporting first-time homeowners also played a key role in bringing new buyers into the market, particularly in rural and growing communities.
As a result, brokers across all four Atlantic provinces remained consistently busy, navigating higher volumes while continuing to provide education, guidance and stability for clients in a market that required both adaptability and strong communication. Overall, 2025 can be described as a prosperous and opportunity-filled year for Atlantic Canadian mortgage professionals, reinforcing the value brokers bring to both consumers and the housing ecosystem.
As we move into 2026, one of our top priorities as an association is governance renewal and strategic direction. We anticipate a shift within our board of directors, welcoming new members and fresh perspectives that will help guide the association through its next phase of growth. This transition presents an opportunity to build on the strong foundation already in place while ensuring the association remains responsive, forward-thinking and member-focused.
Building on the momentum from 2025, we are also excited to expand our signature events. One of our proudest accomplishments last year was hosting the CMBA-Atlantic Charity Golf Tournament on Prince Edward Island, which exceeded expectations and reinforced the strength of our broker community. In 2026, we look forward to hosting the tournament in Newfoundland during the week of the George Street Festival, creating an even larger platform for connection, collaboration and community impact.
To members of CMBA-Atlantic: I want to share that at our April annual general meeting, I will be stepping back from my role as president and from the board of directors.
Serving this association has been an honour, and I am incredibly proud of the work we’ve done together – from strengthening our events and advocacy efforts to building a strong, engaged broker community across Atlantic Canada. I’m deeply grateful for the trust, collaboration and dedication shown by fellow board members, volunteers and our membership.
As the association moves into its next chapter, this transition will create space for fresh leadership and new perspectives to help guide its continued growth. I remain fully supportive of the board and confident in the direction ahead.
This past year reminded all of us that our industry moves in cycles – sometimes fast, sometimes painfully slow – and staying adaptable is key. We saw brokers double down on professionalism, technology and financial literacy, and we learned that collaboration across the ecosystem is necessary.
For CMBA-Ontario, advocacy really mattered in 2025. We strengthened our voice on regulatory issues, expanded educational offerings that brokers actually use in the field and made meaningful progress in building bridges between industry, government and consumers.
A key focus was pushing for an increase to the provincial land transfer tax rebate to give first-time buyers in Ontario a fighting chance, and we will continue to focus on this moving forward. Ontario feels the shifting affordability story more intensely than most, but the broader themes are shared across Canada: rising cost of living, complexity in credit profiles and consumers who want advice. The mortgage conversation has become unmistakably national.
Heading into 2026, brokers should keep an eye on three things: regulatory momentum, technology that supports (not replaces) human advice and the evolving expectations of a younger, more informed borrower. The brokers who thrive will be the ones who lean into education, embrace tools that improve efficiency and keep relationships at the centre of the transaction.
The demand for guidance isn’t going away; if anything, it’s about to grow.
While signs of stabilization emerged in 2025, the British Columbia mortgage market remained complex, requiring resilience and leadership from brokers navigating affordability concerns and cautious consumer sentiment.
One defining opportunity has been the growing recognition of mortgage brokers as strategic financial partners; not just rate providers. As clients navigated renewals, refinances and constrained purchasing power, brokers played a critical role in helping households make confident, informed decisions.
At CMBA-BC, we focused heavily on member value, visibility and credibility. I’m most proud of the association’s continued advocacy efforts on behalf of brokers, ensuring our voice remained present in conversations around regulation, consumer protection and industry standards.
We also expanded our education and engagement initiatives – both in-person and digital – creating more accessible, relevant programming for brokers at all stages of their careers. Strengthening partnerships with lenders, insurers and industry stakeholders helped elevate the profile of B.C. brokers and reinforced the professionalism of our channel.
Of course, the most significant challenge in 2025 was navigating uncertainty – whether related to rate expectations, policy interpretation or shifting lender appetites. For the association, this reinforced the importance of clear communication, timely education and proactive leadership. One key lesson was that engagement matters more than ever. Brokers want transparency, connection and practical support, and that has shaped how we approach decision-making, programming and advocacy heading into the year ahead.
In 2026, CMBA-BC will remain focused on advocacy, education and community. Supporting brokers through ongoing regulatory changes, continuing to professionalize the channel and helping members adapt to evolving client expectations are top priorities.
We are also focused on leadership development and succession, ensuring the next generation of brokers is well-equipped, ethical and supported. As technology, compliance and consumer expectations evolve, brokers who invest in process, education and client experience will be best positioned to succeed.
To our members: Thank you for the integrity, professionalism, and care you bring to your clients and communities every day. The strength of our association is built on your engagement and commitment. As we head into 2026, CMBA-BC remains focused on supporting you, advocating for you and ensuring the mortgage broker profession continues to thrive in British Columbia.
Mortgage brokers across Canada operate in different markets, under different provincial rules, but they share the same core purpose: helping Canadians navigate one of the most important financial decisions of their lives. CMBA National exists to bring those shared interests together.
As the national umbrella organization for Canada’s provincial mortgage broker associations, CMBA National connects, aligns and strengthens the profession from coast to coast. It provides a forum for collaboration, shared leadership and national advocacy – so provincial associations can stay focused on delivering meaningful, local support to their members.
CMBA National was established in 2014 with a clear goal: strengthen the mortgage broker profession through collaboration, not duplication.
By bringing together provincial associations, including Canadian Mortgage Brokers Association - British Columbia, Canadian Mortgage Brokers Association - Ontario, Association des courtiers hypothécaires du Québec, and Canadian Mortgage Brokers Association –Atlantic, CMBA National creates space for shared learning, coordinated messaging and collective problem-solving.
Instead of working in silos, provincial leaders come together to identify emerging trends, respond to national policy issues, and advance initiatives that benefit mortgage brokers and consumers across Canada.
CMBA National focuses on the work that is best done nationally:
CMBA National represents the mortgage broker profession in federal policy conversations, ensuring brokers’ perspectives are considered in housing, finance and regulatory discussions that affect Canadians nationwide.
Supporting provincial associations
Through shared branding, communications tools and national awareness initiatives, CMBA National helps provincial associations amplify their impact and deliver greater value to their members.
Professionalism and trust
CMBA National supports consistent standards of professionalism and ethical conduct across the country, aligning with national frameworks such as the Mortgage Broker Regulators’ Council of Canada’s Code of Conduct to reinforce integrity and consumer confidence.
While CMBA National works at the national level, provincial associations remain the heart of member support.
They advocate on provincial issues, engage with local regulators and governments, deliver licensing and continuing education and create opportunities for connection through webinars, events, conferences and trade shows. Together, this national-provincial partnership ensures brokers benefit from both local expertise and national coordination.
Leadership and governance
CMBA National is governed by a Board of Directors nominated by the provincial associations and supported by executive director Carla Giles.
The Board includes John Woods (president), Jessica Rickerby (vicepresident), Jim DeCoste (treasurer), Jeff Brown (secretary), Lesley Stevens and Michelle Campbell.
Working better together
CMBA National is built on a simple belief: a connected industry is a stronger industry.
By aligning provincial associations, supporting ethical practice and advocating at the national level, CMBA National helps ensure mortgage brokers remain trusted professionals and essential partners for Canadians navigating homeownership.
Mortgage brokers who offer their services in more than one province find that subtle differences come with the territory
BY LISA GORDON
Labour mobility or licence reciprocity is common, but there are some rules you have to navigate, which vary between provinces. For example, Form 10 in B.C. that discloses compensation paid to the brokerage and broker doesn’t exist anywhere else. Suitability requirements in Ontario are unique, and cost of credit disclosures are different in Alberta. Justin Noda
As Canada forges through economic uncertainty, the national real estate market has slowed, with some regions more sluggish than others. Whether it’s an overabundance of supply, affordability issues, or a combination of both, challenges vary from one province to the next –as do mortgage industry regulations.
Justin Noda has spent 19 years working in the mortgage industry, including roles as an underwriter, managing director and director. This past October, he accepted a role as chief compliance and operations officer for A Better Way Mortgage Group, primarily based in Langley, British Columbia. The company’s growth spurred the need for a full-time individual to handle compliance and operations, especially with the pending implementation of B.C.’s new Mortgage Services Act (MSA).
“I used to work with these guys about eight years ago, when I was working as an underwriter,” said Noda. “It was the right place at the right time.”
Noda, who lives in Calgary, holds a mortgage associate license in Alberta, a mortgage broker license in Ontario, and is registered as a submortgage broker in British Columbia. In his new role, he is heavily involved in licensing, offering assistance to agents who work across all three provinces. While he said many mortgage professionals have an interest in getting licensed in multiple jurisdictions, they do need to ask themselves whether “the juice is worth the squeeze.”
Justin Noda
Noda said most provinces have a specific application process for obtaining a broker’s licence. He simplified it down to, “you apply here, supply this, and then you wait.” The process could involve a criminal background check and licence history from the applicant’s current jurisdiction. There is an associated cost, which varies from province to province.
Commonly, mortgage professionals can apply under labour mobility or licence reciprocity rules, which means the province of application may consider an agent’s industry experience in their home province. That could mean an exemption from beginner licensing requirements, said Noda.
“Labour mobility or licence reciprocity is common, but there are some rules you have to navigate, which vary between provinces.”
In fact, Noda believes the number of regulatory bodies and their different approaches is an impediment to the Canadian mortgage industry. Each province is just different enough, he says, that it can create a nightmare when it comes to broker compliance.
“For example, Form 10 in B.C. that discloses compensation paid to the brokerage and broker doesn’t exist anywhere else. Suitability requirements in Ontario are unique, and cost of credit disclosures are different in Alberta,” he explained.
If a broker only handles one or two deals a year out of province, using available resources like ‘deal desks or hubs’ – which handle mortgages files for a fee – can be an option, Noda suggested. For those looking to actually get licensed in another province, he advised they research the necessary steps and make sure their current brokerage has an
office in the province they are looking to license in.
“If they don’t, you will need to find another brokerage licensed in that province willing to take you on,” said Noda. “I think that is one reason larger firms are getting licensed in multiple provinces, giving the brokerage a presence in different provinces and a better ability to recruit.”
Licensing differences between provinces is all on the compliance side, he continued. “You can’t advertise in a province you are not licensed in, and your errors and omissions won’t cover you either, even if you have moved there.”
Inter-provincial brokering and licensing has been subject to increasing regulation over the past five years as compliance requirements have increased. “Before that, it was like the Wild West, where closing deals in other provinces attracted little to no attention,” recalled Noda.
He ended by advising mortgage professionals who wish to get licensed in other provinces to consult with their principal broker. Importantly, he added that if a broker is considering a move, “regulations require you to be licensed in the province you reside in, even if your clientele is still in the province you moved from.”
Julie Sheremeto knows all about brokering across borders. Now a mortgage broker at Tango Financial (Your Mortgage Design Team) in Kelowna, B.C., she used to teach high school math and live in Ottawa. She left the school system and started her mortgage career in 2017, and now
holds broker licences in both Ontario and British Columbia.
“In 2017, I was teaching and I knew I needed a change, so I got my licence and started brokering in Ottawa,” recalled Sheremeto. At first, she taught part-time while growing her new career, but quickly shifted her entire focus to mortgage brokering. Sheremeto started establishing her client base, but then the pandemic arrived. The quality of life in Ottawa became pretty dismal; she was working remotely and no longer met clients in person.
Needing a change, she started spending more time in B.C. “My mother and stepfather have had a place in Kelowna since the mid-’80s, so I started spending about half my time there.”
Sheremeto began networking in Kelowna, but only being licensed in Ontario restricted her from growing her business.
“For a while, I was travelling at about a 50/50 time split between the provinces, while I went through the process of becoming licensed in B.C., which I obtained in 2021.”
Transitioning to a new province posed a few logistical challenges, Sheremeto recalled. She had to retain her Ontario licence, for one.
“Initially, I spent a lot of time back in Ontario, since 60 to 70 per cent of my clientele are either existing clients or referrals from them and from trusted partners,” she explained. “I still go back four to six times a year to continue to service my Ontario clients.”
Investigating regulatory differences between the provinces was also an eye-opener for Sheremeto. She noted different disclosure forms, a different set of compliance documents
The biggest piece of advice I can give to a broker considering licensing in another province is to find an experienced mentor or business partner who is with your brokerage and is familiar with that province’s best practices. Julie Sheremeto
and differences in what kind of material risk disclosures need to be made. “The regulatory side is a beast.”
Managing the time zone difference has also been a challenge.
“Conditions of financing may need to be met and clients may be meeting with their lawyer at 8:30 a.m. in Ontario, but it is 5:30 a.m. in B.C.”
Aligning with a brokerage that has the proper support in each province, including lender relationships and volume relationships, will help brokers succeed, Sheremeto said. “I tried to do it solo in B.C. for a while; the brokerage I was with in Ontario basically opened a new brokerage in B.C. where one didn’t exist.”
But being the only B.C. member of the firm was a challenge, so she eventually joined Tango Financial, which is established in both B.C. and Ontario.
“The biggest piece of advice I can give to a broker considering licensing in another province is to find an experienced mentor or business partner who is with your brokerage and is familiar with that province’s best practices.”
Learning B.C.’s regulatory and compliance ropes has led to some funny stories, added Sheremeto. She explained that the differences in process and requirements between the provinces, especially regarding purchase financing, required an on-the-job learning curve.
“Not understanding that subject removal in B.C. meant all broker conditions were already fulfilled resulted in some interesting conversations with Realtors,” she said with a laugh.
British Columbia-based broker-owner
Tricia McIntosh started her mortgage career as an independent broker and eventually moved into leadership, mentoring and operations. As one of the co-founders of The Mortgage House, an independent national brokerage she created with two other broker partners, the 15-year mortgage professional has seen her role evolve significantly throughout her career.
As McIntosh’s client base expanded –especially among federal government and Royal Canadian Mounted Police (RCMP) members, who relocate frequently across the country – becoming licensed in multiple provinces allowed her to properly support her clients wherever they had to move.
every deal fits a traditional box.
• Clear terms
• Direct communication
• We understand alternative lending When flexibility matters, Liahona MIC helps you keep files moving and deals closing with:
your alternative lending toolkit with Liahona.
Julie Sheremeto
Only pursue licences where you have a clear business case. Start with one additional province, not several. Get comfortable with the workflow, compliance requirements and market differences before expanding further. Tricia McIntosh
“Canada is a country where mobility is common, especially for RCMP members, military families and federal employees,” said McIntosh. “Being able to maintain that continuity of care in those relationships, no matter where they move, is incredibly important to me.”
In 2019, she obtained her first out-ofprovince licence in Alberta. “At the time, I was co-brokering multiple files there and it made sense to take on the work directly,” she recalled.
McIntosh saw demand increase from her clients in Manitoba, Saskatchewan and Ontario, due to work transfers. Within a year, she had expanded her licences to include those provinces in order to maintain long-term relationships. In 2024, she added Nova Scotia, followed by New Brunswick in 2025, in order to support clients posted to Atlantic Canada.
McIntosh enjoys the benefits of her nationwide network. However, staying current on all provincial regulatory frameworks, continuing education requirements and renewal cycles is the most challenging aspect of holding multiple licences.
“I had to be prepared to stay compliant, educated and organized when expanding into multiple provinces,” she said. “It’s absolutely worth it, but it requires intentional effort and ongoing education. It’s also important to understand the administrative workload.”
Navigating the differences in provincial real estate markets and contract structures across Canada adds another wrinkle to McIntosh’s portfolio. “You can move from a strong buyer’s market in one province to a tight seller’s market in another. Contract structures differ as well; for example, some provinces
Tricia McIntosh
require property disclosure statements, while others don’t use them at all.” Title registration can also vary, creating differences in closing timelines and lawyer/ notary practices, she continued.
McIntosh illustrated provincial regulatory differences with an example of clients from Western Canada purchasing a new build in New Brunswick.
“I was accustomed to a new home warranty being mandatory on newly built properties, but New Brunswick does not require builders to provide this warranty,” she said. The discrepancy came to light only a couple of days before funding. McIntosh was able to secure a temporary private mortgage so the clients could still close on time. “About six weeks after closing, a lender agreed to take on the file,
and we were able to replace the private mortgage with long-term financing.”
Holding multiple provincial brokering licences is incredibly rewarding, but it also comes with a lot of responsibility.
“Only pursue licences where you have a clear business case,” she advised. “Start with one additional province, not several. Get comfortable with the workflow, compliance requirements and market differences before expanding further.”
Just as the national geography varies from Atlantic to Pacific, so too does mortgage brokering. Market prices, regulations and compliance can vary. And, just like making plans to travel across Canada, brokering across the country takes extensive planning, research, commitment and, of course, some expense.
Joe Rosati VP, Business Development jrosati@icsavings.ca
647.668.2807 icsmb.ca
BY SAM BILLARD
In 2024, I wrote a paper titled Distressed developers: Soaring costs, fixed returns and public policy create perfect storm, which was published by Lexpert. It described how development costs had escalated rapidly for a number of reasons, including high demand arising from historically elevated levels of immigration, cost increases in labour and construction materials, steep interest rates and significant costs associated with government
in the form of rapidly increasing development charges, land transfer taxes and the burden of municipal oversight.
Since then, the federal government has materially lowered its immigration targets and that, along with GTA residents moving to areas where housing is less expensive, has led to a decline in the population of the Greater Toronto Area (“GTA”). This, together with elevated interest rates, has contributed to a
steep decline in the resale value of homes of all sorts in the GTA. A decrease in interest rates has not materially altered that trend. The inflection point that started people reflecting on real estate investments was the dramatic rise in interest rates in 2021. That led to a decrease in resale prices, but the number of sales remained relatively stable through 2021 and early 2022. By the end of 2022, however, sales declined significantly.
Nationally, total immigration has gone from 1.3-million newcomers in 2024 to 480,000 in 2025 and is projected to be very low for the next three years. (The charts and graphs below were generously provided by Altus Group Limited.)
Source: Altus Group based on data from Statistics Canada
Source: Altus Group based on data from Ontario Ministry of Finance
Housing resale prices in the GTA are down by 25% from the peak for all types of housing.
However, construction costs have not declined in tandem with sale prices. Development charges and fees levied by Toronto and other municipalities, land transfer tax and compliance costs also remain stubbornly high.
The number of construction projects has dropped significantly in the GTA, as would be expected under the circumstances, particularly for high-rise buildings.
home sales by type, Greater Toronto Area
Projects launched but unbuilt are facing great difficulty in selling units. Developers are reluctant to drop their prices, likely because they represent the price that will allow them to make a profit on the project. However, resales of even newer condos are occurring at significant
discounts, making this pricing strategy difficult to maintain.
Simply put, developers are unable to build housing at a price that purchasers are willing to pay. The cost of construction has reduced slightly, but government-controlled costs are
constant. So, developers are not building and existing new condo units remain unsold at current prices.
This is also reflected in the decline in condo sales in the GTA – down by more than 60% on a year-over-year basis for both 2024 and 2025.
How can there be a housing crisis in the GTA if homes are available for sale at reducing prices? Those that could not afford to live in the GTA have left and there is no one coming to replace them. There is plenty of housing to meet demand. There is no shortage.
The Ontario government set a goal for itself of building 1.5-million new homes during the period from 2021 to 2031. The closest the province has come to building sufficient homes to meet that goal in any year was just under 90,000. Now, with population stable and perhaps declining, it seems that the entire program was unrealistic. One wonders where the 1.5 million number came from.
How did the pundits get this so wrong? I do not know but suspect that when public servants are estimating housing needs, they divide the number of people expected to be in an area by 2.5, which is the size of the average Canadian household. Perhaps if they were planning on there being 500,000 new immigrants in Ontario each year, the housing requirement makes sense. But that did not happen and will not happen in the foreseeable future.
What about the projects that have been built and are now being sold? In my previous article, I illustrated the dilemma faced by developers with reference to the Highlight of Mississauga project. Initiated in 2019, the developer of Highlight, Hazelton Development Corporation, filed for creditor protection under the Companies’ Creditors Arrangement Act on April 20, 2022. At that time, the developer reported that the project was 80% complete. Now, 3.5 years and $100 million later, the project is 89% complete and requires substantial further investment to bring it to conclusion.
The monitor issued its 25th report on October 20, 2025. Astonishingly, the debtor-in-possession (“DIP”) lender continues to pour money into this effort. The monitor reported that the DIP lender will not obtain full recovery, nor will any of the other creditors below the DIP lender in priority. The developer is reportedly thinking of finishing and then refinancing the project rather than trying to sell it in the current market. Who is going to finance an empty building?
I have spoken to banks that have financed condominium developments which have
now been completed. They speak of deposits abandoned and owners simply unable to raise the money to complete the purchase. A bank in that position could likely realize, but what would it do with an asset that is devaluing at a significant rate? That requires maintenance and tax payments and security. It would be expensive. If the developer is paying those costs, it may be prudent to leave well enough alone for a while.
At some point, the lenders behind these developments will need to sell and, if they all do it at once, there will be a further deterioration in the market. If the housing market stabilizes at what represents a recovery cost for senior secured lenders, it would be reasonable to expect that there will be a controlled sell-off of lender interests. That will keep the market flat for quite a while. Investment in residential real estate for resale will not be terrifically attractive until after that bump has moved through the market.
How did we get here? In the condo market in particular, there developed a group of private investors keen on committing to buying condos in the presale market in the expectation that they would be able to either assign their rights to purchase for a profit or purchase the condo and hold it until the price was right. These were largely local, small investors who put their savings into condos.
This works very well while prices are rising and encourages both building and building units for people that never intended to live in them. Investor purchases made up 50% to 80% of presales toward the end of the boom. However, these investors are sensitive to interest rates and the rise in interest rates was devastating for them. Having been burned, they are unlikely to return to this market anytime soon. Any new condo project will require presales to people who actually want to live in the resulting housing or substantial investment from the developer or others. That would be a material change in the financing model that has been used in the GTA for a long time.
But what happened to demand and why are people still talking about a housing crisis? There is no housing crisis for people who can afford housing at 75% of its price in 2022. That is still a high price, but it is
much better than it was, and it continues to trend down. If the purchase is optional, the canny investor will wait to see if what they want gets cheaper, especially in the economic circumstance in which Canada finds itself. This is a classic declining market, and the bottom is hard to predict.
In the GTA, there has been a significant overbuilding. If we continue trying to build at the rate promised by many political parties, we will have construction projects rotting empty on their plinths. But the market has spoken and there is very limited new construction.
There is a housing shortage for below-market and supported housing, perhaps. There is money in the federal budget for this type of housing. It would be interesting to see if the built but unsold projects could be converted to fill this need.
Finally, it is interesting to consider the importance of governments in this market. All three levels of government have a stake: the federal government because, up until recently, housing was among the top issues on voters’ minds and they have a share in sales tax; the provincial government because they are also interested in voters and earn considerable revenue from the land transfer tax and sales tax; and municipalities because they also have voters to please and receive fantastic amounts from development charges and land transfer tax. Municipalities also have complex policy agendas which play out in building standards: green roofs provide a recent costly and controversial example.
Land transfer taxes and development charges are popular with governments because they are not visible to voters most of the time. Altus estimates that total governmental charges represent 30% of the cost of a condominium unit. The same percentage also applies to rental housing. Provincial and municipal governments obviously have a role to play in housing, but it may be time to consider the cost.
Sam Billard is a partner in the Distressed Real Estate Group at Aird & Berlis, a leading Canadian law firm with offices in Toronto and Vancouver, serving clients across Canada and around the world. Aird & Berlis provides strategic legal advice on business, regulatory, constitutional, administrative law and public policy matters. More information: airdberlis.com
BY LISA GORDON
Mortgage broker Renée Huse knows that in order to increase her deal volume by $30 million this year, she needs to talk to about 35 more people every month. Her well established tracking metrics tell her how many of those contacts will probably convert to a mortgage application and then to a funded file.
Huse, a Calgary-based business planning coach and broker at the DLCG Mortgage Group, has spent almost nine years in the mortgage business. Experience has taught her that meaningful business metrics help brokers zero in on the actions that drive results, versus those that simply drain energy.
She never planned to become a business coach, but found herself gravitating to it after she set out to discuss industry best practices with other like-minded professionals.
“I built my mortgage business to roughly $100 million in about five years, and at that point I realized there is a whole new set of problems every time your business scales,” explained Huse.
“A lot of people in this industry don’t like to share, so I decided to go first. I started opening up about what I learned getting there – the systems, the decisions, the mistakes and the tradeoffs behind the numbers.”
...there needs to be a clear handoff between sales, underwriting and fulfillment. While brokers often feel busy, a system that tracks their activity gives them real visibility into where their time is going.
In October 2024, Huse led a breakout session on business planning for an industry association. She was overwhelmed by the response to her story, as brokers from coast to coast reached out, sharing their own experiences and asking deeper questions.
“That exchange made me better at my own craft and coaching grew naturally out of it,” recalled Huse. She doesn’t feel it came from positioning herself as an expert; rather, her coaching platform is about creating a welcoming and inviting space where serious brokers can think more clearly and intentionally about their pathways to success.
Brokers can face a multitude of challenges when trying to create a sustainable goal-oriented business plan, continued Huse.
“The patterns are incredibly consistent. Too much is sitting on the broker’s desk because there’s a scarcity mindset, and people often fear that delegation means someone is stealing their secrets.”
She said there needs to be a clear handoff between sales, underwriting and fulfillment. While brokers often feel busy, a system that tracks their activity gives them real visibility into where their time is going.
“You don’t know what you don’t know. So, working with someone who has that experience helps set goals and put an action plan in place that is grounded in facts.”
Huse believes the best way to achieve personalized goals is to work backwards. First, she determines the desired result and then defines the necessary steps to reach that goal.
“I help brokers untangle all of that so they can clearly see what to keep, what
to delegate with confidence and what to eliminate altogether,” she declared. Business planning and personal time are directly connected, and setting clear roles and priorities backed by intentional decisions will protect personal time.
“If you have been doing something for a long time, you can become complacent. If your business lacks structure, your personal life absorbs the chaos. The goal should be alignment, not balance,” said Huse.
Becoming more deliberate about business planning has changed Huse’s life. She said that when systems are implemented, brokers will notice a clear shift toward more predictable incomes, a better client experience, fewer reworks due to reduced mistakes, confident hiring decisions and significantly reduced work hours.
“Over time, that leads to sustained growth, more time with family, or the ability to do other things they actually love to do. I help them find that sweet spot.”
Huse practices what she preaches because she has seen the results first-hand. She gained more clarity about where her time mattered most, building a team with defined roles and expectations.
“My business grew, I retained staff better, and I had more time with my family. Business planning allowed me to step out of reaction mode and into leadership. Instead of being buried in the business, I became intentional about building it.”
To get started, Huse recommended writing down your own processes, so you can teach them to others and then delegate. It does take some time to pull it all together, she cautioned.
“The first thing you will notice is an improvement in the client experience when you become more intentional about business planning.” She feels retaining good people is among the biggest benefits of learning how to run and scale her business properly. “People want to know what is expected of them; it’s hard to retain good people in chaos.”
Once goals are identified and a plan devised, it’s important to stick to it. A coach, mentor or accountability partner can help you focus on meeting your targets.
“Sometimes brokers can get caught in ‘shiny new object syndrome,’ where you jump from one idea to the next,” said Huse.
She concluded with the advice that clarity is what drives momentum, and if aspects of the business are not bringing joy or money, they don’t belong. “Apply a simple filter to everything on your plate that has only two acceptable answers: hell yes, or heck no.”
...business planning and personal time are directly connected, and setting clear roles and priorities backed by intentional decisions will protect personal time.
Marci Deane, a Vancouver-based broker with Mortgage Architects, has been following Renée Huse, and others, for the past couple of years. With over 18 years of brokering experience, the last 12 spent with Mortgage Architects, Deane runs a small team with assistants and subbrokers, focusing on a steady stream of repeat clients.
Her business has grown since the early years, when she juggled a family life with young children, all while building her business database.
“It wasn’t the size that it is today,” explained Deane. “As it has grown, I had to think about a much bigger database and figuring out all the buckets of where clients are coming from.”
Deane, like Huse, said she has always preferred the “working backward” method to achieve targets.
“I have always worked backward and it helps that I am very goal-oriented.”
In 2024, she deliberately began tracking actions and results quarterly, versus yearly. Breaking it down to threemonth planning segments has allowed her to course correct quickly, when necessary.
“Ninety-day chunks allow a reset,” noted Deane. “If you are just waiting for your accountant’s report at the end of each year to see how you are doing, it’s too late.”
Quarterly tracking is part and parcel of her evolved business approach. “I am more businesslike by looking at all the numbers, not just deal per deal. I better understand my cashflow. I don’t think many are actually doing that.”
She says those who only check their numbers yearly often have to push hard
Marci Deane
for the last couple months of the year, if they feel they are behind.
“I look at my CRM (Customer Relationship Management) daily; it helps keep me on track,” said Deane. “I started really tracking leads. I know how many people I talk to in a week. I know for every month how many people I talked to, and what type of lead they were.”
Deane has embraced new technology and efficiencies as well, even adding a virtual assistant to help with some tasks. She now outsources some non moneymaking tasks to maximize her time where it is needed most, and even though her internal staffing hasn’t changed, her volume has increased.
“My volume was up about 80 per cent last year, but I actually had more free time.”
She was surprised to learn that carving out “down time” has made her more efficient.
“It also creates a happier family life. I set expectations with my clients on when I am available. I feel if you don’t do that, you become like a dog chasing its tail.”
The self-professed avid reader, podcast listener and conference attendee populates her calendar densely to ensure the best use of time. A knowledge seeker, she credits the likes of Gary Mauris, Dustin Woodhouse and Huse for helping her on her business journey.
Deane advised brokers to take it slow if they are new to business planning.
“Tackle a couple of things at a time, and don’t try to fix it all at once. You will do nothing that way. Be very strategic by tracking eight or nine data points on a weekly basis, not everything.”
She also recommended an accountability partner or coach. “Find your people. I sought out sharing people. Create your own network and help keep each other accountable.”
Finally, Deane recommended joining an industry association.
“I am constantly baffled if brokers are not members of their association. It’s the best way to network and there is a lot of great information available to members, even free seminars at times.”
She urged brokers to get involved with the mortgage broker community and take a little time out of the business to incorporate best practices and business tracking. “If you don’t have a plan, how can you have a destination?”
Consider that while a driver’s licence allows you to drive a vehicle, you might still need help navigating to your destination. Likewise, a broker may know all the ins and outs of creating the best deal for their clients, but they might still benefit from some help with setting and achieving business goals.
Like many things in life, asking for help sooner is typically better than later.
...when systems are implemented, brokers will notice a clear shift toward more predictable incomes, a better client experience, fewer reworks due to reduced mistakes, confident hiring decisions and significantly reduced work hours.
For CMBA Ontario vice-president Frank Napolitano, mortgage brokering is about education, integrity and giving back to both clients and community
BY SAMANTHA ASHENHURST
Few people understand the evolution of Canada’s mortgage landscape as intimately as Frank Napolitano. Based in Ottawa, Napolitano balances his work with clients alongside his role as vice-president of CMBA Ontario, advocating for higher standards, stronger education and greater trust across the industry.
Napolitano’s professional journey began more than 40 years ago when he took a gig as a teller with a major Canadian bank. In the decade to follow, he steadily worked his way up through the ranks, gaining experience as a loans officer, loans manager and, eventually, a mortgage officer.
By his early 30s, Napolitano was being groomed for senior leadership – including the opportunity to manage his own branch –but as the banking system evolved, so, too, did his outlook.
“I realized that the branch manager role had changed,” he says. “It had become more about managing people and complaints, with no real power of the pen.”
A major health challenge in the mid-1990s further sharpened his focus. After surgery related to Crohn’s disease, Napolitano returned to work with a renewed clarity about what he wanted from his career.
“I missed doing mortgages and loans,” he says. “That’s when I went to my district manager and said, ‘I want to try being a road rep.’”
The move came with risk, as Napolitano was the sole income earner for his family and had three young children at home. That said, he recognized the opportunity.
“I thought to myself, ‘If I’m going to work 50 hours a week anyway, why not work that hard and declare what I want to make?’” he says.
The gamble paid off. Within six months, Napolitano had earned more than he would have in his salaried role, with a strong pipeline of deals behind him. He went on to spend eight years as a mortgage specialist, finishing in the top 10 nationally for mortgage sales for seven consecutive years.
By 2005, though, another turning point emerged. Napolitano’s long-time colleague, Michael Hapke, had left the bank earlier and entered the broker channel. The two stayed
close, even competing at times, until Hapke floated an idea that would change both of their careers.
“Mike called me and said, ‘I’m working for a brokerage and seeing that we could do this better – especially together,’” says Napolitano. Soon after that conversation, the duo established Mortgage Brokers Ottawa. While it was an exciting endeavour, the business was not without its challenges, with an inaugural year marked by personal loss, stress and multiple obstacles. Still, the founders persevered.
“After our first year, we figured we had to make it work,” says Napolitano. “We’d gone through too much for it not to.”
What began as a small operation quickly grew, largely through word of mouth from former banking colleagues who shared Napolitano’s values. Education, he says, became a defining pillar of the business.
“One thing Mike and I believed was missing in Ottawa was education about what a mortgage broker actually does,” he says. “Homebuyers shouldn’t go to a mortgage broker only when their bank turns them down. They should start with a mortgage broker.”
“
I still love what I do. I love this industry, and I love the incredible people in it. That’s what makes me proud to be part of it.
That philosophy soon found a powerful platform. In May 2007, Napolitano started Open House – The Real Estate and Mortgage Show, a live, one-hour radio program airing every Saturday. The goal, he explains, was public education.
“My message for buyers has always been, ‘Start with a mortgage broker,’” says Napolitano. “People deserve to understand their options.”
Now, almost two decades later, the show has aired more than 900 live episodes – never pre-recorded – and continues to attract callers of all ages.
“What surprises us most is how many younger listeners we get now,” says Napolitano. “People in their early 30s are calling in with great questions.”
Napolitano’s passion for the industry extends well beyond his own business. In 2023, he was inducted into the Mortgage Professionals Canada Hall of Fame – an honour he describes as deeply meaningful.
Additionally, in January 2024, he was approached to join the CMBA Ontario board during a period of leadership transition. Initially hesitant, Napolitano agreed to step in on an interim basis.
Two years later, he remains vicepresident, with a particular focus on strengthening the association’s presence in Ottawa.
“Ottawa has always felt like the forgotten city,” he says. “There was no CMBA Ontario footprint here, even though there are a lot of great brokers.”
Since then, CMBA Ontario has hosted multiple sold-out events in the region, including golf tournaments and educational sessions that continue to gain momentum.
“I guess it’s working,” says Napolitano. “Now brokers are calling me asking when the next event is and who the speakers will be.”
Advocacy is another area where Napolitano is deeply engaged. He
“
is vocal about issues affecting first-time homebuyers, including land transfer taxes and access to longer amortizations.
“There are supposed to be programs in place to help young people,” he says, “but it’s still too expensive for a lot of them to own a home.”
Despite his leadership roles, Napolitano remains an active mortgage agent, guided by a simple principle: honesty above all else.
“I don’t ever want to do a mortgage for a client without doing what’s right for them,” he says. “Clients appreciate truthful advice – even if it means a deal doesn’t go through.”
That commitment also informs his strong views on licensing and professionalism.
“My biggest beef is that it’s too easy to get into this industry,” says Napolitano. “You shouldn’t be able to take a short course and start giving mortgage advice without proper training.”
B.C. broker Sharon Davis’s dedication to community service has shaped both her career in mortgage brokering and her belief that small, intentional acts can make a big difference.
BY SAMANTHA ASHENHURST
For Sharon Davis, the path into mortgage brokering didn’t begin with a grand plan or a long-term career strategy: It started at the end of her driveway in Port Moody, B.C., with a casual conversation and a cold drink shared among neighbours.
“One evening, as I finished mowing the lawn, I was chatting with my neighbour over a cold bevy,” Davis says. “He asked, ‘So, what are you going to do when your youngest goes to kindergarten?’”
At the time, Davis had spent eight years at home raising her children and assumed she would return to the food and beverage industry, where she’d built her career in food service. Her neighbour, Alan Schmelzel, a mortgage broker, had a different idea.
“He looked at me and said, ‘You should be a mortgage broker,’” she says.
Davis initially laughed off the suggestion, but when Schmelzel asked what she wanted from a job – the ability to help people, flexibility, unlimited income potential, and space to keep her family first – that got her thinking.
“Once I answered, Alan said, ‘OK, you should definitely be a mortgage broker. Pass the course and you can hang your license in my office,’” she says.
Davis did just that, joining the industry in the mid-2000s. More than two decades later, she’s worn many hats: broker, managing broker, franchise owner and back again. These days, she works alongside her son (and succession plan), Matthew, at Davis Mortgages, a boutique brand they launched under DLC Producers West in 2024.
“I say I’m back to ‘just’ being a broker with intention,” says Davis. “That’s really where I want to be.”
While mortgage brokering has been a central part of Davis’s professional life, her identity outside of work has long been shaped by something else entirely: volunteerism.
“I’ve done volunteer work all my life,” she says. “Even when I was a kid, I used to ride my bike to The Salvation Army and read to seniors. I think it’s just part of community.”
The mindset of giving back followed her into adulthood. Over the years, Davis has volunteered as a hockey tournament director, managed her children’s sports teams, served as a block captain for the Canadian Cancer Society’s April campaign for more than a decade, and spent many Christmases wrapping gifts for charity at Coquitlam Centre.
Everything you do –with clients, friends, family, or strangers – you lead with goodness and a willingness to help. “
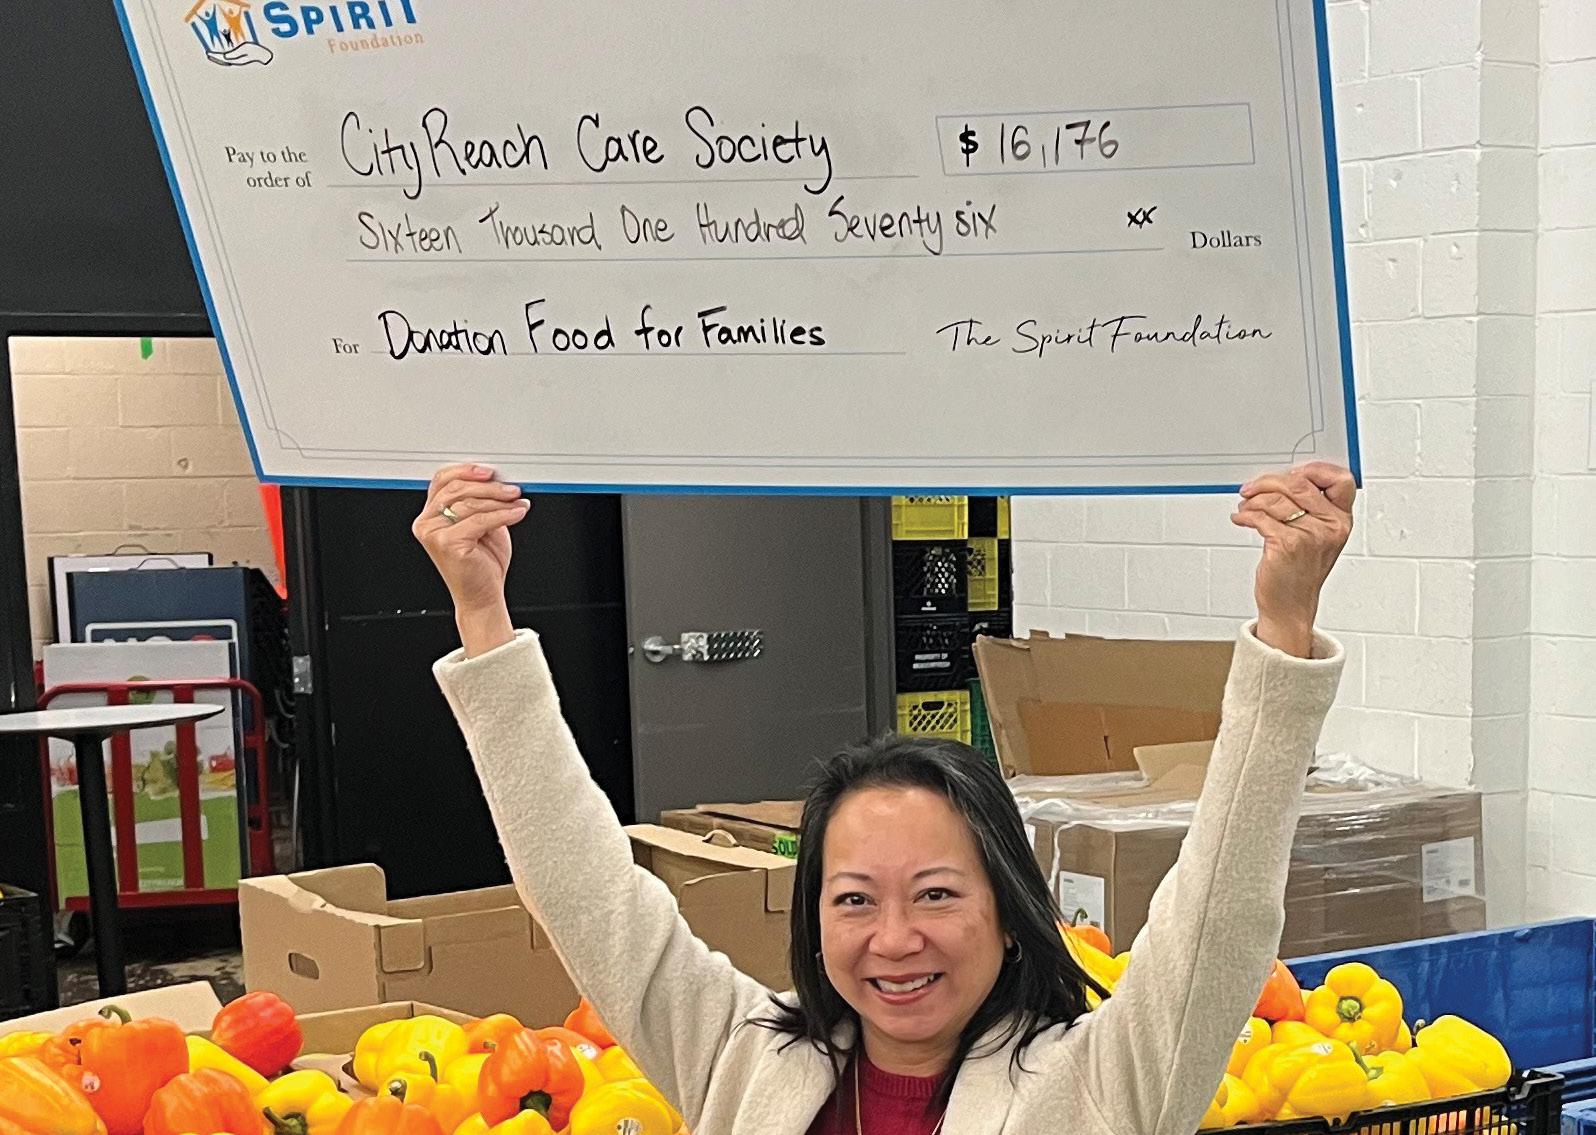
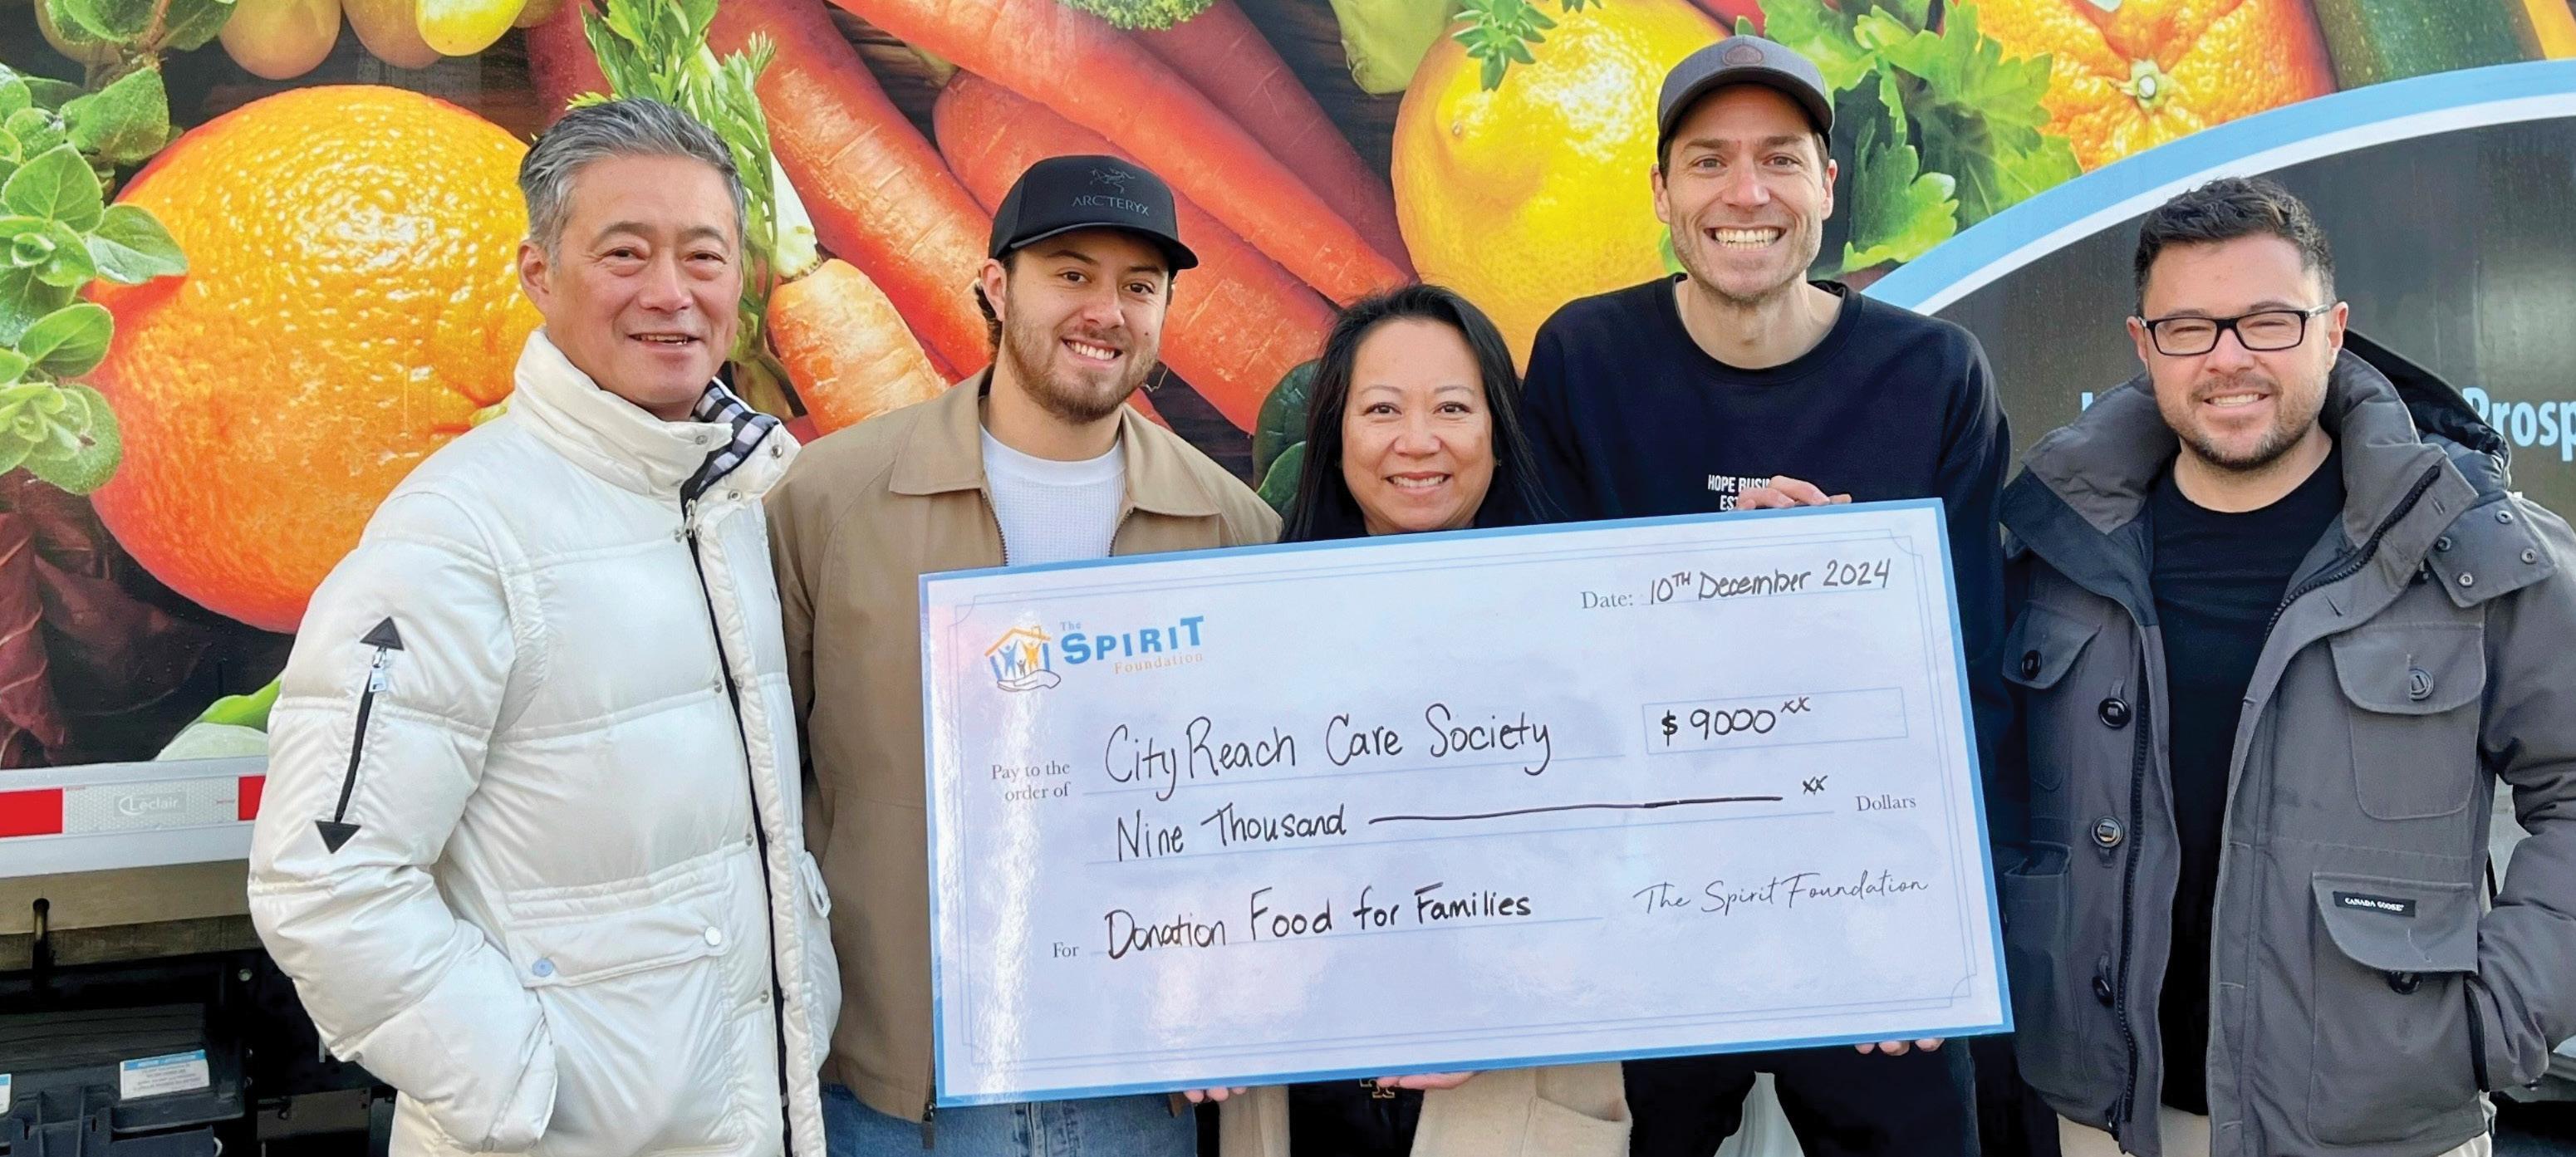
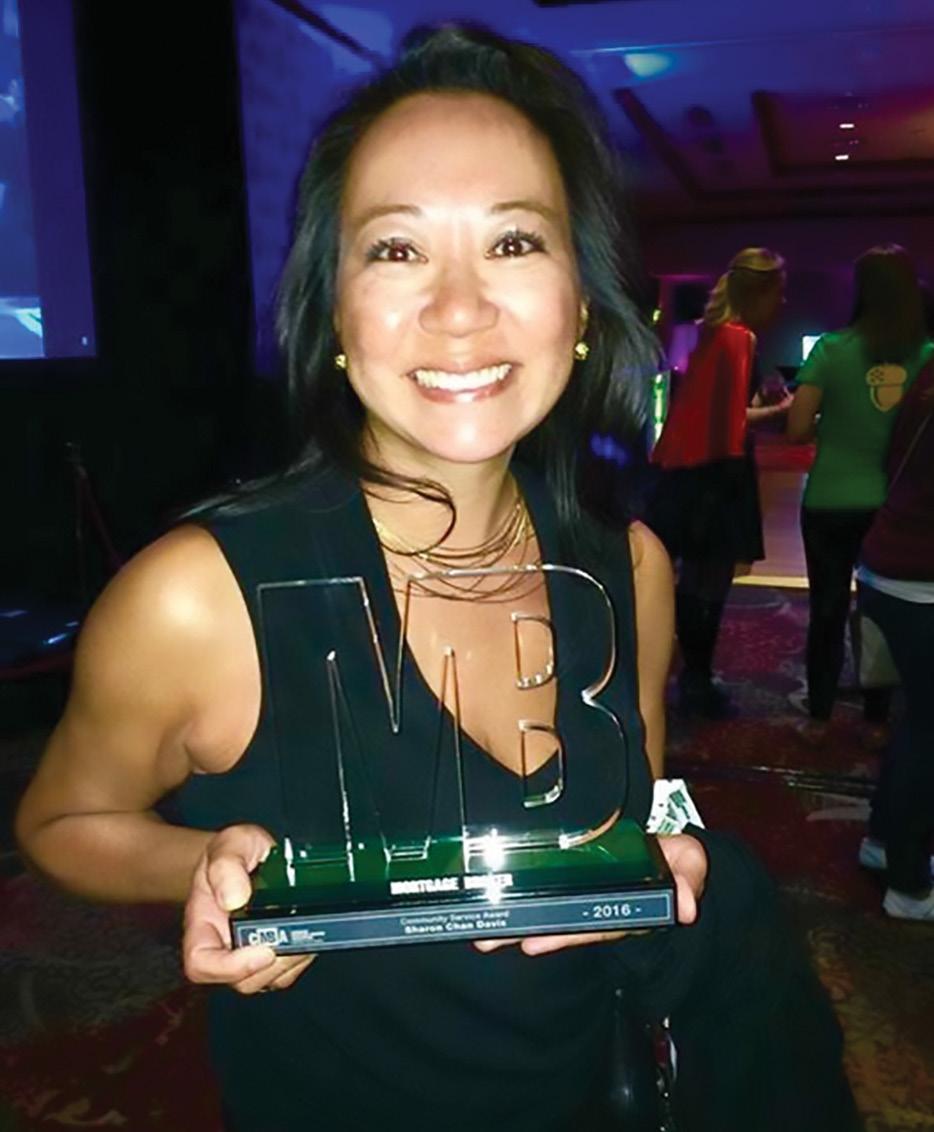
a two-time recipient of the MB Community Spirit Award, winning in both 2016 and 2022; Celebrating another CityReach Care Society donation.
This lifelong commitment eventually led Davis to deeper involvement with the Spirit Foundation, a charitable organization connected to the mortgage industry that focuses on supporting small, local charities.
When she joined the industry, friends working with City Wide Mortgage Services had already launched the foundation. Davis initially helped by participating in events, then organizing them, and eventually stepped into a leadership role.
“It was just kind of a natural progression,” she says. “I’ve been a director on the foundation for about 12 years now. It’s super fun and feels really good.”
The Spirit Foundation’s mission is simple but powerful: make tangible, local impact.
“Our ‘small’ efforts can raise $10,000 or $15,000 or $20,000 at an event,” says Davis. “For smaller charities, that can make a huge difference – and it’s a difference you can really see.”
She points to initiatives like funding job retraining for individuals from Vancouver’s Downtown East Side through Mission Possible, building playgrounds for the YMCA, feeding seniors in Vancouver’s Chinatown and supporting organizations that are visible and active in the community.
Two years ago, the foundation revived a hockey tournament fundraiser, most recently
supporting CityReach Care Society, a Lower Mainland organization that provides perishable food to those in need.
“They have a 10X impact model,” says Davis. “So, for every dollar we raised, they gave out $10 of food.”
The event raised $21,000, with more than $16,000 donated — translating into more than $160,000 worth of food for local families.
“Small, but impactful impressions are what we’re hoping to make,” says Davis.
Another cornerstone initiative is the Spirit Foundation’s annual Day of Caring, now in its 13th year. This past year, volunteers collected gently used warm clothing and footwear, assembled roughly 600 bag lunches, and distributed them directly to people in Vancouver’s Downtown East Side and local shelters.
“It’s an opportunity for people to come together and be grateful for what we have,” says Davis.
When it comes to balancing a full-time career with extensive volunteer commitments, Davis says it comes down to intention.
“If something is important, you make time for it,” she says. “You purposely make time for your family, for old friends and for giving back.”
Plus, says Davis, volunteerism doesn’t always have to be large-scale.
“You could do nice things and be generous and kind every day,” she says. “That in itself is a baby act of volunteerism.”
These values carry directly into the way Davis works with clients.
“Everything you do – with clients, friends, family, or strangers – you lead with goodness and a willingness to help,” she says. “It sounds silly, because we’re not achieving world peace, but if you could, this might be how you get there.”
For Davis, service isn’t about recognition or return. It’s about connection, and the quiet ripple effect of showing up for others.
“That feeling of helping someone feels good,” she says. “For people who are passionate about volunteerism, the drive is really inside you. That feeling becomes a bit addictive – in the best possible way.”
This interview with Sharon Davis continues our series Brokers Off-the-Clock. In every issue, we ask a mortgage broker to tell us what they like to do when they’re not behind a desk. Be it travelling to exotic places, supporting community initiatives or being involved with sports, we want to know how you unwind. Would you like to be profiled in a future edition – or suggest a fellow mortgage broker? Contact info@cmba-achc.ca
BY ROY MILLEN, SAM ADKINS AND NICHOLAS TOLLEFSON
Two recent court decisions have brought renewed attention to the question of whether Aboriginal title can apply to privately owned (or “fee simple”) land. These cases provide different answers to this consequential question and will have implications for the ongoing resolution of Aboriginal title claims across Canada.
In J.D. Irving, Limited et al. v. Wolastoqey Nation (Wolastoqey Nation), the New Brunswick Court of Appeal refused to declare Aboriginal title over land held by private landowners, finding that a declaration of Aboriginal title would confer rights that cannot coexist with private land ownership. In the Court’s view, recognizing Aboriginal title over privately owned lands would “sound the death knell of reconciliation with the interests of non-Aboriginal Canadians.”
In contrast, in Cowichan Tribes v. Canada (Attorney General) (Cowichan Tribes), the Supreme Court of British Columbia considered the same question but came to the opposite conclusion. The Court declared Aboriginal title over an area that included privately owned land, holding that Aboriginal title and fee simple ownership can legally coexist. The Court did not, however, address the implications of its declaration of Aboriginal title on the fee simple rights of private third-party landowners, including how competing exclusive interests in land may co-exist in practical terms.
These divergent paths raise implications for private landholders, Indigenous nations, lenders and infrastructure owners across Canada. The guidance of the Supreme Court of Canada will ultimately be required to resolve these important questions.
Aboriginal title has existed in Canadian law for many years. Aboriginal title is a collective, constitutionally protected interest in land, which is recognized and affirmed in section 35 of the Constitution Act, 1982. Aboriginal title arises from the regular and exclusive occupation of land by an Indigenous group prior to the Crown’s assertion of sovereignty over the lands that now comprise Canada.
Two previous court decisions and one court order have declared Aboriginal title over Crown (public) lands.
In the Supreme Court of Canada’s leading decision on Aboriginal title in 2014, Tsilhqot’in Nation v. British Columbia
(Tsilhqot’in), the Court upheld a declaration of Aboriginal title over Crown land located in a large remote area of central British Columbia. The Court also confirmed that Aboriginal title provides significant rights over land, including the right to control, possess, use, economically benefit from and proactively manage the land.
In the British Columbia Supreme Court’s 2024 decision in The Nuchatlaht v. British Columbia (Nuchatlaht), the Court declared Aboriginal title over a group of specific sites located on Nootka Island, off the west coast of Vancouver Island in British Columbia. This decision was made after the Court had previously dismissed the Nuchatlaht’s prior claim to a much larger area of 201-square kilometers on Nootka Island.
In both the Tsilhqot’in and Nuchatlaht cases, the claimant Indigenous groups excluded private lands from the scope of their claim. As a result, the question of whether Aboriginal title can exist over private land was left unanswered.
In September 2025, the British Columbia Supreme Court granted an order entered by consent of the Haida Nation, British Columbia and Canada declaring that the Haida Nation has Aboriginal title over all of Haida Gwaii. However, the parties also agreed that the declaration does not derogate from fee simple interests on Haida Gwaii, and the Haida Nation consents to fee simple interests continuing.
Against this backdrop, many legal commentators have highlighted the practical incompatibility between two forms of exclusive ownership over the same land. Others suggested frameworks where rights might be reconciled through Crown-led negotiations, with remedies limited as against private third-party landowners. From a practical perspective, provincial land registries uniformly treat Aboriginal title as a non-registrable interest in land.
The Cowichan Tribes and Wolastoqey Nation decisions represent the first attempts by Canadian courts to answer this important question directly.
Wolastoqey Nation
In Wolastoqey Nation, the New Brunswick Court of Appeal set aside preliminary orders of the New Brunswick Court of King’s Bench, which had allowed the Wolastoqey to pursue a declaration of Aboriginal title over private fee simple lands owned by nonCrown parties. In overturning the decision of the court below, the Court of Appeal made several key points.
The Court reasoned that a declaration of Aboriginal title over private fee simple lands would vest rights of exclusive possession, control and economic benefit in the title-holding group, which the
Court viewed as irreconcilable with the rights held by fee simple owners. In the Court’s view, those interests cannot practically coexist in the same land.
The Court reaffirmed that Aboriginal title is recognized and affirmed under section 35 of the Constitution, and that the Crown remains responsible for reconciling Indigenous rights with broader public interests. However, it reasoned that declaring Aboriginal title over privately held lands would not further reconciliation because it would create two competing rights of exclusive ownership – an irreconcilable conflict. On this basis, the Court struck the portions of the Wolastoqey’s claim which sought a declaration over private lands.
However, the Court allowed the Wolastoqey to pursue claims against the Crown for damages and compensation upon a finding of Aboriginal title over private lands. The Court emphasized the legal distinction between a declaration and a finding, with the former having implications only for the Crown and the Wolastoqey, as the proper parties to the litigation. In practical terms, any such finding would be backward-looking as to Aboriginal title and without consequence to private landowners, but with forwardlooking consequences for the Crown and the claimant.
Finally, the Court concluded by endorsing the “commonsensical and reconciliation-friendly” view that justice does not favour the dispossession of innocent private landowners. The Court found that compensation by the Crown is the appropriate remedy in cases of findings of Aboriginal title in private lands.
Wolastoqey has publicly stated it intends to appeal the decision to the Supreme Court of Canada.
In Cowichan Tribes, the British Columbia Supreme Court came to a different conclusion. After a 513-day trial, the Court issued an 863-page
decision containing extensive and detailed evidentiary findings. The Court declared Aboriginal title over a historic Cowichan village site on the south arm of the Fraser River, in modern-day Richmond, British Columbia. The site’s footprint included both Crown and privately owned land.
The Court found that Aboriginal title and fee simple can legally coexist, rejecting the argument that fee simple interests automatically displace Aboriginal title. It characterized Aboriginal title as a “senior,” constitutionally protected interest that burdens the land, including land held in fee simple.
Importantly, the Court found that Aboriginal title does not necessarily defeat fee simple title. Where fee simple and Aboriginal title coexist, the Crown must take steps to reconcile those interests. Because both Aboriginal title and fee simple include rights of exclusive use, the Court acknowledged that the day-to-day exercise of one right may have to yield to the other unless and until reconciliation occurs. In practical terms, this means that the current fee simple owners’ exclusive use remains effective unless and until modified by negotiation, legislation, expropriation, remedial orders or other lawful means. The court emphasized that it is the Crown (not private owners) that bears primary responsibility for reconciling these competing interests.
In contrast to Wolastoqey Nation, which prevented any adverse impacts to private land rights, the Cowichan Tribes decision places private land rights in a zone of uncertainty. To be clear, the Court in Cowichan Tribes did not displace the current private landowners. The Court’s remedy was effectively directed against the Crown to resolve the issue through negotiations with the Cowichan. Nevertheless, the Court did not limit the possibility of further litigation (if the negotiations are unsuccessful) that could result in a wide range of potential outcomes that could affect the use, governance and value of the land.
The Court found that Aboriginal title and fee simple can legally coexist, rejecting the argument that fee simple interests automatically displace Aboriginal title. It characterized Aboriginal title as a “senior,” constitutionally protected interest that burdens the land, including land held in fee simple.
The Cowichan Tribes decision has been appealed to the British Columbia Court of Appeal, but there has been no date set yet for the hearing of the appeal. Blakes is counsel for Musqueam Indian Band on the appeal, seeking to overturn the trial judgment.
There are other claims relating to Aboriginal title across Canada, and, given the differing answers provided by the courts of New Brunswick and British Columbia, there are practical implications for businesses and private landowners that are of national interest. Two immediate implications with respect to land transactions are:
• Enhanced due diligence on significant private land transactions: Due diligence regarding potential Aboriginal title claim risks may be called for on significant acquisitions or long-term leases of private lands. Where diligence identifies potential risks, appropriate representations, warranties or indemnities may provide tools to manage that risk.
• Importance of location: Whether a court will consider a declaration of Aboriginal title over private land may now depend on the province in which the land is located –subject to further appeals. Ultimately, the question of the application of Aboriginal title to private land will likely require a nationally binding decision from the Supreme Court of Canada.
This article is republished with the permission of Blake, Cassels & Graydon LLP, a leading Canadian law firm with offices in Toronto, Calgary, Vancouver, Montréal, Ottawa, New York and London. Roy Millen and Sam Adkins are Partners in the Firm’s Vancouver office and Nicholas Tollefson is an Associate in the Firm’s Vancouver office. More information: blakes.com
Recognition. Insight. Connection. The CMBA Ontario Gala & Conference return April 202 6.
Join Ontario’s mortgage professionals for two days that matter. From celebrating leadership and achievement to gaining insights you can use immediately. If you attend one industry event this year, make it this one.
GALA & AWARDS | APRIL 22 CONFERENCE & TRADE SHOW | APRIL 23
SCAN TO REGISTER Member pricing available

BY CARLA GILES, MBA, CAE, CEO OF CMBA-BC, MBIBC, EXECUTIVE DIRECTOR, CMBA NATIONAL
Mortgage brokers in British Columbia are navigating a period of significant regulatory change – from the transition to the Mortgage Services Act (MSA) to evolving expectations around governance, supervision and consumer protection. Another important regulatory development is now firmly on the horizon: the introduction of the Restricted Insurance Agency (RIA) licence, which will directly affect mortgage brokerages that offer certain insurance products as part of their business activities.
While the new licence regime does not come into force until January 1, 2027, the groundwork is being laid now. Understanding how this framework works – and how it may apply to your brokerage – will be important well before application windows open.
The RIA licence is part of a broader effort by the Province to strengthen consumer protection and increase confidence when insurance products are sold alongside other goods or services.
In 2019, the B.C. government amended the Financial Institutions Act to enable a licensing framework for incidental sales of insurance –insurance sold by non-insurance businesses in connection with their usual business activities. Historically, many of these point-of-purchase insurance sales were exempt from licensing requirements and formal regulatory oversight.
In practice, this meant that consumers could purchase insurance products in a range of contexts – such as vehicle dealerships, travel agencies and mortgage brokerages – without those sellers being subject to consistent regulatory standards. The new RIA
framework is intended to introduce greater consistency, transparency and oversight across these activities.
The Province has tasked the Insurance Council of British Columbia with designing, implementing and overseeing the new Restricted Insurance Agency licence program. This includes:
• Developing the regulatory framework and licence requirements
• Consulting with stakeholders
• Establishing rules and guidance
• Issuing licences and overseeing ongoing compliance
The licence program is expected to launch in November 2026, with applications accepted ahead of the January 2027 effective date.
The Insurance Council of British Columbia is currently consulting on a package of proposed Council Rule changes to support implementation of the RIA licence. The consultation is open until April 27, 2026, and brokerages that may be impacted may wish to review the proposed changes and consider providing input.
In B.C., selling insurance as a primary business activity requires full agency licensing, along with individually licensed insurance agents. Standard licences (for general insurance, life insurance, or accident and sickness insurance) allow the sale of a broad range of products within those classes.
The RIA licence, by contrast, is designed specifically for incidental insurance sales – where insurance is not the organization’s primary business.
Under this model:
• A business obtains a restricted insurance agency licence
• Employees or contractors may sell specific insurance products named in regulation
• Individual sellers do not need to hold their own insurance licences
• Sales are limited to prescribed products and must occur within defined parameters, subject to training, oversight and compliance requirements
This approach recognizes the incidental nature of these insurance sales while still ensuring appropriate consumer protections are in place.
Mortgage brokerages are explicitly listed in the Restricted Insurance Agent Licence Regulation as a class of business that may require a licence. Specifically, mortgage brokerages that sell credit protection insurance as an incidental product alongside mortgage services will fall within the scope of the new regime.
This does not mean all brokerages are affected. The licence requirement applies only where the brokerage itself is engaged in the sale of the insurance products named in the regulation. However, for those that do sell credit protection insurance, the change is material: activities that were previously exempt from licensing will now require formal authorization.
The regulation identifies specific “classes of persons” (types of businesses) that must hold an RIA licence if they sell certain insurance products. Mortgage brokerages appear on this list alongside vehicle dealers, travel agents, trust companies and other non-insurance businesses.
For mortgage brokerages, the licensing requirement depends on whether the brokerage is directly involved in selling insurance. Brokerages that sell credit protection insurance as an incidental product alongside mortgage services will be required to obtain a restricted insurance agency licence. Brokerages that do
not sell insurance products are not required to hold this licence.
Importantly, continuing to sell regulated insurance products without applying for a licence after the transition period will be considered non-compliant with the Financial Institutions Act and may be subject to enforcement action.
Although 2027 may feel some distance away, the transition timeline is clearly defined:
• November 2026: Insurance Council expects to begin accepting applications for the Restricted Insurance Agency licence.
• January 1, 2027: The RIA Licence Regulation comes into effect. Businesses newly offering regulated incidental insurance after this date must already hold a licence.
• March 31, 2027: Deadline for businesses that were previously selling insurance under licensing exemptions to have submitted an application in order to continue those sales.
For mortgage brokerages currently offering credit protection insurance, March 31, 2027 is the key date to plan around.
For brokerages that fall within scope, the RIA licence introduces a new layer of regulatory accountability, particularly around governance, internal controls and oversight.
While detailed licence conditions are still under development, brokerages should anticipate requirements related to:
• Designating a responsible individual for the licence
• Maintaining appropriate disclosures and records
• Ensuring staff involved in insurance sales are properly trained and supervised
• Renewing the licence annually and complying with Insurance Council rules
For principal brokers and brokerage leadership, this reflects a broader regulatory theme: oversight responsibilities increasingly extend
beyond core mortgage activities to related or ancillary services offered by the firm.
The introduction of the RIA licence should not be viewed in isolation. As with recent changes under the MSA, it reflects a broader regulatory shift toward clearer accountability, proportionate oversight, and consistent consumer protections across financial services activities.
For mortgage brokers already adapting to the MSA, the direction will feel familiar: regulators expect firms to understand the full scope of their activities – and to manage those activities responsibly.
The RIA licence will not affect every mortgage brokerage in B.C. For those that do offer credit protection insurance, however, it represents a meaningful regulatory change that warrants early awareness.
With application windows opening in late 2026 and compliance expectations following soon after, thoughtful planning will be key. As additional guidance is released, brokerages will have opportunities to assess how insurance offerings fit within their broader business model and regulatory obligations.
The Canadian Mortgage Brokers Association – British Columbia will continue to engage with the Insurance Council of British Columbia and share updates, guidance, and relevant resources with members as more information becomes available.
For detailed and up-to-date information on the RIA licence framework – including timelines, application requirements and guidance materials – visit the Insurance Council of British Columbia website (insurancecouncilofbc.com/ria/).
Mortgage brokerages can also register for the Insurance Council’s RIA mailing list to receive updates, consultation notices and key information as the regime is developed and implemented.

Grow Your Expertise: Access top industry courses and webinars
Expand Your Network: Connect with brokers and lenders nationwide
Advance Your Career: Gain tools and insights to stay ahead
Shape the Industry: Be a voice for mortgage professionals with CMBA National
Ready to thrive in the mortgage industry? Join us today!