• Generally, employees working 20+ hours/week and all 49% employees working 17.5 hours/week. 49% employees are not eligible to enroll for disability benefits.
• Specific plan eligibility is listed on the top of each page. Specific employee and dependent eligibility rules are governed by each plan’s policy document/certificate, which is available on your employee benefits website, or by contacting Campus Benefits.
Enrollment
• The first step is to review your current benefit elections.
• Verify your personal information and make any changes if necessary.
• Make your benefit elections as well as list your beneficiaries.
• Once you have made your elections, you will not be able to make changes until the next open enrollment period unless you have a qualified life event.
• Login instructions available on the Campus Benefits Enrollment page within this guide.
When Do Benefits Begin
• The effective date of coverage for benefits depends on your hire date. Typically, benefits will begin the first of the month following 30 days of employment.
• Employees must be actively at work on the effective date of coverage
How to Make Changes
• Once you make your benefit elections as a new hire or during Open Enrollment, you cannot make changes to those elections until the next Open Enrollment period.
• The only exception is a qualifying life event which allows you to make eligible changes to your benefit elections during the plan year.
• Please contact Campus Benefit to make a qualifying life event change.
IMPORTANT REMINDERS - TAKE ACTION
• Eligibility for benefits enrollment must take place within 30 days of your hire date.
• Remember: Please review and/or update beneficiaries annually for all benefits including, Basic Life, Voluntary Term Life & AD&D and Permanent Life policies.
• Important: Review and Understand Guaranteed Issue Options (New Hires).
• Life Events - You are required to submit any life event changes for you and eligible dependents within 30 days of an event.
• This Guide - This guide is presented for illustrative purposes only and is not intended to offer insurance advice. It is important you review each benefit’s summary plan description (SPD) and other carrier materials before making any selections.
There are two separate benefit enrollments:
1. Campus Benefits Voluntary Benefits
(View Campus Benefits Enrollment page for detailed enrollment instructions)
2. State Health Benefit Plan Medical Insurance
(View the SHBP pages for instructions)
How to Enroll in Campus Benefits Voluntary Benefits
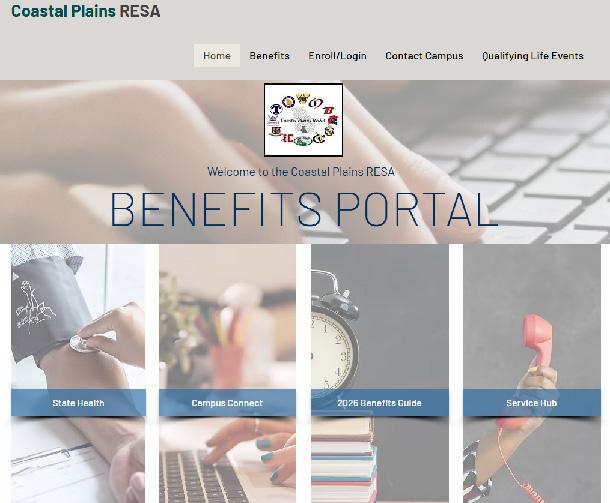
1. Visit www.cpresabenefits.com
2. Select the “Enroll” tab or the “Campus Connect” tab
3. Follow the on-screen instructions OR
4. Contact Campus Benefits at 1.866.433.7661, opt 5
• Plan year is 1/1-12/31
• Annual open enrollment occurs in the Fall
Company Identifier: CPR14
TERMS & DEFINITIONS
Definitions Disclaimer: The definitions below are for illustrative purposes only. Actual plan definitions are governed exclusively by the provider contract and associated Summary Plan Description (SPD). Please visit www.cpresabenefits.com for each plans policy document/certificates and actual benefit definitions.
Age Reduction - A reduction of the face amount of your group insurance policy when you reach a certain age. Please review the age reductions on the Basic Life Insurance and Voluntary Term Life Insurance.
Beneficiary - A life insurance beneficiary is the person or entity that will receive the money from your policy’s death benefit when you pass away. When you purchase a life insurance policy, you choose the beneficiary of the policy. Please update your beneficiaries as needed for your Basic Life Insurance, Voluntary Term Life Insurance and/or Permanent Life Insurance.
Conversion - The option on your term life policies to convert your term life insurance policy into a permanent life insurance policy. Please refer to the plan certificate for detail on converting your term life coverage. Note: converting your term life policy will change the rate.
Dependents – The definition of eligible dependents vary by insurance carrier. Eligible dependents may include your spouse and taxable dependent children who are under the age of 26. Child marital status will impact benefit eligibility. Please refer to each plans policy document for verification of dependent eligibility.
Elimination Period - A period of consecutive calendar days that you must be out of work before you are eligible to receive benefits. Refer to the Disability page for more details.
Flexible Spending Accounts - An employee benefit which allows you to set aside money from your paycheck, pre-tax, to pay for healthcare and dependent care expenses. There are two types of flexible spending accounts: A Health Care FSA can cover medical, dental or vision expenses that you would otherwise pay for out of pocket. A Dependent Care FSA, also known as a Dependent Care Assistance Program (DCAP), covers employment-related expenses for child care. Please review the Flexible Spending Account pages for additional details.
Guaranteed Issue - A plan’s guaranteed issue (GI) is the amount of life insurance available to an employee without having to provide Evidence of Insurability, or EOI/ no health questions. This is particularly helpful if you have health issues which may make you otherwise uninsurable. Many of the benefits offered have GI amounts for new hires. Please review these within your new hire window.
Portability – The portability provision allows you to take coverage with you when you leave your place of employment. The portability rate will differ from current plan rates and are determined by the plan carrier at the time of portability. Portability must be completed within a specific time frame. Please refer to the plans policy certificate for details on portability.
Pre-existing Condition - An illness or injury experienced before enrollment in an insurance plan may be considered a pre-existing condition. Pre-existing conditions can include health issues such as cancer, diabetes, lupus, depression, acne, pregnancy, or just about any other health condition you can imagine. Refer to each plans document for pre-existing condition limitations.
Qualifying Life Event Change - A change in your situation — like getting married, having a baby, or losing benefit coverage — that can make you eligible for a Special Enrollment Period, allowing you to enroll in insurance outside the yearly Open Enrollment Period.
SHBP - The State Health Benefit Plan (SHBP) is a division of the Georgia Department of Community Health (DCH). It serves as the state’s administrator of health insurance coverage for state employees, teachers, public school employees, retirees, and former employees, and covered dependents.
Term Insurance VS. Permanent Life Insurance - There are two basic life insurance options offer through your employer: term and permanent. The term life offered is a group policy which allows you to get more benefit for less premium. Permanent lasts your entire lifetime. Term Life and Permanent Life work best when used in conjunction with one another. Term Life can protect your family in your younger working years and Permanent Life can protect your family in your retirement years. Please review the Life Insurance 101 pages for more details. Voluntary Benefits - Products offered by your employers but paid by employees via payroll deductions. The voluntary benefits within this guide are life insurance, disability insurance, vision insurance, dental insurance, critical illness insurance, cancer insurance, accident insurance, telemedicine insurance, and legal insurance.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
DISABILITY INSURANCE
What is Disability Insurance? A type of coverage that replaces a portion of your income if injury or illness prevents you from working. It provides financial security for you and any loved ones who may depend on your most valuable asset — your ability to earn a paycheck. You may also hear disability insurance referred to as disability income insurance or income protection.
Eligibility: Eligible employees with the exception of 49% employees, as described on page 1 of this benefits guide
• Coverage through OneAmerica
• Employee must be actively at work on the effective date
• Must exhaust all sick-leave prior to receiving a benefit
• No Health Questions- Every Year! (Pre-existing condition will apply for new participants)
Long Term Disability Quick Summary
Elimination Period
Benefit Duration
Benefit Percentage (monthly)
Benefits begin on the latter of the 91st day of an injury or illness or the exhaustion of sick leave
Covers accidents and sicknesses up to Social Security normal age of retirement (Please note exclusions or limitations may apply, see plan certificate for details)
60% of your gross monthly salary
Maximum Benefit Amount Monthly $6,000
Pre-Existing Condition
Rates
3 months / 12 months
Illness or injury for which you received treatment the 3 months prior to your effective date will not be covered for the first 12 months (applies to new enrollees only)
Long-Term Disability
Divide Annual Salary by 12
Divide by 100
Multiply by Rate (Based on Age)
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the
See important claims information on Service Hub page.
LIFE INSURANCE
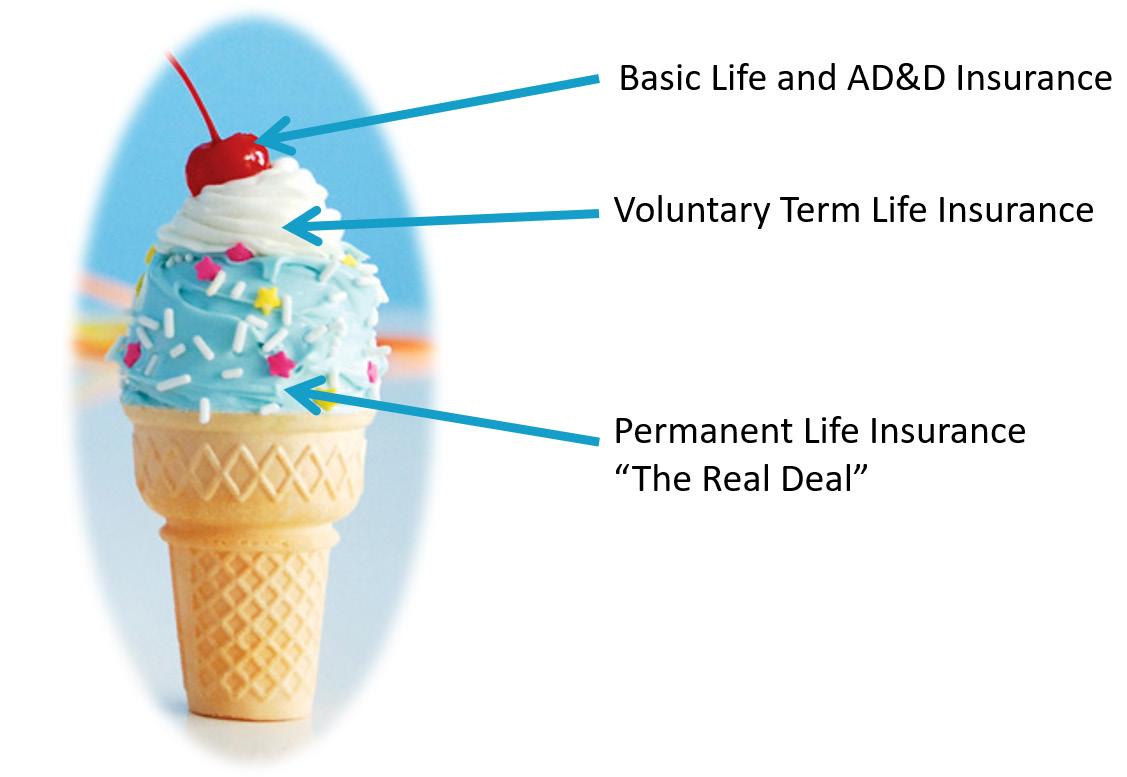
The need for life insurance depends on each individual life situation. If loved ones are financially dependent on you, then buying life insurance coverage can absolutely be worth it. Even if you don’t have financial dependents yet, life insurance can be a valuable solution for making death easier on a family (at least financially). There are two voluntary life insurance options offered through your employer: Term Life Insurance and Permanent Life Insurance. Below is an overview of the differences.
Term Life and Permanent Life work best when used in conjunction with one another. Term Life can protect your family in your younger working years and Permanent Life can protect your family in your retirement years.
INSURANCE 101
TERM LIFE INSURANCE
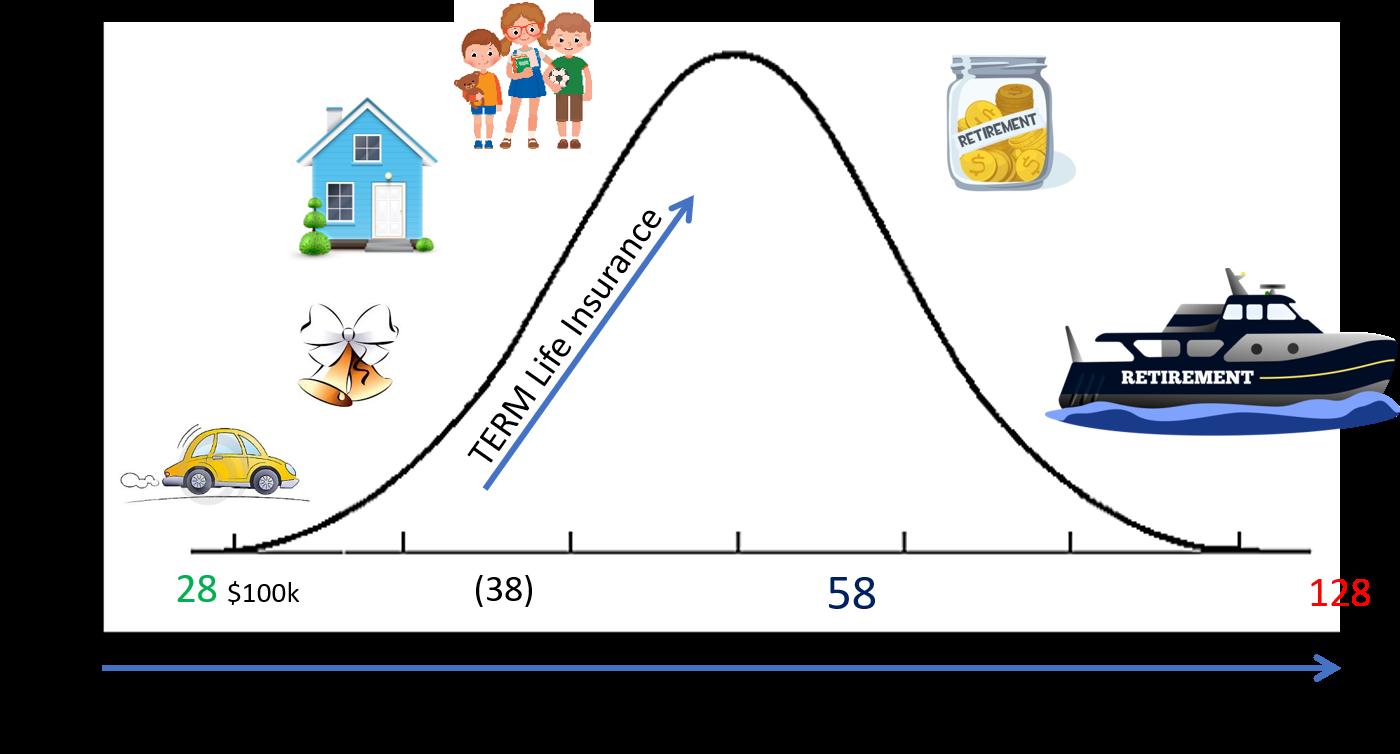
Term Life insurance is illustrated on the bell curve below. The term life offered is a group policy which allows you to get more benefit for less premium.
• Term life insurance is for the unexpected death
• Includes an Accidental Death & Dismemberment Benefit
• Term life insurance is flexible and allows changes to your benefit amount each year depending on life changes. For example, as you get married and have children the need for term insurance often increases. As you near retirement, the need for term life insurance often decreases.
• Coverage is portable at retirement or if you leave the employer (premium will change)
• Premiums are based on age and increase as you get older
PERMANENT LIFE INSURANCE
Permanent Life Insurance is illustrated above along the bottom of the graph with a straight blue arrow.
• Permanent life insurance offers a stable premium along the lifetime of the policy
• Permanent life offers a level premium and is meant to take into retirement
• Permanent life is an issue age policy and is based on the age when the policy is issued
• This is an individual plan you can take with you regardless of where you work
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
BASIC LIFE INSURANCE
What is Basic Life Insurance and AD&D? A financial and family protection plan paid for by Coastal Plains RESA which provides a lump-sum payment, known as a death benefit, to a beneficiary upon the death of the insured. AD&D coverage is included as a part of life insurance benefits, and will pay out a lump-sum death benefit in the event you die accidentally or pass away later as the direct result of an accident. This plan also has a dismemberment benefit which provides an additional lump sum payment if an insured becomes dismembered in an accident.
Eligibility: Eligible employees as described on page 1 of this benefits guide
• Coverage through OneAmerica
• Must be actively at work on the effective date
• Waiver of premium: waives the policyholder’s obligation to pay premiums should they become seriously ill or disabled prior to age 60
• It is important to review beneficiaries each year!
Basic Life/AD&D Rates - Paid for by Coastal Plains RESA
VOLUNTARY TERM LIFE & AD&D INSURANCE
What is Voluntary-Term Life and Accidental Death & Dismemberment Insurance?
A financial protection plan which provides a cash benefit to a beneficiary upon the death of the insured. Proceeds can be used to replace lost potential income during working years and help ensure your family’s financial goals will still be met. AD&D coverage is included as a part of life insurance benefits, and will pay out a lump-sum death benefit in the event you or a covered loved one die accidentally or pass away later as the direct result of an accident. This plan also has a dismemberment benefit which provides an additional lump sum payment if an insured becomes dismembered in an accident.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26)
• Coverage through OneAmerica
• Must be actively at work on the effective date
• If electing for the first time outside of the initial open enrollment period, health questions will be required for employee and spouse
• Employee must elect coverage for themselves in order to cover spouse and/or children
• Dependent coverage cannot exceed 100% of employee amount
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
Multiply above rate factor by desired benefit amount to determine premium. For Example: $100,000 Benefit for Employee Only at Age 30 0.129 x 100 = $12.90 premium*
PERMANENT LIFE INSURANCE
What is Permanent Life Insurance? Coverage that provides lifelong protection, and the ability to maintain a level premium.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & dependent children (up to age 26)
• Coverage through Colonial Life
• Must be actively at work on the effective date
• Underwriting may be required. Coverage is not guaranteed
• Permanent life offers the flexibility to meet a variety of personal needs while allowing employees the choice of benefit and premium amounts which fit their paycheck and lifestyle
• Keep your coverage, at the same cost, even if you retire or change employers
(Ages 15 - 79)
Child (0 - 17) Juvenile Policy Child (18-26 if a full-time student) Adult Policy
GUARANTEED ISSUE (FIRST TIME ELIGIBLE/NEW
Spouse & Child Simplified Issue Amounts (One Health Question) may be available. Contact Campus Benefits for Additional Questions.
for Paid up to age 70 or age 100 Terminal Illness accelerated death benefit for up to 75% (Up to $150,000)
Cost of coverage is based on the level of benefit you choose and your age. Please consult with a Campus Benefits Counselor or log into the enrollment system for rate details.
EMPLOYEE ASSISTANCE PROGRAMS
What is an EAP? A program offered at no cost to Coastal Plains RESA employees that provides guidance with personal issues, planning for life events or simply managing daily life which can affect your work, health and family.
OneAmerica EAP
Eligibility: Eligible employees as described on page 1 of this benefits guide, their household members and unmarried children up to age 26
• Coverage through OneAmerica
• Provides support, resources, and information for personal and work-life challenges
• Receive up to three counseling sessions per issues, per year
• CALL 1.855.387.9727 or visit www.guidanceresources.com, WEB ID: OneAmerica3
Confidential Counseling
• Helps employees address stress, relationship and other personal issues for you and your family
• Sessions with highly trained master’s and doctoral level clinicians
• Stress anxiety and depression
• Relationship/marital conflicts
• Problems with children
Work-Life Solutions
• Job pressures
• Grief and loss
• Substance abuse
Work-Life Specialists do the research for you, providing qualified referrals and customized resources:
• Child and elder care
• Moving and relocation
• Making major purchases
• College planning
• Pet care
• Home repair
Financial Information and Resources
Speak by phone with a Certified Public Accountant and Certified Financial Planners on a wide range of financial issues, including:
• Getting out of debt
• Credit card or loan problems
• Tax questions
Online Resources
• Retirement planning
• Estate planning
• Saving for college
• Timely articles, HelpSheets, tutorials, streaming videos and self-assessments
• Child care, elder care, attorney and financial planner searches
Free Online Will Preparation
• EstateGuidance lets you quickly and easily write a will on your computer
• Go to www.guidanceresources.com and click on EstateGuidance link
• Follow the prompts to create and download your will at no cost
• Name an executor to manage your estate
• Choose a guardian for your children
• Specify your wishes for your property
• Provide funeral and burial instructions
provided at no cost to you.
Disclaimer:
DENTAL INSURANCE
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & dependent children (up to age 26)
• Orthodontics available for children only <19 years old (subject to takeover provision)
• No waiting periods or late entrant penalties
• The chart below is a sample of covered services. Additional information available on your employee benefits website.
VISION INSURANCE
What is Vision Insurance? A health and wellness plan designed to reduce your costs for routine preventive eye care including eye exams and prescription eyewear (eyeglasses and contact lenses).
Eligibility: Eligible employees, as described on page 1 of this benefits guide, spouse, & dependent children (up to age 26)
• Coverage provided by MetLife
• Claims must be submitted within 90 days of service
• The chart below is a sample of covered services. The Plan Certificate is available on your Employee Benefits Website: www.cpresabenefits.com.
(with dilation as necessary)
Contact Lens Fit and Follow-Up (Standard)
Lasik or PRK 15% off retail or 5% off promotional Frames
(See plan certificate for featured frames allowance)
Single Vision, Bifocal, Trifocal, Lenticular
Standard Progressive Lenses
Standard UV Treatment
$200 allowance + 20% off balance
$220 allowance on featured frames ($110 allowance at Costco, Walmart, Sams)
$150 allowance + 20% off balance
$170 allowance on featured frames ($85 allowance at Costco, Walmart, Sams) Lenses
Copay
in Full Standard Scratch Resistant Covered in Full
Standard Polycarbonate Children: Covered in Full Adults: Up to $35 Copay
Standard Anti-Reflective Coating Up to $41 - $85 Copay
Transition Lenses Up to $47 - $82 Copay
Elective Contacts
Contact Lenses
$200 Allowance
to $17 - $33 Copay
$150 Allowance
Medically Necessary Covered in Full after eyewear Copay Frequencies
Exams, Lenses, Contact Lenses and Frames Every 12 mo
2nd Pair Benefit
(Allowance must be purchased on two separate invoices)
Exams and Lenses: Every 12 mo Frames: Every 24 mo
Each covered person can get: 2 pairs of prescription eyeglasses OR 1 pair of prescription eyeglasses & an allowance toward contacts OR Double the contact lens allowance Not Covered
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
*Click on id card for more information and printable version
CRITICAL ILLNESS
What is Critical Illness Insurance? A health and wellness plan in which you receive a lump sum cash payment if diagnosed with one of the specific illnesses on the predetermined list of critical illnesses.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26)
• Coverage through Colonial Life
• Issue Age: Rates lock in at the age you are and do not increase
• Payments made directly to you and benefit does not offset with medical coverage
• Keep your coverage, at the same cost, even if you retire or change employers
• Guaranteed Issue amounts during the initial new hire period or during the open enrollment period
• Elect Critical Illness with or without Cancer
• The chart below is a sample of covered in-network services. Additional information can be found on your benefits website.
$40,000
Children 25% of Employee Amount
(Myocardial Infarction)
B, C, or D
Payout 3 x benefit amount for all covered persons combined GUARANTEED ISSUE (No Health Questions) Employee: $20,000 & Spouse: $20,000
WELLNESS INCENTIVE
SECOND OCCURRENCE (DIFFERENT ILLNESS)
RE-OCCURRENCE BENEFIT (SAME ILLNESS)
$50 - (See Wellness Incentives page)
25% of face amount, up to the max - 30 days after the initial diagnosis
25% of face amount, up to the max - 180 days after the initial diagnosis
PRE-EXISTING CONDITION 12/12
Illness or injury for which you received treatment the 12 months prior to your effective date will not be covered for the first 12 months.
(Applies to new enrollees only)
Age Reduction 50% at age 75
Plan Rates
Cost of coverage is based on the level of benefit you choose and your age. Please consult with a Campus Benefits Counselor or log into the enrollment system for rate details.
CANCER INSURANCE
What is Cancer Insurance? Cancer insurance is a form of supplemental insurance meant to offset cancerrelated expenses so you can focus on recovery.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26)
• Coverage through Colonial Life
• Keep your coverage, at the same cost, even if you retire or change employers
• Payments made directly to you and do not offset with medical insurance
• The chart below is a sample of covered services. For a detailed listing of services in their entirety, please see the Plan highlight Sheet available on the Coastal Plains RESA Benefits Website.
$50 - (See Wellness Incentives page)
None - Must be 5 years cancer free
WAITING PERIOD 30 Days
Plan Rates
Cost of coverage is based on the level of benefit you choose and your age. Please consult with a Campus Benefits Counselor or log into the enrollment system for rate details.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and
and/ or premiums may change after printing. Eligibility,
ACCIDENT INSURANCE
What is Accident Insurance? A financial and family protection plan designed to help pay for the medical and out-of-pocket costs a covered individual may incur after an accidental injury either on or off the job.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26)
• Coverage through Colonial Life
• Payments made directly to you and benefit does not offset with medical coverage
• Pre-Existing Condition Limitation on Hospital Confinement only
• Portability included
• The chart below is a sample of covered services. For a detailed listing of services in their entirety, please see the Plan Highlight Sheet, available on the Coastal Plains RESA Benefits website.
INJURIES
Lacerations (Based on size & repair)
MEDICAL SERVICES & TREATMENT
Hospital Stay (Max 365 days) $275/day
ICU Stay (Max 365 days)
Office Visit (Max 12)
Therapy Visit (Max 10)
ACCIDENTAL
DEATH
& DISMEMBERMENT
EE/SP: $25,000
EE/SP: $40,000
Accidental Death Benefit - Basic
Accidental Death Benefit - Common Carrier
WELLNESS INCENTIVE
WAITING PERIOD
AGE REDUCTION
CH: $5,000
EE/SP: $100,000
CH: $15,000
CH: $10,000
EE/SP: $160,000
CH: $30,000
$50 - (See Wellness Incentives page)
None - 30 day wait on wellness benefit
None
WELLNESS INCENTIVES
GET REWARDED FOR PREVENTIVE CARE
What are Wellness Incentives? An annual reimbursement for covered members who complete one of the eligible screening procedures on your critical illness, cancer, and accident insurance plans.
Eligibility: You, spouse and dependents who are covered on the critical illness, cancer, or accident plans How it works:
• If you or a covered dependent get one of the eligible screenings, you can file a wellness claim
• Once approved, you will receive a check for the wellness benefit amount
• The wellness benefit can be filed annually as long as your critical illness, cancer, and accident plans are in force
• Blood test for triglycerides
• Bone marrow testing
• Breast ultrasound
• CA 15-3 (blood test for breast cancer)
• CA 125 (blood test for ovarian cancer)
• Carotid Doppler
• CEA (blood test for colon cancer)
• Chest X-ray
• Colonoscopy
• Echocardiogram (ECHO)
• Electrocardiogram (EKG, ECG)
• Fasting blood glucose test
• Flexible sigmoidoscopy
• Hemoccult stool analysis
• Mammography
• Pap smear
• PSA (blood test for prostate cancer)
• Serum cholesterol test for HDL and LDL levels
• Serum protein electrophoresis (blood test for myeloma)
• Skin cancer biopsy
• Stress test on a bicycle or treadmill
• Thermography
• ThinPrep pap test
• Virtual colonoscopy
*Cancer Wellness includes an additional invasive diagnostic test or procedure benefitVisit your employee benefits portal for additional information. www.cpresabenefits.com
How to File a Wellness Claim?
1. Complete your wellness
2. File your claim online at www.coloniallife.com and click on “File a Claim” button OR
3. Fax your claim form to 1.800.880.9325 OR
4. Mail your claim form to Colonial Life Wellness P.O. Box 100195 Columbia, SC 29202
• Wellness forms are located on your benefits portal, www.cpresabenefits.com
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
Available Wellness Incentives
What Qualifies as Wellness?
Colonial Life Critical Illness / Cancer/ Accident Plans
MEDCARECOMPLETE
THE SMART WAY TO REDUCE YOUR HEALTHCARE COSTS
What is MedCareComplete? A bundle of services constructed to save you time, money, and hassle while simplifying your life.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26)
• This is a supplemental benefit and does not replace health insurance
• The employee portion of this benefit is paid for by Coastal Plains RESA. Employees must elect coverage to be covered.
• Register at MCC: www.medcarecomplete.com/members to access the full range of benefits
• Register at 1800MD: www.800md.com or 1.800.388.8785 to access telemedicine benefits
Included With the MedCareComplete Membership:
Medical Bill Negotiator
Medication Management
Telemedicine
Medical & ID Theft Monitoring
Medical Bill Negotiator
Restoration Expert
Expense Reimbursement
Social Media Tracking
Sex Offender Alerts
A medical bill advocate will identify and appeal common billing errors and overcharges on your behalf. Advocates provide continuous support throughout the appeal that typically results in an average savings of 40% on 80% of the bills reviewed.
Telemedicine
Get 24/7/365 on-demand telephone access to Board-certified physicians for diagnosis and prescriptions for common and acute illnesses.
Acute Illnesses include but are not limited to the following:
Service monitors the internet for instances of your personal health and financial information to protect you from becoming a victim of identity theft. The security of your personal health information (PHI) can have a large impact on the medical care you receive.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
LEGAL PLAN
What is Legal Plan? A plan which provides valuable legal and financial educational resources for a variety of life events and needs.
Eligibility: Eligible full-time employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26)
• Coverage through MetLife
• Elder Care extends to parents and in-laws
• Visit www.legalplans.com/why-enroll or call 1.800.821.6400 for additional information
• Non-members & members create an account and select Employer for plan information (creating an account doesn’t enroll you in plans)
• High Plan: For non-covered matters that are not otherwise excluded, your plan provides four hours of network attorney time and services per year
• Additional information can be found on your benefits website (www.cpresabenefits.com)
• Identity Theft Defense
Money Matters
Home & Real Estate
Estate Planning
• Negotiations with Creditors
• Promissory Notes
• Debt Collection Defense
• Tax Collection Defense
• Deeds
• Mortgages
• Foreclosure
• Tenant Negotiations
• Eviction Defense
Security Deposit Assistance
• Simple and Complex Wills
• Healthcare Proxies
• Living Wills
• Codicils
• Powers of Attorney (Healthcare, Financial, Childcare, Immigration
• Guardianship
• Conservatorship
• Name Change
• Review of ANY Personal Legal Document
Family & Personal
Civil Lawsuits
• School Hearings Demand Letters
• Affidavits
• Personal Property Issues
• Garnishment Defense
• Domestic Violence Protection
• Disputes over Consumer Goods & Services
• Administrative Hearings
• Incompetency Defense
Consultation & Document review for issues related to your (or spouse’s) parents: Medicare
Elder Care Issues
Vehicle & Driving
• Medicaid
• Prescription Plans
• Nursing Home Agreements
• Leases
• Promissory Notes
• Deeds
• Wills
• Power of Attorney
• Repossession
• Defense of Traffic Tickets
• Driving Privileges Restoration
• License Suspension due to DUI
• Identity Theft Defense
• Negotiations with Creditors
• Promissory Notes
• Debt Collection Defense
• Tax Collection Defense
• Deeds
• Mortgages
• Foreclosure
• Tenant Negotiations
• Eviction Defense
Security Deposit Assistance
• Simple and Complex Wills
• Healthcare Proxies
• Living Wills
• Codicils
• Powers of Attorney (Healthcare, Financial, Childcare, Immigration
• Review of Immigration Documents Prenuptial Agreement
• Adoption
• Civil Litigation Defense & Mediation
• Small Claims Assistance
• Pet Liabilities
Consultation & Document review for issues related to your (or spouse’s) parents:
• Medicare
• Medicaid
• Prescription Plans
• Nursing Home Agreements
• Leases
• Promissory Notes
• Deeds
• Wills
• Power of Attorney
• Repossession
• Defense of Traffic Tickets
Driving Privileges Restoration
• License Suspension due to DUI
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
FLEXIBLE SPENDING ACCOUNTS
What are Medical Flexible Spending Accounts (FSAs)? A pre-tax benefit account used to pay for out-of-pocket healthcare costs such as deductibles, co-pays, prescribed medication and other medical costs.
What is Dependent Care Accounts? A pre-tax benefit account used to pay for dependent care services such as preschool, summer day camp, before or after school programs, and child or elder daycare.
Eligibility: Eligible employees as described on page 1 of this benefits guide, spouse, & unmarried children (up to age 26) *For Dependent Care children (children up to age 13) and adults for adult day care
• Coverage through Consolidated Admin Services
• Plan year is from January 1- December 31 and employees must re-elect each year
• Only family status changes will allow you to change your annual election. The altered election must be consistent with the status change.
• Married and not filing jointly participants limited to $3,750 deferral for Dependent Care
• Transfer of funds between the Dependent Care and Medical Care accounts are prohibited
• Please visit your employee benefits website for a complete listing of eligible expenses and qualifying dependent care services.
Carryover Maximum*- Amount participants can carry over if re-electing the plan
Total elected amount is available at the beginning of the plan year All receipts should be kept to submit if verification is requested
Minimum Contribution
DEPENDENT CARE ACCOUNT
$300 annually Maximum Contribution
Carryover Maximum
$7,500 annually
None
Amounts are available as they are payroll deducted PLAN RULES
RUNOUT PERIOD - Time to turn in receipts for services rendered during the plan year. 30 days after plan end date
IMPORTANT NOTE:
FSA/DCAP Fee Per Participant Per Month
This amount is based on the number of participants who enroll in FSA for the year and will be calculated at the beginning of each plan year. Typically this amount is around $4.00.
Card Fee (Coastal RESA pays)
Dependent Care FSA is for eligible expenses related to the care of your child, disabled spouse, elderly parent, or other dependent who is physically or mentally unable for self-care (i.e. day care, adult day care) or is disabled. Medical expenses for your dependent are not eligible for reimbursement under the Dependent Care account.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
HELPFUL FSA RESOURCES
What is covered under Medical FSA Account?
• Medical coinsurance and deductible
• Doctor’s office visit copays
• Emergency Room costs
• Dental copays and out-of-pocket costs
• Vision copays and out-of-pocket costs
• Contacts and glasses
• Prescriptions
• Please see the full eligibility list for other covered expenses
Who is covered under Dependent Care Account?
FSA Eligibility List www.consolidatedadmin.com/fsa-hsa-eligibleexpenses
• Children ages 12 and under (including stepchildren, grandchildren, adopted or foster children, and children related to you who are eligible for a tax exemption on your federal tax return)
• Tax dependents residing with you and incapable of self-care (this could include your spouse, a child age 13 and over, and elderly parents)
The CARES Act permanently reinstates over-the counter products, and adds menstrual care products for the first time, as eligible expenses for your FSA funds WITHOUT A PRESCRIPTION!
Eligible items for purchase without a prescription now include, but are not limited to:
• Children’s pain relievers, allergy medicines, and digestive aids
FSA Calculator (estimates how much you can save with an FSA) www.fsastore.com/fsa-calculator In the App Store go to: Consolidated Admin Services Online Portal and Access to information: www.consolidatedadmin.com
IMPORTANT NOTE:
Dependent Care FSA is for eligible expenses related to the care of your child, disabled spouse, elderly parent, or other dependent who is physically or mentally unable for self-care (i.e. day care, adult day care) or is disabled. Medical expenses for your dependent are not eligible for reimbursement under the Dependent Care account.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
BENEFITS PORTAL!
CAMPUS BENEFITS ENROLLMENT
Coastal Plains RESA
Steps To Log In:
https://www.cpresabenefits.com
Company
Select “Campus Connect” to log in
3
Existing User Login
1. Enter your username
2. Enter your password
3. Click “LOGIN”
4. Click on the “Start Benefits” button and begin the enrollment process
FAQ’S
What is my username?
• Work email address OR
• Email address you provided to HR when hired OR
• Email address you used to previously change your username
What is my password?
To create or reset a forgotten password follow the steps on the login page using tips below.
• Password must be at least 6 characters
• It must contain a symbol and a number
• Using uppercase, numbers and symbols greatly improves security
What can I find on the portal?
• Access to personal benefit elections
• Plan highlight sheets and policy documents
• Claim forms
• Links to State Health Benefit Plan information
New User Registration
1. On Login page click on “Register as a new user” and enter information below
• First Name
• Last Name
• Company Identifier: CPR14
• PIN: Last 4 Digits of SSN
• Birthdate
2. Click “Next”
3. Username: Work email address or one you have provided to HR when you were hired
4. Password: Must be at least 6 characters and contain a symbol and a number
5. Click on “Register”
6. On the next page, it will show your selected Username. Click on “Login”
7. Enter Username and Password
8. Click “Start Benefits” to begin the enrollment
STILL NEED HELP?
Contact Campus Benefits
• Email mybenefits@campusbenefits.com
• Call 1.866.433.7661, opt 5
Login Information
Username: _______________________________
Password: ________________________________
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
SERVICE HUB/ SUPPORT CENTER
Campus Benefits is your dedicated advocate for all your voluntary benefits.
When to contact the Campus Benefits Service Hub
• Portability/Conversion
• Benefits Education
• Evidence of Insurability
• Qualified Life Event Changes
How to File a Claim
• Claims
• Card Requests
• Benefit Questions
1. Contact Campus Benefits via phone or email
2. Work with Campus Benefits’ claims specialist to complete the necessary paperwork
• Employee Portion
• Physician Portion
• Employer Portion
• COBRA Information The Campus Benefits team understands the claims process and leverages the necessary carrier relationships to expedite the paperwork efficiently to ensure claims are not delayed due to improper paperwork completion.
3. Submit the necessary paperwork to Campus Benefits via the secure upload
• Secure upload located at www.cpresabenefits.com/contact-campus
Frequently Asked Questions (FAQs):
Q: When must a qualifying life event change be made?
A: Please notify Campus Benefits within 30 days of the life event date. All SHBP life events must be made directly through the SHBP website.
Q: Am I required to contact Campus Benefits to file a claim?
A: No. However, in our experience the number one reason for claim denial or delay is due to incomplete or inaccurate paperwork. By working with Campus Benefits’ claim specialist, we can advocate on your behalf.
Q: How can I access the group dental card or vision card quickly?
A: Your Campus Benefits group dental and vision plan information is available at: ww.cpresabenefits.com
STATE HEALTH BENEFIT PLAN
STATE HEALTH BENEFIT PLAN
Eligibility: Please review the SHBP Decision Guide for plan eligibility rules.
• Coverage through Anthem, United Healthcare, or Kaiser Permanente.
• All qualifying life events must be submitted via the SHBP Portal.
• Notice: Your employer offers all eligible employees health insurance through the Georgia State Health Benefit Plan. During the annual open enrollment, you have the opportunity to review all available options and make elections for the upcoming Plan Year.
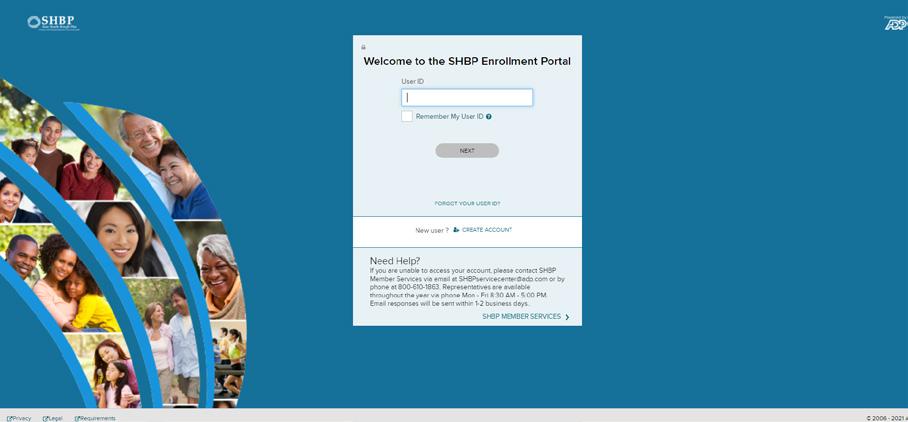
www.myshbpga.adp.com
SHBP Decision Guide:
In this guide, you will find a brief explanation about each health benefit option, a benefit comparison guide, and a list of things to consider before making your election decision.
You can access the decision guide at www.shbp.georgia.gov
STATE HEALTH
The table below is a high level overview, for official details and plan information please review the SHBP Decision Guide.
Designs for 2026
HRA (Health Reimbursement Arrangement) Credits
decision guide and summary plan documents for
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
SHBP LEGAL NOTICES
Availability of Summary Health Information Summary of Benefits & Coverage (SBC)
As an employee, the SHBP health benefits available to you represent a significant component of your compensation package. They also provide important protection for you and your family in the case of illness or injury.
SHBP offers a series of health coverage options. Choosing a health coverage option is an important decision. To help you make an informed choice, SHBP makes available a Summary of Benefits and Coverage (SBC), which summarizes important information about any health coverage option in a standard format, to help you compare across options.
The SBC is available on the web at: www.shbp.georgia.gov/plan-documents/otherdocuments/summary-benefits-and-coverage. A paper copy is also available, free of charge, by calling 229-546-4094.
About the Following Notices:
The following important legal notices are also posted on the State Health Benefit Plan (SHBP) website at www.shbp.georgia.gov/plan-documents under Plan Documents.
Penalties for Misrepresentation
If a SHBP participant misrepresents eligibility information when applying for coverage during change of coverage or when filing for benefits, the SHBP may take adverse action against the participants, including but not limited to terminating coverage (for the participant and his or her dependents) or imposing liability to the SHBP for fraud for indemnification (requiring payment for benefits to which the participant or his or her beneficiaries were not entitled). Penalties may include a lawsuit, which may result in payment of charges to the Plan or criminal prosecution in a court of law. To avoid enforcement of the penalties, the participant must notify the SHBP immediately if a dependent is no longer eligible for coverage or if the participant has questions or reservations about the eligibility of a dependent. This policy may be enforced to the fullest extent of the law.
Federal Patient Protection and Affordable Care Act Notices
Choice of Primary Care Physician
The Plan generally allows the designation of a Primary Care Physician/Provider (PCP). You have the right to designate any PCP who participates in the Claims Administrator’s network, and who is available to accept you or your family members. For children, you may also designate a pediatrician as the PCP. For information on how to select a PCP, and for a list of participating PCPs, call the telephone number on the back of your Identification Card.
Access to Obstetrical and Gynecological (OB/ GYN) Care
You do not need prior authorization from the Plan or from any other person (including a PCP) in order to obtain access to obstetrical or gynecological care from a health care professional in the Claims Administrator’s network who specializes in obstetrics or gynecology. The healthcare professional, however, may be required to comply with certain procedures, including obtaining prior authorization for certain services, following a pre-approved treatment plan, or procedures for making referrals. For a list of participating health care professionals who specialize in obstetrics or gynecology, call the telephone number on the back of your Identification Card.
HIPAA Special Enrollment Notice
If you decline enrollment for yourself or your Dependents (including your spouse) because of other health insurance or group health plan coverage, you may be able to enroll yourself and your Dependents if you or your Dependents lose eligibility for that other coverage (or if the employer stops contributing towards your or your Dependents’ other coverage) your other health insurance coverage ends. However, you must request enrollment within 31 days after your or your Dependents’ other coverage ends (or after the employer stops contributing toward the other coverage). In addition, if you have a new Dependent as a result of marriage, birth, adoption or placement for adoption, you may be able to enroll yourself and your new Dependents. However, you must request enrollment within 31 days after the marriage or adoption, or placement for adoption (or within 90 days for a newly eligible dependent child).
Eligible Covered Persons and Dependents may also enroll under two additional circumstances: The Covered Person’s or Dependent’s Medicaid or Children’s Health Insurance Program (CHIP) coverage is terminated as a result of loss of eligibility; or The Covered Person or Dependent becomes eligible for a subsidy (State Premium Assistance Program).
NOTE: The Covered Person or Dependent must request Special Enrollment within sixty (60) days of the loss of Medicaid/CHIP or of the eligibility determination. To request Special Enrollment or obtain more information, call the SHBP Member Services Center at 800-610-1863 or contact your Benefit Coordinator/Payroll Location.
Women’s Health and Cancer Rights Act of 1998
The Plan complies with the Women’s Health and Cancer Rights Act of 1998. Mastectomy, including reconstructive surgery, is covered the same as other surgery under your Plan option. Following cancer surgery, the SHBP covers:
• All stages of reconstruction of the breast on which the mastectomy has been performed
• Reconstruction of the other breast to achieve asymmetrical appearance
• Prostheses and mastectomy bras
• Treatment of physical complications of mastectomy, including lymph edema
NOTE: Reconstructive surgery requires prior approval, and all Inpatient admissions require prior notification. For more detailed information on the mastectomy related benefits available under the Plan, call the telephone number on the back of your Identification Card.
Newborns’ and Mothers’ Health Protection Act of 1996
The Plan complies with the Newborns’ and Mothers’ Health Protection Act of 1996. Group health plans and health insurance issuers generally may not, under Federal law, restrict Benefits for any Hospital length of stay in connection with childbirth for the mother or newborn to less than 48 hours following a vaginal delivery, or less than 96 hours following a cesarean section. However, federal law generally does not prohibit the mother’s or newborn’s attending Provider, after consulting with the mother, from discharging the mother or her newborn earlier than 48 hours (or 96 hours, as applicable). In any case, plans and issuers may not, under Federal law, require that a Provider obtain authorization from the Plan or the insurance issuer for prescribing a length of stay not in excess of 48 hours (or 96 hours, as applicable).
HEALTH INSURANCE PORTABILITY AND ACCOUNTABILITY ACT NOTICE OF INFORMATION PRIVACY PRACTICES
Georgia Department of Community Health State Health Benefit Plan Notice of Information Privacy Practices. Revised August 4, 2015.
The purpose of this notice is to describe how medical information about you, which includes your personal information, may be used and disclosed and how you can get access to this information. Please review it carefully.
The Georgia Department of Community Health (DCH) and the State Health Benefit Plan Are Committed to Your Privacy.
DCH understands that your information is personal and private. Certain DCH employees and companies hired by DCH to help administer the Plan (Plan Representatives) use and share your personal and private information in order to administer the Plan. This information is called “Protected Health Information” (PHI), and includes any information that identifies you or information in which there is a reasonable basis to believe can be used to identify you and that relates to your past, present, or future physical or mental health or condition, the provision of health care to you, and payment for those services. This notice tells how your PHI is used and shared by DCH and Plan Representatives. DCH follows the information privacy rules of the Health Insurance Portability and Accountability Act of 1996(“HIPAA”).
Only Summary Information is Used When Developing and/or Modifying the Plan. The Board of Community Health, which is the governing Board of DCH, the Commissioner of DC Hand the Chief of the Plan administer the Plan and make certain decisions about the Plan. During those processes, they may review certain reports that explain costs, problems, and needs of the Plan. These reports never include information that identifies any individual person. If your employer is allowed to leave the Plan entirely, or stop offering the Plan to a portion of its workforce, DCH may provide Summary Health Information (as defined by federal law) for the applicable portion of the workforce. This Summary Health Information may only be used by your employer to obtain health insurance quotes from other sources and make decisions about whether to continue to offer the Plan. Please note that DCH, Plan Representatives, and your employer are prohibited by law from using any PHI that includes genetic information for underwriting purposes.
Plan “Enrollment Information” and “Claims Information” are Used in Order to Administer the Plan. PHI includes two kinds of information, Legal Notices (cont.) “Enrollment Information” and “Claims Information.” “Enrollment Information” includes, but is not limited to, the following types of information regarding your plan enrollment: (1) your name, address, email address, social security number and all information that validates you (and/or your Spouse and Dependents) are eligible or enrolled in the Plan; (2) your Plan enrollment choice; (3) how much you pay for premiums; and (4) other health insurance you may have in effect. There are certain types of “Enrollment Information” which may be supplied to the Plan by you or your personal representative, your employer, other Plan vendors or other governmental agencies that may provide other benefits to you. This “Enrollment Information” is the only kind of PHI your employer is allowed to obtain. Your employer is prohibited by law from using this information for any purpose other than assisting with Plan enrollment. “Claims Information” includes information your health care providers submit to the Plan.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
SHBP LEGAL NOTICES
For example, claims information may include medical bills, diagnoses, statements, x-rays or lab test results. It also includes information you may submit or communicate directly to the Plan, such as health questionnaires, biometric screening results, enrollment forms, leave forms, letters and/or telephone calls. Lastly, it includes information about you that may be created by the Plan. For example, it may include payment statements and/or other financial transactions related to your health care providers.
Plan are “Plan Representatives,” and therefore must protect your PHI. These Plan Representatives may only use PHI and share it as allowed by HIPAA, and pursuant to their “Business Associates” agreements with DCH to ensure compliance with HIPAA and DCH requirements. DCH Must Ensure the Plan Complies with HIPAA. DCH must make sure the Plan complies with all applicable laws, including HIPAA. DCH and/or the Plan must provide this notice, follow its terms and update it as needed. Under HIPAA, Plan Representatives may only use and share PHI as allowed by law. If there is a breach of your PHI, DCH must notify you of the breach.
Plan Representatives Regularly Use and Share your PHI in Order to Administer the Plan. Plan Representatives may verify your eligibility in order to make payments to your health care providers for services rendered. Certain Plan Representatives may work for contracted companies assisting with the administration of the Plan. Bylaw, these Plan Representative companies also must protect your PHI. HIPAA allows the Plan to use or disclose PHI for treatment, payment, or health care operations.
Below are examples of uses and disclosures for treatment, payment and health care operations by Plan Representative Companies and PHI data sharing.
Claims Administrator Companies: Plan Representatives process all medical and drug claims; communicate with the Plan Members and/or their health care providers.
Wellness Program Administrator Companies: Plan Representatives administer Well-Being programs offered under the Plan; and communicate with the Plan Members and/or their health care providers.
Actuarial, Health Care and /or Benefit Consultant Companies: Plan Representatives may have access to PHI in order to conduct financial projections, premium and reserve calculations, and financial impact studies on legislative policy changes affecting the Plan.
State of Georgia Attorney General’s Office, Auditing Companies and Outside Law Firms: Plan Representatives may provide legal, accounting and/ or auditing assistance to the Plan.
Information Technology Companies: Plan Representatives maintain and manage information systems that contain PHI.
Enrollment Services Companies: Plan Representatives may provide the enrollment website and/or provide customer service to help Plan Members with enrollment matters.
Note: Treatment is not provided by the Plan but we may use or disclose PHI in arranging or approving treatment with providers. Legal Notices (cont.) 43 Under HIPAA, all employees of DCH must protect PHI and all employees must receive and comply with DCH HIPAA privacy training. Only those DCH employees designated by DCH as Plan Representatives for the SHBP healthcare component are allowed to use and share your PHI.
DCH and Plan Representatives May Make Uses or Disclosures Permitted by Law in Special Situations. HIPAA includes a list of special situations when the Plan may use or disclose your PHI without your authorization as permitted by law. The Plan must track these uses or disclosures. Below are some examples of special situations where uses or disclosures for PHI data sharing are permitted by law. These include, but are not limited to, the following:
Compliance with a Law or to Prevent Serious Threats to Health or Safety: The Plan may use or share your PHI in order to comply with a law or to prevent a serious threat to health and safety.
Public Health Activities: The Plan may give PHI to other government agencies that perform public health activities.
Information about Eligibility for the Plan and to Improve Plan Administration: The Plan may give PHI to other government agencies that may provide you benefits (such as state retirement systems) in order to get information about your eligibility for the Plan and to improve administration of the Plan.
Research Purposes: Your PHI may be given to researchers for a research project, when the research has been approved by an institutional review board. The institutional review board must review the research project and its rules to ensure the privacy of your information.
Plan Representatives Share Some Payment Information with the Employee. Except as described in this notice, Plan Representatives are allowed to share your PHI only with you and/or with your legal personal representative. However, the Plan may provide limited information to the employee about whether the Plan paid or denied a claim for another family member.
You May Authorize Other Uses of Your PHI. Plan Representatives may not use or share your PHI for any reason that is not described in this notice without a written authorization by you or your legal representative. For example, use of your PHI for marketing purposes or uses or disclosures that would constitute a sale of PHI are illegal without this written authorization. If you give a written authorization, you may revoke it later.
You Have Privacy Rights Related to Plan Enrollment Information and Claims Information that Identifies You.
Right to Inspect and Obtain a Copy of your Information, Right to Ask for a Correction: You have the right to obtain a copy of your PHI that is used to make decisions about you. If you think it is incorrect or incomplete, you may contact the Plan to request a correction.
Right to Ask for a List of Special Uses and Disclosures: You have the right to ask for a list of all special uses and disclosures. Right to Ask for a Restriction of Uses and Disclosures or for Special Communications: You have the right to ask for added restrictions on uses and disclosures, but the Plan is not required to agree to a requested restriction, except if the disclosure is for the purpose of carrying out payment or health care operations, is not otherwise required by law, and pertains solely to a health care item or service that you or someone else on your behalf has paid in full. You also may ask the Plan to communicate with you at a different address or by an alternative means of communication in order to protect your safety. Right to a Paper Copy of this notice and Right to File a Complaint: You have the right to a paper copy of this notice. Please contact the SHBP Member Services Center at 1-800-610-1863 or you may download a copy at www.dch.georgia.gov/ shbp. If you think your HIPAA privacy rights may have been violated, you may file a complaint. You may file the complaint with the Plan and/or the U.S. Department of Health & Human Services, Office of Civil Rights, Region IV. You will never be penalized by the Plan or your employer for filing a complaint.
Address to File HIPAA Complaints:
Georgia Department of Community Health
SHBP HIPAA Privacy Unit
P.O. Box 1990 Atlanta, GA 30301
1-800-610-1863
U.S. Department of Health & Human Services Office for Civil Rights Region IV
Atlanta Federal Center 61 Forsyth Street SW Suite 3B70 Atlanta, GA 30303-8909
1-877-696-6775
For more information about this Notice, contact:
Georgia Department of Community Health State Health Benefit Plan P.O. Box 1990 Atlanta, GA 30301 1-800-610-1863
MENTAL HEALTH PARITY AND ADDICTION EQUITY ACT OPT-OUT NOTICE Election to be Exempt from Certain Federal law requirements in title XXVII of the Public Health Service Act Date: August 4, 2015
TO: All Members of the State Health Benefit Plan who are not Enrolled in a Medicare Advantage Option Group health plans sponsored by state and local governmental employers must generally comply with Federal law requirements in title XXVII of the Public Health Service Act. However, these employers are permitted to elect to exempt a plan from the requirements listed below for any part of the plan that is “self-funded” by the employer, rather than provided through a health insurance policy. Your plan option is self-funded because the Department of Community Health (DCH) pays all claims directly instead of buying a health insurance policy.
The Department of Community Health has elected to exempt your State Health Benefit Plan from the Mental Health Parity and Addiction Equity Act, that includes protections against having benefits for mental health and substance use disorders be subject to more restrictions than apply to medical and surgical benefits covered by the Plan.
The exemption from these federal requirements will be in effect for the plan year starting January 1, 2016 and ending December 31, 2016. The election may be renewed for subsequent plan years.
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
NOTES
Disclaimer: The Benefits Guide is provided for illustrative purposes only and actual benefits and/ or premiums may change after printing. Eligibility, benefits, limitations, services, premiums, claims processes and all other features & plan designs are offered and governed exclusively by the insurance provider or vendor contract and associated Summary Plan Description (SPD). All employees should review carrier documents posted on your employer’s benefits website or request documents before electing coverage.
•
•
•
•
•
•
•
•
The 2026 Benefits Enrollment Guide is provided for illustrative purposes only. Actual benefits, services, premiums, claims processes and all other features and plan designs for coverage offered is governed exclusively by the insurance contract and associated Summary Plan Description (SPD). In case of discrepancies between this document and the insurance contract and SPD, the contract and SPD will prevail.
We reserve the right to change, modify, revise, amend or terminate these plan offerings at any time. Updates, changes and notices are available to you per your request. Call 1.866.433.7661, opt 5 These should be reviewed fully prior to electing any benefits.