Explore the month’s most exceptional deals and standout cases from leading experts in the specialist finance industry, all in B&C Magazine’s DOTM Special

Explore the month’s most exceptional deals and standout cases from leading experts in the specialist finance industry, all in B&C Magazine’s DOTM Special
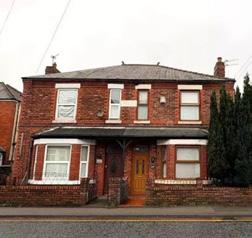
Loan size: £328,875
Loan term: 12 months
LTV: 75%
Reason for loan: Funding to pay off an existing lender
Location: Warrington
Exit plan: Refinance
Time to fund: Eight days
Broker/Borrower/Relevant parties: Relationship manager Ash Kendall, Underwriter Tobias Williams, Processor Chung Liu
Nathan Parry of Y3S introduced this case to MS Lending Group, where the client required urgent funding to complete the purchase of an HMO investment property at auction.
The security was made up of two semidetached properties, and the client was an experienced investor with a large portfolio. We were able to move quickly, using a desktop valuation to keep things simple and efficient, and completed the deal in just eight working days.
The client plans to exit by refinancing onto a longer-term facility, allowing them to keep the property as part of their wider portfolio. This is how bridging should be: fast, flexible, and straightforward. At MS Lending Group, we know speed matters, especially with auction finance, and this case is a great example of how we can support our clients with securing the funding they need without unnecessary delays.
Nathan Parry commented: “I approached MS Lending Group for an urgent auction purchase of two HMOs; the client needed to service the bridge to get the max LTV, and also, he needed a desktop for speed. MSLG acted quickly, issuing terms, organising the valuation and allowing the client to service the bridge. MS Lending Groups’ acting solicitor was very responsive, which allowed us to complete the deal in the timeframe needed, and the client was very happy with both the outcome and level of service.”
Octane Capital has completed a £4.41m developer exit loan for an established UK developer and contractor with more than 25 years’ experience across Surrey and the wider Home Counties.
The transaction marks a repeat piece of business, with the borrower returning to Octane to support their latest funding requirement, reflecting the ongoing relationship between the two parties.
The facility was structured as a 15-month developer exit loan at 65% LTV, secured against four semi-detached homes forming part of a six-unit scheme. The development has been finished to a high standard and includes access to a private parcel of woodland, a feature that sets it apart within the local market.
At the point of completion, two of the units had already been sold. The loan refinanced the existing facility while also releasing equity, giving the developer time to market and sell the remaining properties without pressure, and ultimately maximise values.
The deal was completed in three weeks and priced at 0.71% per month, linked to BBR. It included a 1% arrangement fee, no exit fees, and rolled interest.
The case was introduced and packaged by Steve Bealing at ASC Finance for Business. At Octane, the transaction was led by senior BDM Francesca Woodhouse and underwritten
by Jamie Oxley, senior structured finance manager. Knight Frank provided the valuation, with legal work carried out by Daniel Baker and Seray Kitchingman at Weightmans.
Francesca Woodhouse said “This is a good example of how developer exit can be used in the right way—not just as a refinance, but as a tool to give borrowers the time and flexibility to deliver the best outcome on a scheme.
“It also highlights the importance of relationships. Having worked with this client before, there was already a clear understanding on both sides, which helped us move quickly and structure something that worked for everyone involved.
“Thanks to Steve and the team at ASC for bringing this back to us and working closely throughout.”
One of the benefits of specialist finance is its ability to unlock opportunities for those who want to raise capital from existing properties through a remortgage. This is especially true in instances where traditional finance providers do not have the appetite for lending towards the purpose of the capital raising remortgage.
A client, who is the owner of an existing fully-let commercial property in Wales, recently approached us for this reason. They owned a commercial building comprising twelve individual office units. Despite the property earning regular and consistent profit, they had identified an opportunity to pursue a new business venture but had to remortgage the property and raise capital in order to do so. They also needed to secure the funds timeously to make use of the opportunity.
As their existing mortgage was with a high-street lender, there was no appetite from the banks’ side to provide a capitalraising remortgage for business or investment purposes.
Not only were we willing to help the client secure a mortgage that would raise capital from the commercial property for the use case they presented, but we were also able to provide improved terms from what they were paying before.
The property, valued at £950,000, still had around £350,000 outstanding. We provided a loan facility of £595,000 at 63%
LTV, which helped the client repay their existing mortgage in full. This remortgage facility resulted in a cash surplus of around £230,000 to fund a new business venture.
Once the deal was completed, the client commented: “Releasing the equity has put us in a great position for our next project, and I wouldn’t hesitate to work with [West One] again.”
Upon receiving the enquiry, we were able to issue indicative terms on the same day. The full application was submitted just five days later and was successfully funded in 45 days, which was shorter than the expected time-to-completion with their existing high street lender.
The client added: “From start to finish, the process was handled efficiently and professionally. The speed at which terms were issued really stood out, and everything progressed exactly as promised.”
If you are looking to remortgage an existing commercial property and you value speed and a willingness to find a solution, West One is ready to assist. Get in touch with our commercial mortgage team at commercial.term@westoneloans.co.uk
Loan size: £13m
Loan type: Unregulated bridging
Loan term: Nine months
LTV: 75% gross LTV based on purchase price
Reason for loan: Auction purchase of 40-property residential portfolio
Exit plan: Refinance onto BTL
Andy Neo
Comment from Neal Telford, director of bridging and development at Capital B Property Finance:
“Given the number of properties involved, it was essential that the case progressed quickly and with certainty. Together worked diligently to ensure challenges were addressed, communication was clear throughout, and funding was delivered on time to meet the client’s requirements.”
Andy Neo, key account manager at Together, commented:
35 new homes_York3.png
“Our team has extensive experience in dealing with complex cases, auction deadlines and multi-million-pound transactions, so when Capital B approached us for support, we knew we had the flexibility, appetite and speed to deliver. The case was processed through our new dedicated service Premier for Intermediaries and shows how we can help brokers with complex £1m-plus deals across a range of personal finance and business lending scenarios.”
Roma Finance has completed a £1.3m BTL facility in just six days, delivering a standout turnaround on a complex dual asset transaction.
The borrowers were up against an imminent deadline to refinance their existing development exit loan and avoid significant penalty charges. This required a lender able to act quickly across two investment properties:
• An 11-bed MUFB (multi-unit freehold block) in Bedford, formerly a family-owned doctor’s surgery now converted into residential accommodation
• A detached single-family home let on an AST (Assured Shorthold Tenancy)
Following a full assessment of the borrowers’ requirements, alongside their strong asset-backed position, moderate leverage and clear refinance exit, Roma progressed immediately with confident decision-making. An AVM supported the underwriting process, allowing momentum to be maintained
Loan amount: £1.3m LTV: 63%
Term: 36 months
Exit strategy: Refinance
without compromising diligence.
A people-first approach was key to delivering the outcome. Rather than relying solely on standard criteria, the case was assessed in the context of the borrowers’ circumstances, timeline and objectives, enabling a practical, solution-led approach within a tight timeframe.
Adam Evans, senior underwriter at Roma Finance, said: “We were extremely happy to deliver a solution in this time-sensitive case. The borrowers were in a strong asset-backed position with reasonable leverage and had a clear, credible BTL refinance exit, which enabled us to move quickly and confidently. This demonstrates that the team here at Roma has the experience and capability to deliver results when faced with high-pressure, time-sensitive transactions. Our focus is always on delivering swift, accurate decisions that give borrowers certainty when they need it most.”
George Tuffin, senior BDM at Roma Finance, added: “It was great to work with the introducer on this case. We’ve built a really strong relationship and that trust meant we were able to move quickly and collaboratively from day one. Their clear communication and thorough packaging made a huge difference, especially on a time-sensitive deal like this. We’re always proud to support brokers who share our commitment to delivering fast, reliable outcomes for their clients.”
This case demonstrates how Roma’s people-first approach delivers results. By focusing on the borrowers and their objectives, our team can act decisively and deliver solutions even under tight deadlines. Completing a complex MUFB and BTL structure in six days reflects both our speed and expertise.
General background details about the transaction:
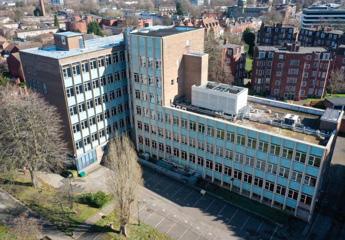
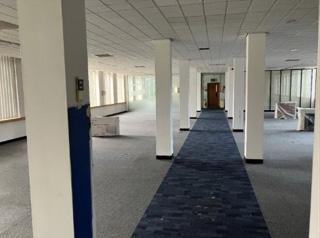
The funding enabled the acquisition of a strategically located semi-commercial asset in Birmingham, providing the speed and flexibility needed to secure the property ahead of arranging development finance for its conversion. The borrower plans to transform a former office building in Edgbaston into a 75-apartment residential scheme, comprising 42 one-bedroom and 33 two-bedroom units. Full planning permission was secured prior to completion, allowing the project to progress immediately and deliver much-needed housing in a desirable, well-connected location.
Built in the late 1950s, the property sits on a 1.38-acre (62,622 sq. ft) site and comprises a basement, ground floor and five upper floors, with 104 parking spaces and several retained original architectural features. The site benefits from strong transport links, including rail connections to major UK cities and access to the motorway network, while also being well positioned to benefit from HS2. The borrowers are experienced residential developers known to B&W, operating as a father-son team with a strong track record in conversion projects. As part of an ongoing succession plan, the son is taking responsibility for the future development pipeline. The anticipated exit is via refinance onto a
Loan size:
£1.6m (LTV 55%, 0.95% rate)
£750,000 (LTV 63%, 1.50% rate)
£955,000 (LTV 47%, 0.95% rate)
Loan term: All completed on a seven-month loan term
Reason for the loan/loan use: We helped the borrower purchase the asset before they plan to arrange development finance for the conversion works
Exit plan: The planned exit is via refinance onto a development facility; however, a sale may be considered depending on the market conditions at the time
development facility, although a sale remains an option depending on market conditions. The transaction was completed within a tight timeframe, with funding deployed across three facilities against a single asset within 24 hours, demonstrating B&W’s ability to deliver flexible funding solutions for experienced developers undertaking large-scale residential schemes.
Time taken to complete: 11th February 2026 (date of application) and 29th April 2026 (date of completion)
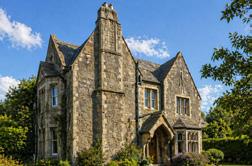
Loan size: £413,000
Loan term: Six months
Rate: 0.93% per month
LTV / LTPP: 65% LTV / 100%
loan-to-purchase-price
Security: Grade II listed building, Reading
Borrower: Portfolio landlord (SPV)
Exit: Refinance onto the refurbishment bridge
Completion: Four weeks
Matthew Rogers, development finance manager at Colenko, commented: “The borrower had a strong strategy and understood the asset well. Our job was to understand it equally well and then deliver. The title split created real, evidenced value. That is what made the lending decision straightforward, even with the complexity around it.”
The deal, managed by relationship manager Aidan Lesslie and underwritten by Saif Ali Khichi, saw Avamore Capital provide a £3.65m refurbishment facility to support the conversion of a mixed-use asset into 18 residential flats and six commercial units.
Structured over 15 months at 70% LTGDV, the facility enabled the borrower to undertake a significant residential conversion while retaining income from existing commercial tenants. The transaction completed on the contractual purchase deadline despite a number of complexities, including a layered legal structure, multiple leases and ongoing applications.
Close collaboration between all parties and a proactive approach throughout the process ensured the deal progressed efficiently to completion. The funding will allow the borrower to reposition the asset, creating additional value through the residential conversion while maintaining existing income streams.
The transaction highlights Avamore
Capital’s ability to support complex, value-add opportunities with tailored funding solutions. By combining flexible structuring, responsive execution and a pragmatic underwriting approach, the team delivered a facility that met the borrower’s objectives while maintaining a disciplined risk profile.
Aidan Lesslie, relationship manager at Avamore Capital, commented
“This was a great example of a borrower with a clear vision for repositioning an asset, and our role was to provide the flexibility and certainty to help bring that plan to life. With multiple stakeholders involved and a number of moving parts across the legal structure, it was important that we remained proactive and solutions-focused throughout. Maintaining momentum and clear communication across all parties ultimately ensured we were able to deliver within the required timeframe.”
A short-term bridge-to-let facility was arranged to support the purchase and refurbishment of a three-bedroom detached property in the South East of England. The borrower, a foreign national investor, had secured the property at auction and required a fast, flexible funding solution to meet tight completion deadlines while also financing the refurbishment works. As the LTGDV remained comfortably within criteria, the lender was able to fund 100% of the refurbishment costs alongside the purchase. The property required full modernisation, including EPC improvements, a new kitchen and bathroom, and wider cosmetic upgrades throughout. The borrower’s intention was to refinance onto a long-term BTL product once works were complete and operate the property as a single AST investment.
The bridge-to-let facility was structured over a 12-month term, providing sufficient flexibility for both the refurbishment works and refinance. However, the borrower completed the project within just four months,
allowing them to refinance significantly earlier than anticipated onto a lower-cost BTL facility. This improved the overall cost efficiency of the transaction and supported the borrower’s long-term investment strategy. As the transaction moved from the bridge onto the term product, the borrower also avoided paying for additional legal work, helping reduce costs further and streamline the process.
The refurbishment works added both equity value and increased rental income potential, enabling the borrower to refinance at 75% LTV and recycle a higher level of equity into future investments. The client also benefited from a 0.15% reduction in the BTL interest rate through a feature available within the bridge-to-let product.
Throughout the transaction, the broker worked closely with their BDM, Ben Pike, and the same underwriter from start to finish. This continuity helped keep the process efficient and straightforward, ensuring the borrower did not need to resupply documentation unnecessarily during the transition from bridging finance onto the long-term mortgage. The structure also created additional value for the broker, who benefited from procuration fees on both the bridging facility and the subsequent BTL refinance.
Refurb facility: £87,000
Term: 12 months/five-year fixed
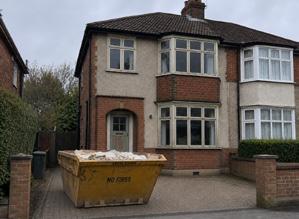
A married couple approached us after securing planning permission to build a detached home on land surrounding their existing property. The husband, a self-employed builder with 25 years’ experience, planned to build the new home, move in, then sell the existing property to repay the loan.
They also needed to buy a small neighbouring plot to preserve the existing home’s rear garden once the titles were split and required a quick completion to begin construction during the spring/summer build window.
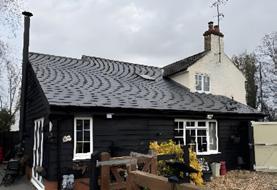
The day-one advance needed to redeem the existing £139,000 first charge, fund the neighbouring land purchase and provide enough capital to start the build. As the facility was regulated, additional safeguards were required around the exit strategy and future sale of the borrowers’ main residence.
We issued fully credit-backed terms on the same day as enquiry and instructed all professionals immediately.
Loan size: £418,000
Loan term: 12 months
LTV and/or GDV: 35% LTGDV
Reason for the loan/loan use: Self build + redeem first charge + fund neighbouring land
Exit plan: Via sale
Time taken to complete: Eight weeks
Rate: 1.14% per month
Despite increased build costs and a lower-than-expected valuation on the existing property, we delivered a £418,000 regulated loan with a max facility of £479,000 at 1.14% per month, with interest rolled up over 12 months. The £222,000 day-one advance cleared the existing charge, funded the land purchase and started the build, with three further £57,000 drawdowns released subject to satisfactory monitoring surveyor reports. A fixed-price build contract was also required for cost certainty.
Additional conditions included marketing the existing property by month six, discharging planning conditions and arranging warranty and building
regulations sign-off before completion.
The borrowers could build on their own land without selling their home upfront or sourcing an external site. Including the neighbouring plot within the same facility protected the value and saleability of the existing property.
Rolled-up interest and staged drawdowns kept the structure simple, while a day-one LTV of 43% and LTGDV of 35% against a £1.375m valuation provided strong equity headroom and a clear exit strategy through the sale of the existing property.
Want to highlight a recent deal? Don’t miss the opportunity to be featured in our next Deals of the Month Special.
Whether you have an impressive case study, an innovative deal, or a unique achievement, we want to hear from you.
Contact us today to secure your spot.
Let’s make