MSLG MARCH 2026 CASE STUDY

MSLG MARCH 2026 CASE STUDY
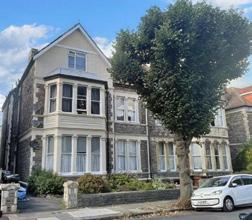
Loan size: £600,000
Loan term: 12 months
LTV: 75%
Reason for loan: Funding to support the purchase of seven fully tenanted flats
Location: Bristol
Exit plan: Retain and refinance the asset as repayment
Time to fund: 10 days from offer to completion
Broker/Borrower/Relevant parties: Relationship manager
Ash Kendall, Underwriter Mike Watson, Processor Rubie Downes
Jordan Winter at Mortgage Lane approached us to support his client with the purchase of a seven-property residential portfolio in Bristol. It was a time-sensitive deal requiring speed and flexibility, so naturally, MS Lending Group was the lender of choice. We provided £600,000 gross at 75% LTV against a portfolio valuation of £800,000, secured across seven flats and supported by a desktop valuation that was completed in just two working days. With the flats already tenanted and no works required, we were able to fund the deal in just 10 days from offer to completion, allowing them to progress with their investment strategy. This is exactly what we do best at MS Lending Group: delivering fast, flexible, and reliable bridging finance for more complex property transactions.
Jordan commented: “MS Lending Group were excellent on this transaction. With another lender pulling out of the deal at the last minute, we were extremely up against it time-wise. Considering it was a complex deal, the combination of flexibility and time to completion was just what we needed, and from experience, I don’t know another lender who could deliver like this. Thanks to all the team at MSLG, we look forward to more deals.”
A £670,000 structured acquisition and refurbishment facility has enabled the redevelopment of a poorly presented residential asset in Wimbledon, transforming a dated property into a significantly enhanced family home in a prime commuter location.
Situated within a five-minute walk of Raynes Park Station, the property offered strong fundamentals but required extensive remedial works and reconfiguration to realise its full market potential. The borrowers identified an opportunity to reposition the asset through structural improvements, a ground-floor wraparound extension and a loft conversion.
Upon completion, the scheme will increase the gross internal area by 51%, delivering a substantially larger living space at ground level and creating a five-bedroom layout across three floors. The clear exit strategy is a sale following completion of works.
The transaction was initially structured as an acquisition planning bridge. However, as
planning progressed and the scope of works became clearer, it became evident that a full acquisition and refurbishment facility would provide a more efficient and commercially aligned funding solution.
Rather than require the borrower to refinance or restart the process, the facility was restructured mid-transaction to accommodate both acquisition and works funding within a single facility.
The final structure delivered leverage of 73% LTV on day one and 65% loan-to-gross development value over a 12-month term, priced at 0.69% per month. Crucially, the revised facility ensured sufficient capital to fund the proposed refurbishment while maintaining appropriate headroom against the projected GDV.
Timing was central to the transaction. The borrowers were keen to align completion
with the granting of planning permission to enable immediate commencement of works.
By restructuring the facility and progressing the deal in parallel with planning, the funding allowed the borrowers to maximise the effective term of the loan. Works could begin post-completion immediately, reducing idle time and accelerating the route to market.
The transaction was completed within eight weeks.
The property’s original condition required careful underwriting. Structural remedial works, significant extension plans and a substantial uplift in floor area introduced complexity that required a clear understanding of costings, programme and exit strategy.
The final facility was structured to ensure that funding levels were sufficient to deliver the refurbishment in full, while maintaining disciplined leverage against both day-one value and projected GDV.
By increasing the GIA by more than half and reconfiguring the internal layout to meet modern family demand, the project is expected to deliver a materially stronger resale proposition in a competitive South West London market.
This transaction highlights the importance of flexibility in refurbishment-led bridging. Development projects rarely remain
static. Planning evolves, scope expands and funding requirements shift. The ability to restructure quickly — without compromising momentum—can be the difference between a delayed project and one that proceeds seamlessly.
In this case, adapting the facility from a planning bridge to a full acquisition and refurbishment loan ensured continuity, preserved time and provided the borrower with the capital confidence required to move forward immediately.
For borrowers undertaking value-add projects, structuring finance around both opportunity and timing remains critical. When executed effectively, it allows underperforming assets to be repositioned efficiently and brought back to market in significantly enhanced form.
Loan structure: £670,000
Term: 12 months
LTV: 73%
LTGDV: 65%
Rate: 0.69% per month
Purpose: Acquisition and refurbishment
Exit: Sale on completion
Having just completed a strategic merger, a well-established law firm needed finance to purchase a larger office in central London that would be suitable for the expansion of the firm.
Following the merger there was some urgency–to ensure a smooth transition and greater cohesion for the firm, more office space was a priority.
The firm identified a suitable property that they wanted to use as their new flagship headquarters. The challenge was that they needed £3m in five weeks to complete the purchase and ward off competition for the office space from other parties.
While most commercial lenders would flinch at the scale of the transaction and the short timeline, West One was ready to commit the resources necessary to get it done in time.
We structured a facility at £3m at 65% LTV over a 10-year term. Legal was instructed parallel to the valuation to streamline the process and our 24hr response window on all communication allowed us to streamline communication between all parties and achieve completion within the required deadline.
By delivering the commercial mortgage in just five weeks from enquiry to completion, West One enabled the law firm to secure their new premises without disrupting operations after their merger. The deal showcases West
One’s ability to deliver large-scale commercial finance with exceptional speed and coordination on cases with demanding timelines. The broker who worked with us commented: “I needed a dynamic lender that could work quickly with a fast-paced transaction in the city of London market…The importance of speed and prompt high level decision making was key.”
To discuss a commercial case with
£13m commercial loan helps Turkish wholesaler chain refinance and reinvest
Loan size: £13m
Loan type: Commercial term
Loan term: 240 months
LTV: 64%
Reason for loan: Refinance and invest in essential equipment upgrades
General transaction details:
When their existing bank lender’s appetite changed, a long-established Turkish wholesale chain found itself with just weeks to secure new long-term funding for a multi-million-pound refinance of its outstanding debt.
Together, supporting broker Crystal Specialist Finance quickly got to work assessing the case. Our expert underwriting team carried out detailed property and valuation assessments, including unravelling ownership of the main security—a warehouse being used by several of the client’s businesses, to ensure that it was a viable security.
After analysing the company’s complex finances and layered corporate structure, we provided a £13m commercial term loan within the tight deadline. This allowed the client to refinance, avoiding any penalties from their existing lender, and access additional capital to reinvest in the business.
David Parke, lending manager at Crystal Specialist Finance, commented:
“Finding solutions is what we love at Crystal. The borrower needed funding quickly to support their growth and cost-saving strategy, so clear communication and close coordination across all stakeholders—including valuers, solicitors, and the wider team—were essential in navigating a complex transaction and agreeing a well-structured finance package.
35 new homes_York3.png
“The client’s long-standing banking relationship had shifted due to a change in appetite, leaving them seeking a lender who could support their evolving needs and future growth. After carrying out market due diligence, it became clear that Together was the right long-term funding partner.”
Emma Goodyear, senior underwriter at Together, commented:
“By working collaboratively with all parties and adopting a bespoke, solution-led approach, our team and Crystal were able to overcome the challenges and deliver funding within a demanding timeframe, while effectively managing risk. Cases like this are a key part of what we offer at Together.”
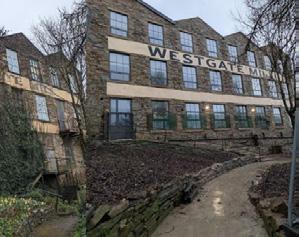
Roma Finance was approached to support a borrower who had recently completed the conversion of a disused three - storey commercial mill in Burnley into residential apartments.
The borrower, an experienced developer with extensive knowledge and experience in refurbishment and commercial to residential conversions, originally purchased the mill unencumbered. Roma provided a facility covering 100% of the build costs, enabling the transformation of the building into 10 one-bedroom and three two-bedroom apartments following the approval of full planning consent.
With the development now complete, the borrower required additional capital to move on to their next project. Roma was able to internally refinance the asset onto our developer exit product, allowing them to release equity and generate essential cash flow for their next scheme.
The funds are now being used to acquire a vacant end terraced commercial property in Radcliffe, Manchester. Formerly a furniture showroom and currently in poor condition, the site benefits from planning permission for 18 residential units, comprising 17 one-bed apartments and one two-bed duplex.
The borrower’s intended strategy is to progress this new development using the capital raised, demonstrating the strength of Roma’s development exit solution in supporting project growth and continuity. Senior underwriter, Jack Ainsworth, commented:
“It was fantastic to support our borrower on this case by utilising our developer exit solution. The refinance not only strengthened their cash flow but also allowed them to maintain momentum without monetary interruption. It’s great to see our funding play a part in helping borrowers, such as this one, progress from one scheme to the next. I look forward to seeing how the next project develops.”
Loan size: £850,000
Initial advance: £850,000
CMV: £1,215,000
Term: 12 months
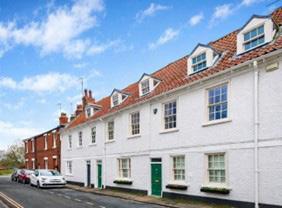
Loan size: £175,000
Trustpilot review from the broker:
“As a broker firm, we recently completed a bridging loan with this lender and had a very positive experience from start to finish. The process was handled efficiently, and the team demonstrated a clear understanding of the urgency that often comes with bridging finance.
A special mention goes to Rick and Agne, who were excellent throughout the application and completion process. They were professional, highly responsive, and always available to provide updates or clarify any points along the way. Their proactive communication and attention to detail made it much easier for us to keep our client informed and ensured the transaction progressed smoothly.
From a broker’s perspective, it’s always reassuring to work with a lender that is reliable, transparent, and committed to getting deals completed. Thanks to the support of Rick and Agne, the loan was completed on time and exactly as expected. We would be very happy to work with this team again and would confidently recommend them to other brokers looking for a dependable bridging lender.”
Loan term: 12 months
LTV: 52%
Reason for the loan/loan use: The borrowers are raising capital for business purposes via second charge over their main residence
Exit plan: Sale
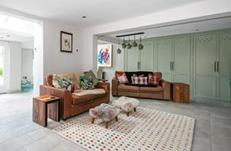
General background details about the transaction: The borrowers are raising capital for business purposes via a second charge over their main residence. The property is a high-spec converted Grade II building in Beverley, dating back approximately 400 years. It offers a unique blend of historical elegance and modern convenience. It has four bedrooms, three formal reception rooms, an open-plan kitchen and dining space, and a landscaped garden.
Time taken to complete: 26 working days. Application from Janurary 28th to completion in March 5th
Broker/borrower, or any relevant parties involved: Ryan Jones and Estelle Baker from We Are Premier Rate: 0.97%
Avamore Capital completed six transactions totalling £11m in a single month, all introduced by a single broker, underlining the strength of its intermediary relationships and its ability to deliver across complex structures at a fast pace.
The broker, a one-man-band operator and active developer, has worked closely with Avamore for the past 12 months, building a relationship grounded in collaboration and commercial alignment. The first segment of deals involved four high-spec HMO refurbishment facilities in South East London, totalling approximately £3.15m. The loans were provided to separate SPVs for a high-networth investor assembling a premium HMO portfolio within Article 4 areas. Avamore structured the facilities at 75% day-one LTV against OMV and funded 100% of the build costs in arrears, while also enabling an equity release from the existing lender. The schemes involve upgrading and extending properties to create fully en-suite, highspec accommodation aimed at young professionals. Enhanced KYC checks were undertaken due to the borrower’s foreign national status, and although the client was
a first-time developer, strong contractor experience supported the credit case. The second segment of deals involved two large loans in Bristol. Avamore funded the £3.2m purchase and light refurbishment of a fully tenanted 24-flat block under a tight three-week deadline ahead of the Autumn Budget, structuring the transaction at 85% LTV against the purchase price with refurbishment costs funded in arrears. The final transaction was a £4.5m multi-site portfolio acquisition in Bristol, secured against two separate flat blocks and a pair of semi-detached houses; structured as a company share purchase, it required enhanced legal due diligence and careful underwriting, with all units income-producing at completion and the structure accommodating additional complexity around title arrangements.
George Ormerod, relationship manager at Avamore Capital,
said:
“Completing six deals with one broker in a single month demonstrates what can be achieved when there is genuine alignment and trust. These transactions involved first-time development, share purchases, tight deadlines and valuation challenges, but through collaboration and decisive underwriting, we were able to deliver.”
A broker introduced a married couple looking to refinance their existing mortgage and cover ongoing litigation costs. They required a £1.3m bridging loan, split into two drawdowns of £1m and £250,000, secured against their residential property in Worcester. Both advances were allocated to legal fees and supported by invoices.
The exit strategy was either a litigation settlement or sale, with completion targeted for August 2025 following a three-month extension from their existing lender.
The primary exit relied partly on an ongoing litigation claim, with no binding settlement in place at completion. The property was also down-valued from £3m to £2.3m, increasing LTV from 60% to over 70%.
Staged drawdowns tied to legal costs required tight controls on fund release. The short extension from the existing lender also meant valuation and search documents risked expiring before completion, adding time pressure.
Originally approved in March 2025, the loan was completed in January 2026.
During this period, we maintained close contact with all parties to ensure the structure remained suitable.
Following a senior review, terms were revised to £1.3m at 70.37% LTV, priced at 0.94% over 12 months. The facility included two drawdowns, with the second conditional on legal invoices.
We also built in an exit discipline: the property was to be listed within four months unless a settlement was reached. A repayment progress update was required within eight months, alongside a commitment to sell if needed.
The clients refinanced without a forced sale. Legal costs were funded in a controlled, phased way, giving them time to pursue a settlement while maintaining a clear fallback option.
Loan structure: £1.3m
Term: 12 months
LTV: 70%
Reason for the loan/loan use: Refinance their existing mortgage and cover ongoing litigation costs
Exit plan: Sale
Time taken to complete: 10 months
Rate: 0.94%
Jim Baker, sales director at Masthaven Finance, commented:
“In the world of bridging, 10 months is basically a lifetime. But that’s exactly how long this £1.3m refinance took to get over the line. Originally approved in March 2025 and completed in January 2026 - it wasn’t fast, and it certainly wasn’t pretty. But it got the clients out of a tight corner without a forced sale, which is the result that actually matters. Sometimes the best thing a bridging lender can be is persistent.”
Want to highlight a recent deal? Don’t miss the opportunity to be featured in our next Deals of the Month Special.
Whether you have an impressive case study, an innovative deal, or a unique achievement, we want to hear from you.
Contact us today to secure your spot.
Let’s make