EXCLUSIVE
I S S U E 4 6 J U LY/AU G 2 0 26
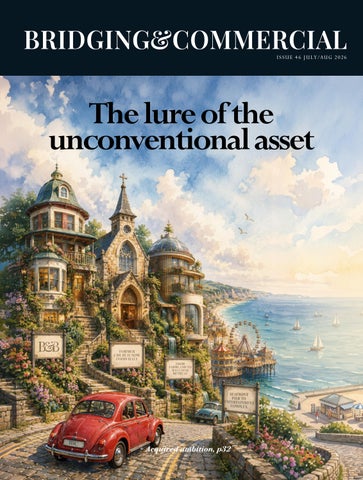
The lure of the unconventional asset
+ Acquired ambition, p32
EXCLUSIVE
Bridging & Commercial
2
EXCLUSIVE
United, we go further I s s ue 4 6 Ju ly/Au g 2 0 26
Easy journeys for smart users
A new bridging portal designed to help brokers work smarter and go further UTB's new portal has been developed to give our broker partners more control over their bridging cases and to provide them with an easier journey. Key benets include DIP responses within minutes, 24-hour access and easy case tracking, meaning brokers can avoid time-consuming emails and phone calls and can keep their customers updated. www.utbank.co.uk/intermediaries
Asset Finance | Mortgages, Buy to Let & Bridging | Property Development | Structured Property Solutions | Savings & Deposits For intermediaries only
1
July/Aug 2026
Acknowledgments Editor-in-chief Beth Fisher
Magazine manager Dhuha Al-Zaidi
Creative direction Beth Fisher Dhuha Al-Zaidi
Sub editor
Christy Lawrance
Contributors
Kate Cowan, Stuart Dunk, Tom Cantor, M Stars Programme, Sam Herd, Paul Weitzkorn, Steve Palfreeman, Adnan Ali, Luke Watson, Phil Derbyshire, Justin Friend, Sidorela Taylor, Ben Pike, Gavin Diamond, Nick Grant, Uma Rajah, Sophie Meller, Josh Knight
Photography Connie Burke
Sales and marketing Beth Fisher beth@medianett.co.uk Ellen Townsend ellen@medianett.co.uk
Special thanks
Cover story respondents Niamh Carolan, Rosely Group SQ1 Team
Printing Jam Print
Design and image editing BePro
Bridging & Commercial Magazine is published by Medianett Publishing Ltd
Managing director
Beth Fisher beth@medianett.co.uk 0203 818 0160 Follow us: LinkedIn @Medianett Publishing | Instagram @medianettpublishing
To read about our commitment to the environment and sustainable print publishing, please visit https://bridgingandcommercial.co.uk/page_magazine. Bridging & Commercial
2
T
here are moments when an industry quietly redefines what it means to be a specialist. Not through sweeping policy changes or dramatic market events, but through thousands of individual lending decisions that gradually reshape where capital flows, what opportunities emerge, and how brokers create value for their clients. This edition of Bridging & Commercial is our Super Specialist Issue, exploring where today’s opportunities are being found and what they tell us about the future of specialist property finance. The message is clear: the era of straightforward lending opportunities is fading. The brokers thriving in today’s market aren’t simply finding deals; they’re uncovering niches. They’re financing assets that require deeper expertise and a willingness to look beyond conventional property investment. Across these pages, we examine where those opportunities are emerging. We explore the lenders leading in this, the opportunities brokers are identifying before the wider market catches on, what valuers are seeing on the ground, and how today’s economic pressures are reshaping investor priorities. Nowhere is that more evident than in our cover story. ‘The Lure of the Unconventional Asset’ [p44] explores corners of the market that, not so long ago, many lenders would have politely declined. Today, these are becoming compelling areas of specialist finance. As equity becomes harder to stretch, ground-up developments become tougher to exit, and traditional opportunities become increasingly competitive, borrowers are creating value in places others overlook. We delve into church and barn conversions, data centres, technology-led aparthotels, and even an amphibious home designed to embrace flood risk rather than avoid it. The low-hanging fruit has largely disappeared. Success increasingly belongs to those prepared to understand assets that don’t fit neatly into conventional lending criteria. That same theme of specialist expertise runs throughout this edition. We sit down with Funding 365 following one of the most significant milestones in its history [p32]. Fresh from completing its acquisition, the lender reveals how increased financial firepower will allow it to raise LTVs, broaden the security types it will consider, sharpen pricing, and up its maximum loan sizes. In an extraordinary coincidence of timing, it also finalised a £300m funding line from a global investment bank on the very same day the acquisition completed—a powerful example of how institutional confidence ultimately creates greater opportunities for brokers. Elsewhere, Allica Bank reflects on the remarkable growth of its bridging proposition since acquiring Tuscan Capital [p82], sharing its ambition to reach £500m of new lending by 2027 and the role specialist expertise has played in that journey. Lendco examines the rise of the bridge-to-let loan [p96], arguing that what was once considered a niche solution is increasingly becoming one of the simplest, quickest and most commercially effective routes for brokers and borrowers alike. GB Bank explores the complexities of lending against assets with overseas ownership structures [p88], demonstrating how specialist underwriting can unlock opportunities that many mainstream lenders continue to avoid. CapitalRise reflects on how borrower and broker priorities have evolved over the past decade [p74], concluding that deep sector knowledge has never been more valuable in helping clients navigate an increasingly fragmented market. MT Finance looks back on the first year of its commercial mortgage proposition [p62], discussing the challenge of persuading brokers to trust an established bridging lender with longer-term lending requirements—and why those relationships are now delivering strong results. Meanwhile, Goldentree makes the case for in-house legal expertise, explaining how bringing legal teams closer to lending decisions can identify risks earlier, improve efficiency and deliver greater certainty throughout the transaction process [p92]. Taken together, these stories paint a picture of an industry that is becoming more nuanced than ever before. Being a ‘specialist finance broker’ is no longer enough. Today’s market rewards the super specialist—those who understand the emerging asset classes, recognise opportunity where others see complexity, and have the confidence to solve increasingly sophisticated borrower challenges. As the market continues to evolve, one thing is becoming increasingly clear: tomorrow’s winning deals won’t necessarily come from the biggest opportunities. They’ll come from the most specialised ones. As always, we’d love to hear your thoughts.
Beth Fisher
3
July/Aug 2026
Scan me
10 20 32 44 62 70 “Truthfully, of the £250m of sales we did last financial year, just under 50% were on behalf of receivers and administrators—that’s the amount of distress we’re seeing in the market” - p44
74 82 96 114 116
The Cut News
Starmer’s out. What now for lenders?
Transparency in focus with new broker-led ratings system / Creating the next generation of SME property developers
Exclusive
How acquisition has changed Funding 365
Cover Story Interview
Unravelling the UK’s hidden opportunity map
Nick Grant
On The Rise Experience Explained Opinion
Sophie Meller
CapitalRise looks back on 10 years in business
Allica Bank reflects after Tuscan Capital acquisition/ Turning complex cases into opportunities/ Goldentree makes the case for in-house legal teams
The growing case for bridge-to-let /Recognise Bank takes a wider lens on complex deals /Why experience still counts/ Planting the seeds of client growth
Limelight Backstory
Masthaven celebrates summer and Three Peaks charity climb
Josh Knight
THE CUT
The Cut
Change at the top: now what? Andy Burnham became the country’s fourth prime minister in five years when he replaced Sir Keir Starmer in July. We asked specialist finance experts about the ramifications of this—including around land value tax—and immediate concerns
11
July/Aug 2026
The Cut
Kate Cowan
Chief financial and operating officer at Hope Capital Property Finance For property investors, the significant development is the renewed discussion of a land value tax. That conversation was already building before Sir Keir Starmer went, driven by Andy Burnham’s rising popularity, and his return to Westminster has given the policy real traction. Burnham has long been associated with replacing council tax with a land value tax, so investors are now weighing up not just a change of leadership but also the prospect of ideas once considered politically distant moving into the mainstream. In the short term, I expect volatility driven by sentiment. Media interest has been intense and, whether or not it is justified, that coverage feeds sentiment, and sentiment alone is often enough to move markets. What we are seeing is a reaction to the possibility of disruption rather than to any certainty. Over the medium term, the concern is not the principle of the tax but the speed and manner of any implementation. If investors and homeowners come to believe reform could reduce house prices, even marginally, expectations may shift quickly. In a highly leveraged market, falling valuations can tighten lending conditions, weaken consumer confidence and, in more severe scenarios, raise the risk of a credit event. .
Stuart Dunk
Finance and treasury director at Morpheus Lending Markets had already priced in Starmer’s resignation, with sterling down 3% since February and gilt yields rising, so the real question is how they will react to what comes next. Andy Burnham emerged as the only candidate and has sought to reassure markets through his commitment to Labour’s existing fiscal principles and early engagement with economic experts. Gilt yields dropped after the Makerfield by-election, an early sign that markets favour certainty of both outcome and policy.
Bridging & Commercial
12
The Cut
HOW DO YOU EXPECT MARKETS TO RESPOND IN THE SHORT AND MEDIUM TERM TO THE NEW PRIME MINISTER? Tom Cantor
Co-head of short-term finance at West One In the short term, very little. Starmer’s exit and Burnham’s arrival were well trailed, so the market has largely priced them in. The medium term hinges on policy and, above all, on what the new chancellor’s plans are for tackling the nation’s debt pile, closing the fiscal gap and boosting economic growth. If Burnham and his chancellor can convince the market that they have the answer to those key questions, it will lower the UK’s borrowing costs and, ultimately, that should bring down the cost of finance. Therefore, the sooner they set out those plans, the better.
13
July/Aug 2026
The Cut
DOES THE UK’S ECONOMIC OUTLOOK STILL LOOK PROMISING TO INVESTORS, OR IS IT CAUSING UNCERTAINTY?
Stuart Dunk
Finance and treasury director at Morpheus Lending The UK housing market has long been seen as a safe harbour for domestic and international investors; however, 2026 has brought a well-documented contraction in sales activity, with house price projections further complicated by regional variation. The UK’s muted economic outlook has been less impactful on investor sentiment than regulatory change, as smaller landlords struggle to keep pace with Making Tax Digital, EPC requirements and stamp duty land tax tiering in the wake of May’s Renters’ Rights Act. With reports of £48bn in rental property value wiped out and 93,000 landlords exiting the sector, it would be easy to assume the market is no longer compelling. Yet a changing face of UK property investment is emerging, as these assets are consolidated into larger landlord portfolios and institutional build-to-rent stock. This shift, while not yet replacing lost rental supply, suggests the UK market is still seen as safe as houses. For investors doubling down in the UK, uncertainty brings opportunity: a bounty of well-priced rental stock is being marketed for swift sale, and working with the right financing partner can offset the risk of deals collapsing owing to seller anxiety.
Bridging & Commercial
14
The Cut
Kate Cowan
Chief financial and operating officer at Hope Capital Property Finance It creates uncertainty, and markets are right to price in the possibility of disruption. But the debate needs to consider the historical perspective. Taxing land values is far from a new idea; variations have circulated in British politics for more than a century, and it formed part of the 1909 People’s Budget, passing the Commons before meeting opposition in the Lords. That it has resurfaced so often points to both its political appeal and the practical difficulty of implementing it without major disruption. For that reason, I remain sceptical that Britain is on the verge of a fundamental restructuring of property taxation. The short-term consequences of a rapid transition would likely be severe enough to keep policymakers cautious. I read the proposal as a near-warning sign for markets, not a signal of lasting change and, on that basis, the underlying outlook for investors has not fundamentally shifted.
Tom Cantor
Co-head of short-term finance at West One The UK economy has a lot going for it, but it is no longer the easy sell to investors it used to be. Growth is middling and there’s a sense that excessive red tape and high taxes are holding it back. The elephant in the room is the prospect of some form of wealth tax, which Andy Burnham has played down but not ruled out. If the UK wants to be seen as a magnet for investment, that sends the wrong signal. In the longer term, the UK, as a services-led economy, should be well placed to reap the rewards from the diffusion of AI. But until there’s a clearer, pro-investment signal on tax and growth, the UK will keep trading below its potential in investors’ eyes. .
15
July/Aug 2026
The Cut
Kate Cowan
Chief financial and operating officer at Hope Capital Property Finance For short-term lenders, the biggest risk sits with exits. A levy designed to double for second homes, overseas buyers and empty properties would compress investment yields and could slow both sale and refinance activities—the two exits on which every bridging loan ultimately depends. Caution will persist until greater certainty emerges. The opportunity comes from that same lack of certainty. History shows that uncertainty often creates opportunity, and those willing to look beyond the immediate noise and identify value before confidence returns may be best placed when it does.
Stuart Dunk
Finance and treasury director at Morpheus Lending The biggest concern for homeowners and investors, particularly in London and southeast England, is that Andy Burnham will overhaul property taxation, with his preference for a proportional property tax, which is likely to push down capital values of high-value properties. In practice, any implementation is hugely complex, with devolved powers, logistical hurdles and political obstacles to clear before such a seismic shift in property taxation can be enacted.
Bridging & Commercial
16
The Cut
WHAT IS THE LARGEST OPPORTUNITY AND THE BIGGEST RISK CREATED BY THIS CHANGE IN LEADERSHIP? Tom Cantor
Co-head of short-term finance at West One The biggest risk is continued uncertainty. We’ve had six prime ministers and eight chancellors in the past 10 years, which puts off foreign investors looking for a home for their money. Andy Burnham also arrives as something of an unknown at this level and he now faces the added pressure and scrutiny that come with Number 10. Ultimately, we need him to succeed and restore a sense of stability that has long been absent from British politics. The biggest opportunity is housebuilding, which is clearly high on Burnham’s agenda, though reports so far suggest the focus will be on council and public housing. That’s welcome. But we’d urge him not to ignore private housebuilding, which contributes more than £46bn a year to the economy. If he can give private builders the conditions to flourish, it will help drive the growth needed to fund his wider agenda.
17
July/Aug 2026
BREAKING Think you know Octane? Think again.
0.69% 2%
Rates from
Proc Fee
ls a V e t o m e R & AVMs
Up to 75%
NEWS This year, we’re raising our game to deliver even more value where it matters most.
Fixed Rates le b ia r a V s a e t a r e Sam
OMV Va luations We le nd again st OMV, not 180-d ay
0345 222 9009
deals@octanecapital.co.uk
octanecapital.co.uk
For use by mortgage intermediaries only. Rates can go up or down with BBR. Octane Capital is a trading name of Aldermore Bank PLC. Aldermore Bank PLC is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (Financial Services Register number: 204503). Registered Office: Apex Plaza, Forbury Road, Reading, RG1 1AX. Registered in England. Company No. 947662. Invoice Finance, Commercial Mortgages, Property Development, Buy-To-Let Mortgages and Asset Finance lending to limited companies are not regulated by the Financial Conduct Authority or Prudential Regulation Authority. Asset Finance lending where an exemption within the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001 applies, is exempt from regulation by the Financial Conduct Authority or Prudential Regulation Authority.
NEWS
The specialist finance industry is set to gain a new way to measure lender performance with the launch of the M Stars Programme, a broker-led ratings platform that aims to provide an independent assessment of service standards across the market
Words by
M STARS PROGRAMME
BROKER-LED
launches amid growing scrutiny of specialist finance lender performance The initiative was developed in response to growing concerns around trust and transparency in the specialist lending market. Shaped by industry peers, including figures from across the compliance and legal community, it aims to shift the balance by giving brokers—the lenders’ clients—the opportunity to assess performance based on their real-world experiences. By drawing on verified data and factual information from genuine transactions, the programme is designed to provide an evidence-led assessment of lender performance and create what its founders believe will be one of the industry’s most credible and meaningful accolades.
Operational control and oversight will be handed entirely to industry veteran Ray Cohen, supported by an independent panel of sector experts who will serve as adjudicators. “This initiative is designed to provide independent assessment of lenders’ service performance with criteria set to ensure that it works for all types of firms, small to large, and bridging to development finance,” said Ray. “There is careful monitoring with sense checks in place to ensure the results are fair. “As the programme develops, this will provide more regular reporting on service standards. “This should be of help to both the intermediary community and the lenders themselves, by way of performance feedback.
Bridging & Commercial
20
NEWS
“If lenders use this to improve their service, it can only be a good thing for consumers.”
deteriorate. “Today’s angel can become tomorrow’s demon.”
Jonathan Newman, senior partner at Brightstone Law and fellow adjudicator, added: “Bridging lenders interact with a number of stakeholders, but tend to operate in silos.
The M Stars Programme has been designed to address that gap. The programme relies on a network of approved, anonymous broker Evaluators who submit assessments of lenders based on real-world transactions. Performance is measured quarterly across a range of criteria, including communication, underwriting quality, completion times, responsiveness, customer understanding, and lending appetite.
“So, an independent data-based benchmark available to all—lenders, brokers, surveyors, and the like—is a real innovation in the sector. “I expect it to drive better outcomes for customers but, equally as important, this will be an invaluable source of real feedback, which lenders can take away to concentrate on aspects of their offering, as well as benchmarking themselves against their peers and the industry as a whole.”
The data is then analysed by an AI-driven system developed under Ray’s supervision. According to the founders, the platform is designed to identify anomalies, discount outlier submissions, and prioritise consistent performance trends over individual experiences.
The scheme aims to create an independent industry standard for service excellence.
To avoid marketing bias, the objective is not to identify the lender with the most market visibility, but the lender that consistently delivers.
The project comes at a time when confidence in parts of the specialist property lending sector has been tested by a series of high-profile disruptions, funding issues, and lender failures.
In an industry where reputation is often shaped by marketing budgets, conference presence and deal announcements, the founders argue there remains limited independent data on operational performance.
For brokers, the consequences have been tangible: delayed completions, increased due diligence requirements, and a growing burden of assessing which lenders remain reliable counterparties.
That absence has become more apparent as recent market events have exposed the gap between perception and reality.
“The most common question we receive is surprisingly simple,” a spokesperson for the M Stars Programme said. “Who can I trust?”
“Trust is the industry’s most valuable currency,” a spokesperson for M Stars Programme said. “Once it’s damaged, rebuilding it is significantly harder than generating new business.”
It is a question that has become increasingly difficult to answer.
Participation in the programme is restricted to approved brokers. Applicants must undergo a vetting process, sign confidentiality agreements, and contribute reviews across a minimum number of lenders. Individual submissions remain anonymous, while ratings are generated only after sufficient volumes of data have been collected.
Awards programmes, broker surveys, and league tables offer useful indicators of market standing, but they are inherently retrospective. They capture performance at a particular moment in time, while the underlying businesses continue to evolve. Management teams change. Funding structures shift. Credit appetite expands and contracts. Service levels improve, or
The resulting accreditation system awards lenders between
21
July/Aug 2026
NEWS
one and three stars, subject to annual review and ongoing monitoring. Unlike traditional awards, accreditation is not permanent. Lenders can lose their status if evidence emerges of serious misconduct or material deterioration in service standards. The model represents an attempt to introduce a more continuous form of accountability into a market that has historically relied heavily on relationships, reputation, and anecdotal feedback. The programme’s success will depend largely on participation levels and the willingness of intermediaries to contribute data consistently over time. What is clear, however, is that the sector’s appetite for greater transparency appears to be growing.
“ Trust is the
industry’s most valuable currency. Once it’s damaged, rebuilding it is significantly harder than generating new business”
For a market built on trust, the M Stars Programme is effectively making a wager: that enough brokers are prepared to help measure it. Applications for broker Evaluators are now open, and brokers can register by scanning the QR code.
Bridging & Commercial
22
Your industry needs
YOU
Give the specialist lending sector back its strength by becoming an Evaluator
REGISTER NOW | mstars.co.uk
Simplified products for a complex world.
Our Bridging finance product with up to 80% LTV
Our Refurb loan with up to 90% LTV
Our Bridge product is perfect for Borrowers requiring fast finance. Ideal for the purchase and refinance of residential BTL and HMO properties as well as commercial investments.
With full flexibility around the servicing of interest and no mid-term valuations, our Refurb product is ideal for the purchase and light refurbishment or conversion of residential BTL and HMO properties.
Key Features
Key Features
• Loan size £75,000 - £3,000,000
• Up to 90% LTV day one
• No minimum term
• No minimum term and up to 12 months
• Cosmetic works permitted
• Interest can be serviced or deducted
• Interest can be serviced or deducted
• Dual Representation available on kerbside residential properties
• Heavy adverse credit considered where exit is sale • Second charge loans considered • Dual Representation available on kerbside residential properties • AVMs and Desktop Valuations considered
Our Development finance product with up to 70% GDV Our Development product offers up to 70% LTV and 100% of works as well as no mid-term valuation, ensuring its suitability for a wide range of property projects. Ideal for development schemes of up to £1,000,000 that result in up to 4 houses or 6 flats.
Key Features •
Loan size £75,000 - £3,000,000
•
Up to 100% of works
•
First time developers accepted
•
We have extensive garden plot and commercial to residential experience
Contact us today. 0161 710 2006
|
hello@mintpf.co.uk
|
mintpropertyfinance.co.uk
what MORTGAGE AWARDS
what MORTGAGE AWARDS
what MORTGAGE AWARDS
what MORTGAGE AWARDS
what MORTGAGE AWARDS
what MORTGAGE AWARDS
what MORTGAGE AWARDS
what MORTGAGE AWARDS
- 2019 W INNER -
- 2020 W INNER -
- 202 1 W INNER -
- 2022 W INNER -
- 2023 W INNER -
- 2024 W INNER -
- 2025 W INNER -
- 2026 W INNER -
NEWS
t r d e evel p x e op t n er a W
s?
row your own
Specialist lenders want to lend to clients with expertise—so they should invest in aspiring developers to help create the next generation of confident, able SME borrowers. Mint’s First Time Developers Academy aims to do this
Words by
SAM HERD
Head of credit at Mint Property Finance
Every experienced property developer once submitted their very first development finance application. It’s an obvious statement, but one I don’t think our industry reflects on often enough. The government has focused its attention on planning reform, housing policy and investment to get homes built. All of those are important. But there is another issue we don’t talk about nearly enough: how we create the next generation of SME property developers. The reality is that first-time developers remain one of the most underserved groups within specialist property finance. While there are lenders prepared to support them, the market understandably places far greater emphasis on borrowers with established track records. That is commercially understandable. Development finance is complex, every project carries risk and lenders have a responsibility to ensure schemes are viable and borrowers are properly prepared. The consequence, however, is that many aspiring developers
Bridging & Commercial
find themselves with the ambition to build but without the confidence, knowledge or funding partner to enable them to take that first step. If relatively few lenders are prepared to support first-time developers, where will tomorrow’s experienced developers come from? And, if we don’t create more experienced developers, how do we realistically expect to increase the delivery of new homes? Common first-time concerns During my career, I’ve reviewed development finance applications ranging from first-time developers to experienced housebuilders, and I’ve had hundreds of conversations with borrowers embarking on their first project. The conversations are remarkably consistent. “I’ve never developed before.” “I’m an experienced landlord, but this is my first build.” “I’m worried I won’t know what lenders are looking for.”
26
Sam Herd
NEWS
In my experience, the challenge usually isn’t ambition. It isn’t capability either. More often than not, it’s confidence. Many first-time developers simply don’t know what constitutes a strong development proposal, what information lenders expect to see or what happens after funding is approved. They’re often worried about asking the wrong questions or making avoidable mistakes that could delay or even jeopardise their project. I don’t believe that should mean first-time developers are left to navigate their first project alone. I believe it means they need greater preparation, better guidance and the right funding partner when they’re ready to take that first step. That belief has been reinforced by conversations with borrowers and our own portfolio management team, who continue supporting projects long after completion.
Through practical learning resources, expert guidance, real project case studies and live online sessions, we’ll explore every stage of the development journey, from preparing a strong funding application and understanding what lenders are looking for, through to managing a project and navigating the challenges that come with it. We’ll also share the lessons we’ve learnt from supporting development projects every day, helping aspiring developers build the confidence, knowledge and preparation needed before they submit their very first application. Funding first-time developers is only part of the answer. Helping them succeed is the other. By combining funding with education, practical insight and ongoing support, we’re giving aspiring developers not only the opportunity to take on their first project but also the confidence and knowledge to do it successfully.
“Funding firsttime developers is only part of the answer. Helping them succeed is the other” Together, we’ve seen where first-time developers thrive, where they struggle and, perhaps most importantly, where a little guidance early in the process could make a significant difference later.
For me, specialist lenders have an opportunity—and perhaps even a responsibility—not only to fund the next generation of developers but also to help create them. Because better-informed developers make better-informed decisions. That gives lenders greater confidence, helps projects progress more smoothly and, ultimately, contributes to delivering more high-quality homes. If our industry wants more experienced developers tomorrow, we need to invest in first-time SMEs today. That means giving more first-time developers both the opportunity to take that first step and the confidence to succeed when they do. That’s exactly why we created Mint First Time Developers Academy.
Realities learnt before starting The question we kept asking ourselves was simple: what if we could help aspiring developers before they submitted their very first application? Those conversations became the catalyst for creating Mint First Time Developers Academy. Our aim wasn’t to create another marketing campaign. It was to build something genuinely useful. An educational platform designed specifically for first-time developers, helping them understand the realities of development finance before they embark on their first project.
Bridging & Commercial
28
The bank that finds a way to support you Full-service banking, with all the business finance your clients need. Find out more at allica.bank/introducers
Allica Bank Limited is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (FRN: 821851). Registered office: 4th/5th Floor, 15 Worship Street, London, EC2A 2DT. Registered in England and Wales with company number 07706156. Copyright © 2026 Allica Bank Limited. All applications are subject to status and lending criteria. Eligibility criteria and terms and conditions apply. Visit www.allica.bank.
Consolidate mortgages through portfolio lending
Optimise your clients’ property portfolios. For refinancing or purchasing solutions, talk to us.
Call us on 03330 608 770
For intermediaries only
Let’s build this
Helping investors is our language Buy
買
Comprar
• Foreign nationals & companies accepted • No UK footprint required • 3 year bridge to let ▪ Bridging Rates from 0.74%pm ▪ BTL rate from 6.89%pa
aspen
bridging
Email: sales@aspenbridging.co.uk Tel: 0845 318 0001
Paul Weitzkorn
Funding 365 recently agreed to become part of a global investment firm and, at the same time, signed a £300m funding line. How will these change the company and what it offers?
Words by
PAUL WEITZKORN
Director at Funding 365
Photography by
CONNIE BURKE
EXCLUSIVE
unding 365 was not looking to be sources of capital. As an indeinception had provide the levels of
acquired; we were exploring additional
pendent lender with principal-led funding, all capital since been provided by our directors. We had reached a stage where, to levels of funding our clients were looking for, we needed greater subordinated debt than our own principal alone could deliver.
It was during conversations with capital providers and our advisors that this opportunity emerged. We quickly realised that being part of Balbec Capital was a very compelling proposition. As a global alternative investment manager specialising in mortgage-based credit and real estate strategies, and looking to re-enter the UK bridging market, Balbec was strongly aligned with our long-term ambitions.
Retaining five star service From our clients’ perspective, this acquisition is a positive move. Service has always been at the heart of our operation, and we are proud of the fact that 100% of our Google and Trustpilot reviews from brokers and borrowers are five stars. We are committed to ensuring that, throughout our planned growth, our clients’ experiences will remain top level.
Bridging & Commercial
34
EXCLUSIVE
FUNDING 365 WAS NOT LOOKING TO BE ACQUIRED; WE WERE EXPLORING ADDITIONAL SOURCES OF CAPITAL
Managing director Mike Strange, marketing director Laura Kendall and I are still running things day to day, supported by our team of underwriters and relationship managers. As before, you can phone our office and expect to have your call answered within three rings. Our underwriters still aim to provide you with bespoke, credit-backed terms in one hour. Your loans will continue to be delivered seamlessly by the underwriter who issued your terms, from enquiry to redemption. Balbec recognises the benefits of the way that we work and has no intention of changing this. We remain in our own office, with the added advantage of having access to Balbec’s infrastructure. Its tech team is already working to make us more efficient, streamlining our internal processes so that we can keep our focus on where it matters most: delivering for our clients.
A much bigger pot Under Balbec’s ownership, Funding 365 can do a lot more. In the past, we tended to be quite conservative as our principal funding was the first loss position in every deal. We became a go-to lender for very competitively priced solutions in the lower-risk end of the market. Now, we can look at raising our LTVs, expanding our types of accepted securities and increasing our loan sizes. By pure coincidence, on the very same day that we finalised our acquisition by Balbec, we signed a £300m funding line from a global investment bank. My background is in investment banking, structuring mortgage securitisations for banks in the UK including Santander, Lloyds and Paragon. My fellow Funding 365 directors have similar backgrounds, with mortgages and other asset classes including bridging - being part of their expertise. Being able to speak the same language as the people we’re dealing with at banks, many of whom are former clients or colleagues, has given us an advantage in negotiating and executing institutional funding lines.
More on offer Our new funding line will enable us to sharpen interest rates across our product suite and increase our book size. We already offer a wide range of unregulated, first-charge bridging, refurbishment, development and specialist buy to let products. In the past few years, however, most of our completions have
35
July/Aug 2026
“WE HAVE A CLEAR BUSINESS PLAN FOR THE NEXT THREE YEARS TO BECOME A GOTO FOR LENDING FOR OTHER PRODUCTS”
EXCLUSIVE
been concentrated in the residential bridging and light refurbishment spaces. We have a clear business plan for the next three years to become a go-to for lending for other products. Our first move, announced at the beginning of July, was to offer rolled interest with our light and heavy refurbishment products, allowing us to deliver larger up-front amounts, with up to 75% LTV net on day one. Following market research, we are planning enhancements to our Northern Irish offerings, commercial bridge, development and specialist BTL products. With Balbec’s support, the deep pockets of multiple investment bank funding lines and enhanced products across the board, the future feels bright for Funding 365. After a challenging start to 2026 for the short-term lending market, with lenders hitting the headlines for all the wrong reasons, it is great to be able to bring some positive news to the industry. Borrower demand is strong and we are seeing a greater urgency for funds. We are delighted to be in a position to support this growth.
Bridging & Commercial
38
We are a principal development and bridging lender with a forward-thinking approach.
Refurbishment
Part Complete Development
Development
Bridging
Funding for light, medium or heavy refurbs Grade listed and student accommodation considered No exit fee regardless of the build cost
Flexible on experience Solution driven equity structures Flexible on PGs
ADAM BUTLER
GEORGE ORMEROD
07388 919 116
go@avamorecapital.com 07824 333 747
Director of Sales & Marketing ab@avamorecapital.com
Relationship Manager
Ability to step in at any stage of the build Experienced team with strong track record in funding PCDs Pre-agreed equity release available
Acquisitions and development exits Net Sales proceeds available Lend against OMV not 180 day value
AIDAN LESSLIE Relationship Manager al@avamorecapital.com 07491 972 329
SAMANTHA GRAYDON Relationship Manager sg@avamorecapital.com 07523 367 903
TOM MORRISSEY
Relationship Manager tm@avamorecapital.com 07376 335 515
020 3440 9651 | www.avamorecapital.com | enquiries@avamorecapital.com
Funding the built environment Providing swift development finance solutions on heavy-refurb or ground-up projects, we know not every developer’s journey starts or ends the same. We design our finance around your timelines, so you can focus on delivering quality residential-led projects time and time again.
West One is a trading name of the underlying firms, who are registered in England and Wales and have their registered office address at The Edward Hyde Building, 38 Clarendon Road, Watford, WD17 1JW: West One Loan Ltd is authorised and regulated by the Financial Conduct Authority (firm reference number 510024), its registration number is 05385677. West One Development Finance Ltd. is not authorised by the Financial Conduct Authority; its company registration number is 11242570. West One Commercial Mortgages Ltd is not authorised by FCA its registration number is 16476112. Certain types of loans are not regulated, for example loans for business purposes or certain buy-to-lets.
Development Finance
www.westoneloans.co.uk Developmentfinance@westoneloans.co.uk 0333 123 4556
The lure of the unconventional asset From seaside piers, lorry parks, farmhouse wellness retreats and vineyards to hotel conversions, casinos, and distressed developments, lenders are finding unusual and often disparaged assets—and locations—increasingly attractive
Words by
DHUHA AL-ZAIDI
Illustrations by
BEPRO
COVER STORY
T
here’s a moment in every market cycle when the obvious deals dry up and the interesting ones start. We’re in it now. Speak to enough lenders, brokers and surveyors, and a picture starts to emerge of an industry that has quietly stopped waiting for the BTL purchase or the refurb and gone looking instead for the deal nobody else wants to touch. “The biggest change for me has been the move away from cookiecutter lending,” says Adam Butler, sales and marketing director at Avamore Capital. This refers to a standardised loan approval process that relies on automated criteria, instead of individual borrower evaluation. “Borrowers today are looking at more complex opportunities; that’s where the value is,” he adds. It seems it isn’t just Avamore. Across the market, this observation is repeated: equity is scarce, groundup development has become harder to sell, and sales cycles have stretched out just enough to push both borrowers and lenders towards assets they would have
politely declined some years ago. Jonathan Samuels, CEO and founder of Octane Capital, frames it as a complete break from an old assumption. “The days of buying an asset and holding it for capital appreciation are pretty much over—the economics for that don’t work any more,” he says. “Property professionals need to add value. That’s the first thing.” His comments are echoed by Edward Matthews, CEO at MERA: “The low-hanging fruit just isn’t there. Investors and borrowers are heading more towards the more complex situations because they seem to be the only opportunities in the market that are viable.” This has taken the industry into unexpected areas; data centres and care homes, wellness retreats built on old farmland, lorry parks and backpacker hostels, seaside towns
Bridging & Commercial
46
nobody was writing about 18 months ago—and away from a central London market some now describe as distressed. However, it has also taken developers somewhere less comfortable: into part-built schemes, receiverships and a lending market some think is repeating mistakes it made in the 2008 financial crisis. This is the UK’s unexpected opportunity map—the assets, the regions, the borrower behaviour and the distress that specialist finance is quietly building itself around, which the mainstream would rather avoid.
“HMOs used to be niche as well as multiunit freehold blocks, but they’re probably more common these days.” Though he’s q u i c k to add t hey still require investor e x p e r i e n c e g i ve n the complexities involved. Alongside Niche to novel t h e m, O c t a n e h a s Ask any lender what’s crossing developed an appetite their desk these days and the list for ex-local authority barely resembles the one from a h o m e s a n d b a r n few years ago. HMOs and multi- conversions—assets unit freehold buildings, once he was cautious about genuinely niche, have become only a couple of years almost mainstream. back. “We’ve had more This is reiterated by Samuels: experience with it, and they’ve performed well,” he says of barn conversions specifically, pointing to the capital appreciation
COVER STORY
available once planning consent is granted. Then there’s the genuinely novel. Jessica Reehal, specialist broker at London Mortgage Solutions, is placing deals on wellness retreats built out of former working farms. “The asset types I’m seeing at the moment are completely different to before; I’m seeing more wellness retreats and non-working farms from farmhouse conversions. So, they’ve got the residential aspect, and then they’ve got the land—the two acres— and they’re going to put pods on it and turn it into a wellness retreat,” she explains. She notes that it’s not a passing fad, either: “Wellness as an industry has gone up by 300% in the past year or two—it’s definitely here to stay.” She is just as enthusiastic about a run of auction HMOs on her desk, including a seven-bed conversion where the lender is funding both the purchase and the works. And, when a lender balks at something unfamiliar, her answer is always the same: “You don’t start from the bridge; you start from the exit.” Operational assets are proving just as compelling. MERA is financing what Edward says is Europe’s largest lorry park alongside a backpacker hostel and is in advanced discussions with a children’s nursery platform looking
“INVESTORS AND BORROWERS ARE HEADING MORE TOWARDS THE MORE COMPLEX SITUATIONS BECAUSE THEY SEEM TO BE THE ONLY OPPORTUNITIES IN THE MARKET THAT ARE VIABLE”
to scale. “We see more and more funding requests for operational businesses rather than just straight acquisitions, purchases or refurbishments,” he says. The logic is simple: with equity so scarce, borrowers who can prove a platform can scale and have an equity backer behind them are one of the few growth stories left standing. “We think operational assets are a big growth area, certainly for the next 24–36 months,” Edward adds. Care is another asset class that keeps coming up, and not just from lenders. “The care sector seems to be very hot at the moment, and it’s an area we’re getting more and more valuation questions on,” says Colin Hor ton, co-founder of valuation company Project & Co. He points to the income security that comes with C2-use leases and housing provider contracts. Akhil Mair, managing director at
47
Our Mortgage Broker, goes further, arguing care and assisted living should already be commonplace. “It’s got to be around here—short-term care or long-term care. That needs to go more mainstream, with more lenders having an appetite to lend in that space,” he says. He adds that purposebuilt student accommodation (PBSA) is another space his landlord clients are increasingly gravitating towards. Akhil doesn’t hide his frustration with how far the market still has to travel on some of this. “We live in a world now where nothing’s straightforward, nothing’s vanilla,” he points out. Nobody, though, has a more compelling story than Jamil Akhundov, managing partner at Ploutos Associates and Ploutos Capital, about what h a pp e n s w h e n s o m e o n e spots a gap nobody else has
noticed. He describes three entrepreneurs— a n I T s p e c i a l i s t, a n investment banker and a construction expert—who bought a dilapidated 48room aparthotel on the Cornish seafront during the Covid-19 pandemic for less than the value of the walls. They gutted it, turned it into 28 selfcatering apartments with no reception desk and no food-and-beverage offering, arranged deals with 15 nearby restaurants, bars and gyms, and fitted it out with NFC key entry and a hologram greeter. “The creativity was in recognising that people are increasingly choosing self-catering,” Jamil says. For example, he says that these
July/Aug 2026
“Borrowers increasingly need funding that’s tailored to their project rather than forcing the project to fit the loan”
COVER STORY
vineyard and winery and describes how old B&Bs and guesthouses in seaside towns are being turned into multi-unit blocks and days a family with children will opt serviced accommodation. for an apartment with self-catering Promising regions for him for the holidays instead of booking include Blackpool and two hotel rooms. “Aparthotels are the East Anglia, Kent and nothing new; they’re mainstream. South West coasts. Going above and beyond the basic offer and lowering staffing costs is Bespoke borrowing a “winning formula,” he asserts. He also adds that the same client has As the assets have changed, since bought a church and turned so has the way borrowers it into a food market and is now are structuring around working on transforming a seaside them. Butler describes a entertainment pier. genuine shift in strategy On the other hand, data centres are at Avamore, away from the asset Jamil thinks the market borrowers simply paying still hasn’t caught up on. “You need full price upfront and at least 50 times more data centres towards vendor finance, across the world than are being built deferred payments and right now,” he states. “Data centres joint venture structures will be like what Google search was with landowners or highin the 1990s: first a niche thing, and net-worth individuals. now everybody and their dog use “You’ve got a vendor who’s it.” Neal Telford, director at Capital got land, and they have a B Property Finance, is placing deals price in their head of what just as unconventional, memorably that’s worth versus what the amphibious house from Grand that price needs to be to Designs, which floats out of the make the scheme viable for ground when the Thames floods. the person who’s going to “Despite it being an amphibious house, being in a flood-risk zone coupled with the obvious nonstandard construction was a struggle for a lot of lenders,” he admits. Neal is also mid-transaction on a
Not everyone is convinced these discounts are quite as they appear, though. Adam Brews, head of capital advisory buy it and develop it,” he explains. at Vandermolen Real For Butler, that’s the real story—not Estate—an agency and the asset class, but the strategy advisory f irm that wrapped around it. “Borrowers spends much of its time increasingly need funding that’s untangling distressed tailored to their project rather than schemes for receivers forcing the project to fit the loan,” and administrators— he notes. “Every single scheme s e e s a m i s m a t c h we look at is a bespoke product.” running right through Jamil sees a similar shift, one driven this corner of the by distress. Borrowers, he says, are market. “The reality is becoming “way more picky” about that, very often, these the projects they take on, moving below-market-value away from ground-up development transactions simply and towards refurbishments, aren’t below market conversions and below-market- value, it’s just the new value acquisitions. He points to value of the property a deal completing on two-bed, in the current market,” new-build flats in Harrow on the he explains. “There’s Hill, bought for £230,000 against a a h u g e m i s m a t c h valuation of £300,000–£350,000. “Why would anybody sell at a 30% discount? Distressed sellers are desperate and trying to get rid of the opportunity at any price, it seems,” he says.
The reality is that, very often, these below-market-value transactions simply aren’t below market value; it’s just the new value of the property in the current market” 49
July/Aug 2026
COVER STORY
between borrowers thinking they’ve found a fantastic deal at 30% below market value and lenders looking at the deal and saying, that’s not 30% below market value, that’s just the market value now.” In other words, what looks like a bargain from one side of the desk can look like a market correction from the other. Jessica describes borrowers getting creative not just in what they buy but also in how they buy it—lease agreements, delayed completions and landlords increasingly working through networks to find approaches others haven’t. Akhil sees the same shift from a different direction: with vanilla BTL squeezed by regulation, legislation and taxation, borrowers are having to “become bold and fancy” in their strategies just to protect their margins. What he’d like to see in return is a lender willing to look past the property and back the person. “Understand the bigger, wider picture of the borrower—their experience, their portfolio, their overall LTV across the portfolio,” he says. “Working with the client like that, I think they’d appreciate it much more.” And then there’s a gap that appears to be difficult to close: equity. Edward is unequivocal about where the real
shortage lies. “Equity is the biggest thing in demand right now,” he says. “There’s a surplus of senior lending at the moment. There’s an undersupply of equity.” MERA, which offers preferred equity funding, is receiving 5–10 enquiries a week for equity funding alone, a surge he puts down to good operators sitting on schemes that are sound in principle but starved of cash by a slower sales market that isn’t of their own making. Regional hotspots and city quitters
For decades, the geography of specialist finance was simple; London first, the rest of the country a distant second. That map is being redrawn, and almost everyone I spoke to is watching similar areas gain traction while London seemingly slips.
Bridging & Commercial
50
For Jamil, it’s “definitely the LeedsBradford area” where a lot of deals are being placed. “Manchester, which is usually very hot, is quieter these days. We’re seeing bits and pieces coming from Scotland,” he observes. The scale of the shift, he notes, is stark. “In the past, we used to have half of our deals in London and half in the rest of the country. Nowadays, it’s hardly 10% in London,” he recalls. He puts it down to a combination of factors: HS2 and infrastructure issues from London, the trend of working from home and, simply, affordability. “A lot of people don’t need to show up in the office every day, so why not buy something bigger and nicer in Leeds, instead of somewhere smaller around London?” he questions. Then there’s the exodus from the top of the market. “You’ve got quite a bit of price adjustment in central London— foreigners, who used to make up 50–60% of buyers in central London, are leaving the market and selling
up,” Jamil highlights. “You’ve got price adjustments of up to 30%, and the London market is becoming a little distressed.” Not every regional story is quite as clear as it looks from London, e i t h e r. J o n a t h a n Vandermolen, CEO a t Va n d e r m o l e n Real Estate, points to two of the cities most often held up as the answer to an overpriced capital, and sees a market that’s overcorrected in its own way. “There’s been an awful lot of new development in two places—Manchester and Birmingham—largely because help to buy overpriced London for a lot of people, particularly investors,” he says. Vandermolen is working on a 1,500-unit site in Salford and reckons both cities have something like 20,000 homes either under construction or
“A lot of southerners now are understanding the demand and the opportunities that are up North and quite rightly so”
COVER STORY
“Truthfully, of the £250m of sales we did last financial year, just under 50% were on behalf of receivers and administrators— that’s the amount of distress we’re seeing in the market”
stuck in limbo because the sums no longer work at today’s build costs. Student accommodation is faring little better, he adds, noting that, outside London, “there are now more student beds than there are students”, with developers and investors increasingly steering PBSA schemes towards general build-torent stock instead. Colin, who values property across the country, agrees prime central London is falling behind. “I still think prime central London is struggling to keep up at the moment, unfortunately,” he says, pointing squarely at stamp duty. “That tax is horrifically restrictive and, as soon as you start moving above that millionpound threshold, it becomes quite obstructive to people trying to move into those homes,” he stresses. Not to mention that “a million pounds doesn’t get you very much in zone one and zone two these days”. Political uncertainty isn’t helping either, not least the rumours of a land tax. “People are looking to put their money outside residential
and probably more into commercial, where it’s a little bit safer,” he says. Areas away from prime central London, however, offer something more promising; Colin says the £1.5m–3m bracket and the Home Counties, Kent and Hertfordshire are consistently strong. Not everyone has written London off. Akhil, running a London-based brokerage, still sees strong volume in the capital on the back of higher capital values and resilient rental demand but concedes the real spike is happening elsewhere— in the commuter belt and in cities with large student populations such as Liverpool, Manchester, Bristol and Bath. “There’s always going to be a sort of North-South divide in England,” he says. “But a lot of southerners now are understanding the demand and the opportunities that are up North and quite rightly so.” Edward echoes the regional strength
Bridging & Commercial
52
without pinning it to one city in particular. According to him, Bristol, Manchester, Liverpool, Leeds and Glasgow are all performing without one being the obvious choice. “I genuinely think it’s a once-in-ageneration opportunity to buy,” he says of the regions more broadly, while flagging one thesis MERA is backing: infrastructure as the true driver of growth. “Transport is our big defining factor for growth,” he says, also suggesting that tourism will migrate north as the climate warms, which has already led the lender to finance a major tourism project in Scotland. Neal’s seaside towns tell a parallel story to the northern cities—Blackpool, East Anglia, Kent and the South West all seeing old infrastructure repurposed into serviced accommodation and multi-unit freehold blocks. Samuels, meanwhile, resists naming a single hotspot, pointing instead to the steady rise of barn conversions, now so common that Octane actively lends on them, provided they’re not “seriously deep rural”, an indication
that oppor tunity is following the asset. Distress behind the discounts
For every opportunity dressed up as a bargain, something behind it has gone wrong—and few see more of this t h a n Va nde r mole n Real Estate. The firm splits its time between agency and capital advisory, but a growing share of both sides of the business now runs through receivers and administrators rather than sellers. “Truthfully, of the £250m of sales we did last financial year, just under 50% were on behalf of receivers and administrators—that’s the amount of distress we’re seeing in the market,” notes Brews. “We’re looking at truly a job a day on behalf of lenders.” It’s a role Vandermolen has made
COVER STORY
“Always communicate with your lender— don’t bury your head in the sand”
peace with, even leant into. “Johnny likes to refer to himself as the Grim Reaper, because he’ll just tell you exactly what we think and what the reality of the market is,” Brews jokes. Much of that distress starts with part-built schemes—developments where the original developer or contractor has gone under, leaving a lender-appointed administrator to try to recover the funds. “No new lender wants to pick up where an old lender failed and try to save the day,” Brews says. “So part-built schemes are a massive issue when it comes to sourcing funding—and also on the agency side, selling them.” Vandermolen sees the same story from a different angle, describing a lending market that has changed shape entirely since the last crash. “In 2008, you mainly had the Scottish banks, RBS and Bank of Scotland, NatWest, Barclays, Lloyds and some specialist lenders like Dunbar and Investec,” he says. “Now, there are probably 500 lenders with a team of five or more, a lot of whom have
their equity supplied either by family of f ices, HNW individuals or credit lines”—a structure that, as the collapse of lender MFS demonstrated, can unwind fast when one of those credit lines gets shaky. The knock-on effects are showing up everywhere. Valuers are being threatened with legal action over historical numbers, Vandermolen says, in a market with too few comparable sales to lean on—Molior data shows just 2,800 homes were sold across the whole of London in the second quarter of last year, and only 589 of those went to individual UK buyers. And, when a scheme does end up in receivership, Vandermolen says the pattern is depressingly consistent. “Pretty much everybody outside of the first charge is wiped out—anybody with mezzanine equity has lost their money, and often the developer has been slow to tell those people they’ve got problems,” he says. His advice to borrowers is simple: “Always communicate with your lender—don’t bury
53
your head in the sand.” Even schemes with planning permission aren’t safe. Tall buildings over 18 metres now need to clear gateway two—the Building Safety Regulator’s approval stage for highrisk buildings, introduced under the building control regulations— before any development lender will touch them, Brews explains, and the lenders who have tried funding during that stage “have been in there for a year and a half with no clarity on when it’s going to end”. The result, Brews says, is that land with consent for hundreds of homes can be worth less on paper than the greenfield or industrial site sitting underneath it.
client wanted to buy that only a couple of lenders would consider, despite her pointing out that it was already producing cashflow and profit. “If some of these lenders opened their doors, like with this Gloucester project I’m currently doing, which has shops downstairs and offices above, and it’s already cash-f lowing, it’s an existing asset; why would they not lend on it?” she Problem reputation questions. She believes After asking the brokers where the problem is partly that lenders are holding on to their lenders’ loan books are money, the answers come fast. For heavy on commercial, Jessica, it’s commercial, full stop. and residential is seen as She recalls a parade of shops a safer. “With Rightmove, residential is all over it, but commercial is still very hidden; to get a good deal it’s who you know—like the right commercial agents,” she suggests. Neal agrees, singling out properties lenders write off on reputation alone. “The quirky
July/Aug 2026
If firms don’t adapt to things like AI, I think they’re going to fall
behind—and that’s not just valuation firms but lenders too
“There’s still very limited appetite across the market for land bridging, especially the leverage that most clients require at the moment”
COVER STORY
commercial assets and places of worship are always the hard ones,” he says, arguing that lenders should adopt a more case-specific approach than the blanket policies most apply. Akhil goes further, naming pubs, casinos, nightclubs, gambling premises and private schools as sectors lenders are simply avoiding. “I think they’re actually missing a trick, to be honest,” he says. “I have never seen a casino closing down, but you’ll see WHSmith closed down, you’ll see all the local retail stores closing down and even banks.” Education, he argues, is an even clearer missed target, given the length and security of government and local-authority-backed leases behind special educational needs schools. Ja m i l’s a n s we r s i t s c l o s e r t o infrastructure than bricks and mortar—data centres, power supply and digital infrastructure more broadly, all of which he believes are chronically under-built relative to demand. And Butler points to land bridging as the gap the market seems unwilling to close. “There’s still very limited appetite across the market for land bridging, especially the leverage that most clients require at the moment,” he says, describing it as lending “very much on hope value” until planning comes through.
Jamil describes traditional high street retail—smaller thoroughfares in particular, the Guildford High Street as opposed to the Oxford Street kind—as one of the hardest asset classes to fund right now, squeezed by falling rents and shrinking tenant demand. “As a lender, you wouldn’t lend against something that’s dropped in tenant value this much,” he says. Colin, looking at it from the valuer’s chair, makes the case for why cash flow is what should really be driving these decisions. What’s brewing?
So, what happens next? MERA is rolling out an equity product in the second half of the year, aimed squarely at the strategic land opportunities Edward was cautious on only two years ago but now believes have settled at “a sensible and viable level”. Octane is preparing a BTL product designed for lower-yielding assets in London and the South East that mainstream lenders won’t leverage. Neal is closing a vineyard and winery deal and has just completed a 40-property auction
57
portfolio valued entirely via an AVM in 15 working days—a sign, perhaps, of how far speed and technology are being pushed in tandem. “Every deal is different,” he says. “You never know what you’re going to pick up the phone to next.” Jamil’s client, fresh from turning a church into a food market, is now working on an entertainment pier in a seaside town most people have written off. Jessica is tweaking funding on an 18-bed Scottish property, still convinced there’s “certainly no shortage of lenders out there”, and Akhil is watching his landlord clients move out of single-family lets and into multi-unit conversions, PBSA and care. Colin, for his part, thinks the next conversation the industry has with itself won’t be about assets at all. “The regulation of the bridging market—I think it’ll become more and more regulated, with fundingline governance coming in,” he says. “It’s already becoming more like term lending and the good operators will continue to thrive.” His warning is aimed at anyone tempted to sit still: “If firms don’t adapt to things like
AI, I think they’re going to fall behind— and that’s not just valuation firms but lenders too.” If there’s a single thread running through all of it, it’s this: the deals worth chasing are no longer the ones sitting in plain sight. They’re in a lorry park, a former church, a farmhouse with planning for pods or a warehouse three lenders turned down. The map has been redrawn. The only question left is: will these become more mainstream, as bridging has?
July/Aug 2026
What a night. The industry at its best! TAB
B&C know how to rock the joint! Together
Medianett breaking new ground, again! Black & White
The ultimate recognition for achievement in specialist finance Colenko
The Oscars of the lending world Spector Constant & Williams
The night B&C went blockbuster Allica Bank
Join the reserve list for a table in 2027 Contact beth@medianett.co.uk and ellen@medianett.co.uk
Is my client’s property really unmortgageable?
Subsidence? HMO? Low EPC? Talk to us. Real solutions to real client problems.
Call us on 03330 608 770
For intermediaries only
Let’s build this
Let’s pick this up in September
today For loans that can’t wait
#LoansCantWait
COMMERCIAL MT Finance started offering commercial mortgages a year ago. How are they getting on? We ask Nick Grant, head of commercial underwriting
MORTGAGE MOVE: ONE YEAR ON
Interview by
DHUHA AL-ZAIDI
Photoraphy by
CONNIE BURKE
Nick Grant
INTERVIEW
part of the market finally getting the support it needs thanks to our specialised risk appetite and product proposition has been a major highlight of the year. What have been the most challenging but equally rewarding aspects? The commercial market is a competitive space, and we were effectively an unknown entity in this space when we started. The primary issue was the sheer amount of groundwork required—we had to be out there, constantly pushing and educating the market on who we are and, more importantly, how we work. The biggest hurdle was shifting broker mindset: moving them from thinking of us only for short-term finance to viewing us as their first port of call for commercial mortgages. Convincing them to trust us with their clients’ longer-term requirements was a significant task. However, the reward is seeing those same brokers return to us time and again. When they come back, you know you’ve hit the mark.
It’s been a year since MT Finance launched its commercial mortgage business with a £2.5bn JP Morgan facility. How would you sum up the first 12 months?
What types of commercial properties have made up the bulk of your lending so far? Has anything surprised you about demand?
The past year has been incredibly exciting and rewarding. Launching a proposition is always a significant undertaking, but there has been a genuine buzz surrounding this product line from day one. Personally, it has been a fantastic opportunity to translate my own professional work ethic and experience into the MT Finance framework. The business has a can-do culture, one that prioritises pragmatic, commonsense lending solutions that borrowers are looking for, and it has been incredibly fulfilling to marry that approach with the specific needs of the commercial sector.
Semi-commercial properties have always been a staple of our wider mortgage range, and loans on these continue to be one of our most popular products. With regards to purely commercial premises, we’ve seen a broad mix of standard and specialist assets. There are significant opportunities for investors to acquire commercial properties right now, largely due to the high yields available compared to other asset classes. We’re seeing a diverse mix of activity from FTLs looking to acquire high-yielding assets to improve their returns, businesses looking to acquire the buildings they trade from to secure their long-term operational footprint and portfolio landlords looking to diversify their portfolios. As for surprises, honestly, there hasn’t been anything unexpected so far—the market is performing exactly as I anticipated 12 months ago. Demand remains robust and the activity we are seeing is consistent with our original projections.
At the time, you spoke about addressing an underserved part of the market. Has that opportunity proven to be as significant as you anticipated? Absolutely. From a trading perspective, performance has aligned perfectly with our initial expectations. We identified that first-time landlords (FTLs) and first-time buyers often being overlooked by high-street lenders, whose rigid criteria can be a barrier to entry, particularly around asset type or borrowing experience. By offering flexible products designed specifically for these segments, we have seen a strong pipeline of applications from borrowers who would typically struggle to secure mainstream funding. It has been a validation of our strategy; seeing this previously underserved
Bridging & Commercial
Has your approach to underwriting or lending evolved since the move? If so, what are you doing differently today? Our core underwriting philosophy remains firmly rooted in the MT Finance DNA; we prioritise commonsense, flexible and concise
64
THE REWARD IS SEEING THOSE SAME BROKERS RETURN TO US TIME AND AGAIN. WHEN THEY COME BACK, YOU KNOW YOU’VE HIT THE MARK”
“OUR PRIORITY IS TO LAUNCH NEW PRODUCT LINES IN THE COMING MONTHS, DIRECTLY IN RESPONSE TO MARKET NEEDS AND THE VALUABLE FEEDBACK WE’VE RECEIVED FROM OUR BROKER PARTNERS”
INTERVIEW
solutions. That said, we have adapted our products in response to the evolving needs to ensure we stay true to our original mission. Twelve months ago, I emphasised that as underwriters, it is vital to build strong, collaborative relationships with brokers, and that is exactly what my team has translated into our day-to-day operations. We aren’t just looking at data; we are building partnerships to ensure we can move cases forward effectively.
The commercial property market has continued to evolve over the past year. How have changing economic conditions influenced borrower behaviour? The challenging economic conditions have naturally influenced borrower behaviour. While there was a lot of initial activity, there now seems to be a bit of a waiting game across the board. However, we have seen a significant number of first-time buyers and FTLs seizing the opportunity to acquire properties that aren’t moving elsewhere, filling the void left by some of the remortgage business that has dropped off due to the shifting economic landscape.
What feedback have you received from brokers, and how has it shaped your proposition? The consistent themes in the feedback we’ve received are the speed at which we can service our customers and our ability to craft personalised solutions that move cases from enquiry to completion. It is a genuine pleasure to see our underwriting team building such strong relationships with the intermediary community. We are proactive listeners, and we take that feedback on board to ensure we are constantly refining how we operate.
Looking ahead to year two, what are your priorities for the commercial mortgage business? Our priority is to launch new product lines in the coming months, directly in response to market needs and the valuable feedback we’ve received from our broker partners. We are also looking closely at our existing product lines to see how we can enhance them, ensuring they remain competitive and fit for purpose.
Where do you see the biggest opportunities and challenges for commercial lending over the next 12 months? I don’t think the market is going to change drastically over the next 12 months—the biggest problem remains the broader economic climate. Nonetheless, we have a robust product range, a strong team and a deep-seated belief in the difference we make. Our focus is to keep doing what we’re doing as efficiently and effectively as we possibly can to provide the right, tailored solutions. The economic climate may be out of our control, but being the best at what we do and executing that with excellence is something we can control.
67
July/Aug 2026
Life is full of surprises, but your lender shouldn’t be. Brokers tell us they want a lender who means what they say on day one – and that’s exactly how we operate. We provide more than just “indicative terms.” Our credit team can also assess your case before terms are issued, meaning when you hand those terms to your client, you can do it with total conviction. Send us your next case and give your clients a lender that means what they say, from day one to drawdown.
Development Finance Features: Reg & non-reg loans
QUICK ENQUIRY
No exit fees Credit-backed terms Interest charged on funds drawn Flexibility on LTC ratios Direct access to underwriters
FOR INTERMEDIARIES ONLY
You’ll be surprised what we can fund. More loan products. More deals done.
Speak to an expert about your next bridging case: 0161 312 56 56 | brokers@somo.co.uk
why make finance difficult
On the Rise
In just three years, Sophie Meller has progressed from business development manager at TAB to national account manager for the South and now senior BDM. We caught up with her to discuss the rapid career progression that has shaped her journey, what drew her to a tech-driven specialist lender, and why building strong, trusted relationships with brokers remains at the heart of her role
You’ve progressed from BDM to national account manager for the South and now senior BDM in just three years. What do you think has been the biggest factor in your rapid career progression? The biggest factor has been repeating the right habits consistently. Whether that’s being responsive, following through on commitments or making time to really understand what brokers need, it is consistency that builds trust over time. Strong relationships aren’t built overnight. They’re the result of delivering the same high level of service, every time. I’ve also been fortunate to work for a business that genuinely encourages development and recognises hard work. I’ve been given opportunities to take on new challenges and continue learning, which has played a big part in my progression over the past three years. I’ve also been lucky to have some great role models at TAB whose guidance, experience and support has given me the confidence to keep pushing myself.
Bridging & Commercial
Sophie Meller
What attracted you to working for a tech-savvy lender, and how do you think technology is changing the role of a BDM in today’s lending market?
As the lending market becomes more competitive, what do you think separates a good BDM from a great one? A good BDM understands product. A great BDM understands people. It’s about being accessible, listening to what brokers really need and delivering on your promises. Being proactive, communicating clearly and adding value beyond simply quoting rates helps build long-term relationships. In a competitive market, reliability and consistency often make the biggest difference.
What attracted me most was the focus on innovation. In specialist lending, things are constantly evolving, so working for a forward-thinking business that is always looking at how it can improve was really important to me. Whether it’s investing in our platform, enhancing our website or continuing to innovate our product offering (such as our move into commercial mortgages), TAB is always looking ahead, never standing still. That mindset creates an adaptable business that’s well-positioned for the future. From my perspective, technology has made the BDM role more efficient. With more automation and better systems, I spend less time on admin and more time supporting brokers, discussing complex cases and building relationships. Enhanced data and insights also help me understand my brokers and pipeline better, allowing me to have more informed conversations and provide a more personalised service. Technology doesn’t replace the human element of the role. It gives us more time to focus on it.
70
BTL landscape, including proposed rent reforms and increasing regulatory considerations, which are encouraging landlords to reassess their portfolios and look at more resilient, income-driven assets. As a result, semi-commercial properties are becoming an attractive middle ground. From a lending perspective, this is where a lot of opportunity lies. These transactions may be slightly more complex, but that’s exactly where we can add value, supporting brokers and borrowers in structuring deals that reflect the potential of the asset rather than forcing them into a one-size-fits-all approach.
As you work closely with brokers and borrowers, what emerging trends are you seeing in niche or specialist asset types, and where do you think the biggest opportunities lie?
What advice would you give to someone starting out in a BDM role who wants to progress and build a successful career in financial services?
One of the most noticeable shifts is residential landlords exploring alternative investment strategies. Semi-commercial assets are becoming an increasingly popular stepping stone for investors who may once have focused purely on residential to diversify and improve yields, particularly in a market where returns on standard BTL are under pressure. This shift to mixed-use is being fuelled by ongoing changes in the
Focus on building genuine relationships and never stop learning. Product knowledge is important, but your reputation is built on how you treat people, how reliable you are and whether you can be trusted to deliver. Be curious, ask questions, seek feedback and take every opportunity to develop your skills. Success doesn’t happen overnight, but if you’re consistent and you work hard, opportunities will follow.
Sophie Meller
Uma Rajah
Borrower and broker priorities have significantly changed over the past decade as development finance has been transformed, and reliability and certainty are becoming as important as pricing. Looking ahead, the role of the specialist lender can only grow
Words by
UMA RAJAH CEO and co-founder of CapitalRise Photography by
CONNIE BURKE
EXPERIENCE
R
eaching our 10-year milestone gives us an opportunity to reflect not just on business growth but also on how the development finance market itself has evolved. When we founded CapitalRise in 2016, it was in response to a clear gap. Experienced developers working on prime residential schemes often struggled to access funding suited to complex projects. Too often, lenders relied on standardised credit processes ill suited to the nuances of high-end development, driven by fixed criteria rather than how schemes would actually be delivered. As founders with prime property development backgrounds, we had experienced these issues first-hand. Our approach was to structure finance around each project’s specific characteristics, working closely with borrowers who needed an informed, flexible funding partner. A decade on, those principles remain unchanged. We have now supported over £650m of lending against more than £1.4bn of high-end property. Consistency amid variations The most important lesson from the past decade is the value of deep, specialist knowledge. Prime developments require genuine sector expertise, as no two projects are alike. A refurbishment in Mayfair, a super-prime new build in Surrey and a high-specification scheme in the Cotswolds will reflect different buyer profiles, amenity expectations and purchasing drivers. These projects also differ fundamentally from mainstream residential or commercial real estate in terms of market dynamics, execution and exit risk. Generalist lenders are rarely equipped to assess, structure and monitor this type of work effectively. Understanding these differences requires detailed, scheme-specific analysis and practical experience of how projects evolve. Build programmes can extend, specifications can change and planning delays are common. Rigid underwriting models are rarely suitable for this market. Expertise is built over time. Working closely with seasoned developers across market cycles has allowed us to identify risks earlier and respond more effectively. In recent years—marked by rising construction costs and ongoing planning delays—this experience has been critical to keeping projects on track. Consistency has also been key. Over the past decade, the market has been shaped by political uncertainty, regulatory changes, a global pandemic and rising interest rates and inflation. Maintaining disciplined underwriting throughout has provided certainty for both borrowers and capital providers.
Bridging & Commercial
76
“The most important lesson from the past decade is the value of deep, specialist knowledge”
EXPERIENCE
Shifting priorities Today’s development finance market looks very different from how it did a decade ago. Rising construction costs have impacted viability, particularly for longer-duration schemes. Planning timelines have lengthened, introducing greater project uncertainty; fewer than one in five major planning applications are now determined within the statutory 13-week period. At the same time, regulatory complexity has only increased. These shifts have changed borrower and broker priorities. Certainty of execution is now critical. The ability to rely on a lender to deliver on agreed terms—and respond constructively as projects evolve—is as important as pricing. Our own lending has expanded in line with demand. While prime central London remains a core specialism, we have now supported schemes across the Home Counties, the Cotswolds, Cheshire and the South West—markets that are attracting experienced developers delivering high-quality stock. We have also broadened our activity across the wider living sector. Alongside purely residential schemes, we have funded a 40-key aparthotel in Hammersmith, purpose-built student accommodation in Bath and Bristol and assisted living projects in Cambridgeshire. While asset classes have expanded, we remain focused on strong locations, high product quality and strong borrower track records.
“The market will evolve.
Bridging & Commercial
78
EXPERIENCE
Judicious buyers, individualised deals Over the past decade, high-end schemes have become increasingly ambitious in design, specification and amenities as buyers become ever more discerning. This has driven demand for more tailored funding. Bridging finance enables developers to secure opportunities quickly. Larger refurbishments often require phased drawdowns aligned with build progress. Other schemes, particularly those with operational elements, require more detailed structuring from the outset.
It’ll get more specialist The next decade will bring both familiar and new challenges and opportunities. Demand for high-quality housing in desirable locations remains supported by constrained supply and strong global buyer interest. These fundamentals are evident not only in prime central London but also increasingly across established regional markets.
For brokers, this means working with lenders willing to engage with details. Providing capital is only part of the role; understanding how a scheme progresses and staying involved throughout are increasingly important. At CapitalRise, all applications go through a rigorous 50-point assessment from our highly experienced team. This enables us to support complex schemes, while maintaining consistency in execution.
As projects become more complex, the role of the specialist lender will only grow. With over £500m of capital available to deploy, we are well positioned to support this next phase. As we enter our second decade, our focus is unchanged: supporting experienced borrowers, funding well-considered schemes and maintaining a consistent approach to underwriting. The market will evolve. The fundamentals of good lending will not.
The fundamentals of good lending will not”
79
July/Aug 2026
Visit us on stand C01
COMMERCIAL MORTGAGES ARE HERE! The next chapter begins...
Scan to learn more
FOR INTERMEDIARIES ONLY
Cut the Complex Short-term and flexible financing for your clients property projects. From Refurbishments to Regulated Bridging we have fast and flexible solutions.
Highlights include: • Regulated and unregulated • Dual-representation: one solicitor for both parties saving time and money • Refurbishment Bridging up to 73% net LTV • Covering auctions, house-flips and landlord refurbs • Access to expert support, including Underwriters • AVMs available up to 65% LTV on regulated bridging, and up to 75% LTV on unregulated bridging.
Simple, for everyone. enquiries@lendinvest.com 0203 836 1837
Scan here for more information
EXPLAINED
Success for an expanding bank should not be measured just by loan book size but by whether brokers still trust you and know you’ll pick up the phone
Words by
STEPHEN PALFREEMAN
Head of sales—bridging at Allica Bank
Bridging & Commercial
82
Photography by
CONNIE BURKE
EXPLAINED
Stephen Palfreeman 83
July/Aug 2026
EXPLAINED
When I joined the bridging world in 2013, I don’t think many of us expected just how much it would change over the next decade. The market was smaller, products were simpler, and change happened at a very different pace. Today, bridging is constantly evolving and has become one of the most dynamic areas of lending. Having been on the team at Tuscan Capital before it became part of Allica Bank, I’ve had the opportunity to experience that evolution first-hand. It’s almost two years since the acquisition; we’ve more than doubled our loan book and are on track to originate £250m of new lending this year, with an ambition to reach £500m by 2027. Growth, though, has never been the solitary objective. What I’ve learnt over the past two years is that growth is one thing; doing it without losing the qualities that our brokers and the established businesses they serve value is something else entirely.
“Our focus has been simple: grow the business without losing what made it successful in the first place”
Scaling versus scepticism When a bridging lender becomes part of a bank, there’s naturally a degree of scepticism. I remember having those conversations after the acquisition. Brokers weren’t asking whether we’d change our pricing—they wanted to know whether they’d still be able to pick up the phone to the same people and get decisions at the same pace. That stuck with me because it summed up what matters most in bridging: relationships. Relationships have always been at the heart of bridging and Allica. In my experience, scale and service can absolutely go hand in hand if you make an effort to protect what got you there in the first place. The biggest benefit now isn’t simply having the backing of a bank; it’s what it allows us to do. It gives brokers confidence that we’re backed by stable funding and allows us to support customers beyond the initial bridge. Growing in the right way has also meant strengthening our proposition and investing in experienced people across sales, underwriting and operations, all with accessibility in mind. In bridging, the ability to pick up the phone and talk through a deal will always matter. So, our focus has been simple: grow the business without losing what made it successful in the first place. That said, there is always a place for technology when done right. The launch of our bridging portal has given brokers greater visibility of their cases and reduced unnecessary friction, allowing intermediaries and underwriters to spend more time progressing deals and less time chasing updates.
Bridging & Commercial
One benefit of this is that deals can progress much more quickly; our completion record to date on a deal is five days. What I have always admired about my team is that they view technology as a way to create time for more conversations, not fewer. Every deal has its own story, and it’s often those discussions that make the difference between a success and a loss. Beyond the bridge Securing finance is still the immediate priority for brokers, but the bridge is only one chapter in a much bigger story. Having a bridging facility within a bank allows us to work with brokers throughout their client’s journey, putting longer-term plans in place. It’s one of the reasons we’ve seen such a positive response to bridge-to-term lending, leading us to be named Pioneers of the Year at the 2025 National Association of Commercial Finance Brokers award. It accounts for around 45% of our bridging enquiries, illustrating that brokers increasingly want certainty about what comes next. By using one facility, one legal process and one set of documentation, the experience becomes simpler for both brokers and the established businesses they serve. One recent transaction brought all of this together. We supported the new owners of a hotel with a £3.3m bridge-to-term to stabilise income before triggering onto term.
84
“Every deal has its own story, and it’s often those discussions that make the difference between a success and a loss”
EXPLAINED
On paper, some lenders might have focused on where the business was at that moment, but we were more interested in where it was heading. The facility gave the customer the time to deliver their plan, with a transition onto a commercial loan once agreed milestones had been achieved. To me, that’s when bridging is at its best—not overlooking risk but understanding it. Broker expectations Bridging has changed enormously since I joined the sector over a decade ago, and I don’t think it’s slowing down any time soon. As more lenders continue to invest in bridging, brokers will rightly expect more from the banks they work with. Fast decisions will always matter—but so will human judgement. At Allica, we’re certainly ambitious about where we want to get to over the next few years, but success won’t simply be measured by the size of our loan book. It will be determined by whether we continue to deliver the responsiveness, accessibility and commonsense approach that brokers expect, while using the backing of a bank to keep improving the experience for them and established business owners. The challenge for many lenders now is making sure growth never comes at the expense of the relationships that made intermediaries trust them in the first place. If, five years from now, brokers can still pick up the phone to us exactly as they did before the acquisition, then we’ll know we’ve grown the right way.
Bridging & Commercial
“Securing finance is still the immediate priority for brokers, but the bridge is only one chapter in a much bigger story” 86
“If, five years from now, brokers can still pick up the phone to us exactly as they did before the acquisition, then we’ll know we’ve grown the right way”
EXPLAINED
For all the discussion around changing regulation, tax reforms and economic uncertainty impacting property investment, the UK’s ability to attract overseas investors is remarkably consistent. In fact, over the past 12 months, we’ve seen growing interest from international investors who view current market conditions as an opportunity to acquire high-quality assets, particularly in London and other established urban locations.
provide an efficient way for multiple investors to participate in a transaction. However, they can create challenges for lenders, particularly when it comes to understanding beneficial ownership, completing due diligence and satisfying increasingly stringent compliance requirements. Historically, private banks have been particularly active in this area. Their client base naturally includes many individuals and organisations that invest through international structures, and they have often been well positioned to support complex transactions.
A recent transaction completed by GB Bank is a good example of this. Like many deals in the property industry, it began with a conversation rather than a formal proposal. During discussions at MIPIM, James Thomlinson, co-founder of Voltaire Financial, suggested a transaction he believed would be a good test of GB Bank’s appetite and ability to support a more complicated ownership structure.
Once the deal had been formally introSuch assets include mixed-use freehold duced, it quickly became clear that there blocks, which combine residential and comwere a number of complexities to understand mercial income streams to create a level of and explore. diversification that many investors find attractive. Banks are growing wary of lending on assets with The transaction complicated foreign ownership. That creates considerable required a £10m A building that genopportunities for brokers, especially given the wealth and term debt facility erates income from ambition of the investors involved. How can they access secured against multiple tenants in difa mixed-use freesuch distant, scattered clients? ferent sectors can offer hold block. The p rop e r t y c o m greater resilience than a single-let asset. Resiprised 13 self-conWords by dential demand remains tained apartments strong in many parts above three comof the country, while mercial units, creHead of relationship management at ating exactly the well-positioned comGB Bank sort of diversified mercial units continue to provide reliable inincome-producing come. Consequently, asset attracting mixed-use freehold strong investor deblocks and larger multimand. The newly completed propunit investments are increasingly becoming erty represented a the assets of choice for high-quality investoverseas buyers seeking ment. both income and longterm capital growth. While the asset itself was straightAlongside this trend, forward and highly we’re seeing increasdesirable, the owning complexity in the ership structure ownership structures required more debehind many of these tailed assessment. transactions. In a growThe borrowing ening number of cases, tity was a UK SPV, the borrower itself is but behind it sat a a UK special purpose Hong Kong-based vehicle (SPV), but the ultimate ownership More recently, however, we’ve seen some consortium alongside UK shareholders and sits elsewhere. It’s not unusual to find over- lenders becoming increasingly selective in directors. From a lending perspective, this seas consortiums, trusts or high-net-worth the opportunities they pursue. meant understanding not only the asset and investors behind what initially appears to the borrowing company but also the wider ownbe a straightforward UK property company. Complicated promise ership structure supporting the transaction.
ADNAN ALI
These structures have existed for many years and are often entirely legitimate. In some cases, they reflect historic tax planning arrangements, while in others they simply
Bridging & Commercial
That shift is creating opportunities for lenders willing to engage with complexity rather than avoid it.
88
This is often where deals begin to run into difficulties. Many lenders are comfortable with a property but become less so once international ownership arrangements enter the picture.
EXPLAINED
The additional due diligence requirements can lengthen timescales and, in some cases, result in opportunities being declined altogether. For brokers, this can often be where frustration begins. They may have a strong asset, experienced investors and a viable lending proposition, yet still struggle to find a lender prepared to work through the complexities of the ownership structure. The result is that perfectly good transactions can spend weeks moving between lenders before finding a home. In this case, GB Bank was able to assess the structure, understand the investors involved and move quickly through the credit process. From introduction to completion, the facility was delivered within a matter of weeks, allowing the borrower to refinance existing debt and move forward with certainty. Working with a broker that has years of experience structuring complex funding requirements was helpful in this case; however, the bank can support less experienced introducers through the funding process provided that the borrower and security are of a high quality. The transaction clearly demonstrated the value of strong broker relationships.
visibility, consistency and credibility. Brokers looking to build a presence in this area need to spend time within the communities they want to serve, attend events, engage with professional networks and build genuine relationships over time. Simply relying on inbound enquiries is unlikely to be enough. However, this is not a market reserved exclusively for a small group of established specialists.
James comments: “GB Bank’s offering occupies somewhat of a gap in the lending market. Loans of circa £10m–20m are too small for some of the sophisticated debt fund lenders that might otherwise compete here. And leverage of more than 55–60% LTV and, just as importantly, sensible interest service cover ratios rule out the mainstream clearing bank lenders.
Many of the most successful brokers operating in this space have built their networks gradually through consistent engagement and a willingness to invest time in understanding client needs. Trust is critical, particularly when dealing with international investors, and this is something that can be earned through expertise, reliability and delivery.
“In addition to the flexible approach, the team were efficient and a pleasure to deal with. We look forward to completing more transactions with the bank going forward.” Building overseas contacts
As overseas investment into UK property continues to increase, brokers who understand the dynamics of the market and develop relationships with lenders capable of handling more complex structures are likely to find themselves well placed.
There is a significant amount of overseas capital actively seeking opportunities within the UK property market. Many of these investors are sophisticated operators with substantial portfolios, significant liquidity and ambitious growth plans. They’re not looking to complete a single transaction and disappear; they’re building portfolios and creating long-term investment strategies. That creates a considerable opportunity for brokers.
The demand is there, the capital is available, and the opportunities are growing. For brokers willing to invest the time to build the right relationships, this could become one of the most rewarding areas of the market over the coming years.
The challenge is that this market is strongly driven by relationships. Many overseas investors prefer to work with trusted advisers, and introductions frequently come through existing professional networks. Lawyers, accountants, wealth advisers, family offices and established business contacts often play a central role in bringing transactions together. As a result, brokers who are not already operating within these circles can sometimes view the sector as difficult to access. In reality, the barriers are often lower than people assume. As with most relationship-led markets, success comes from
89
July/Aug 2026
No QS Required on Refurb Costs up to £100k Fast Refurbishment Bridging Finance
Up to 75% of Purchase Price 100% of Refurbishment Costs Up to 75% LTGDV Loans from £100k Terms up to 12 Months
The whole process from start to finish has been brilliant and completely refreshing. Will Fox, Mortgage & Protection Advisor
The Goldentree Difference In property development, momentum matters. Goldentree provides fast, flexible development and bridging finance, helping developers and property investors move with confidence.
As a privately funded direct lender, our experienced team understands the realities of development, enabling quicker decisions, greater flexibility and a more responsive approach.
Why developers and brokers choose Goldentree
No Quantity Surveyor required
No red book valuations
For refurbishment costs up to £100,000, reducing delays and simplifying the process.
We use in-house surveyors and Automated Valuation Models (AVM’s) instead.
Direct lending
Flexible funding
Decisions made quickly by experienced property professionals.
Facilities structured around your project, not a rigid lending model.
In-house legal team
Trusted expertise
A streamlined approach designed to support faster completions.
Supporting developers, property investors and brokers across the UK for over 25 years.
Speak to our specialist team call
01925 846 420 or email info@goldentreefs.co.uk
goldentreefs.co.uk
EXPLAINED
The case for in-house lawyers Whether it’s over ransom strips, planning, title or complex leases, an in-house legal team can identify issues before they become problems and advise whether they might af fect a lending decision
Words by
PHIL DERBYSHIRE
Managing director at Goldentree Financial Services
Bridging & Commercial
92
EXPLAINED
When people talk about speed in specialist lending, the focus is usually on underwriting or valuations. In reality, one of the biggest causes of delay—and even of deals falling over completely—is the legal process.
Immediate discussions
The instinct can be to see legal as the final stage before completion but, in my experience, that is already too late. The real value comes from involving legals much earlier, while there is still time to identify issues, have sensible conversations and find practical solutions.
“We’re part of the decision-making process from the outset. If we can identify a potential issue early enough, there’s usually more time to find a practical solution,” she says.
Specialist property finance exists to solve problems that mainstream lenders often cannot. Speed has always been important but, today, brokers and borrowers are looking for more than just a quick turnaround. They’re choosing specialist lenders because they want certainty of execution, flexibility, experienced people and confidence that someone will look at the
Kate Clough, our head of legal services, often says that the legal team’s role isn’t simply to advise once a deal reaches completion.
That joined-up approach also changes how quickly decisions can be made. Instead of waiting for questions to go backwards and forwards between different firms over several days, our surveyors, underwriters and legal team are all speaking to each other as part of the same business. If something needs discussing, it happens there and then. One example that stands out involved a
Of course, moving quickly should never come at the expense of managing risk. Kate makes an important point: “Speed and risk aren’t mutually exclusive. It’s not about cutting corners or missing things out. It’s about bringing the right expertise together early enough to make informed decisions.” I completely agree. Our legal team has spent more than 20 years working on bridging and development finance transactions. They’ve dealt with everything from ransom strips and Land Registry restrictions to planning issues and complex lease structures. Very little surprises them. That experience means they are not just identifying risks; they’re helping the lending team understand which issues can be managed and which genuinely change the lending decision.
“The quickest deals are usually the ones where the right people are involved from the start” deal commercially rather than simply follow a process. That is why we made the decision more than 15 years ago to bring legal expertise in-house.
developer who approached us after another lender withdrew late in the process. They were building 44 homes in south Wales, work had already started on site and they urgently needed a development facility of more than £5m.
We believe the two biggest causes of delay in bridging and development finance are valuations and legals. That’s why we don’t outsource either. Our RICS chartered surveyors carry out valuations in-house and our legal team works alongside our lending team every day.
We received the enquiry on a Thursday afternoon. Our BDM and surveyor were on site by 9am on Friday, the deal was underwritten over the weekend, our monitoring surveyor attended site on Monday and the first drawdown was released on the following Friday.
For us, it’s not about saving a few days but about having the right conversations at the right time.
Speed versus risk?
Our BDMs can sit down with our legal team while a deal is still being structured and ask questions about title, planning, lease clauses or access before the application has gone too far. If there’s an issue, we’d rather know on day one than three weeks later. Sometimes, those issues can be resolved. Other times, they can’t. Either way, brokers and borrowers are getting answers before they have spent unnecessary time and money.
People often assume that completing a deal quickly means corners have been cut. I’d argue the opposite. The quickest deals are usually the ones where the right people are involved from the start. The same applies to more legally complex transactions. We recently funded the acquisition of 33 long leasehold apartments where the timetable was particularly tight. Having surveying and legal expertise in-house helped us meet the deadline while also reducing the client’s upfront costs by avoiding multiple external appointments.
93
There are lessons here for brokers, too. One of the simplest ways to keep a deal moving is to give the lender the full picture from the outset. If there are title issues, planning complications, easements or access concerns, don’t wait for them to come out during legal due diligence. Raise them early. The earlier everyone understands the challenges, the sooner they can decide how to deal with them. On urgent transactions, ordering searches at the beginning of the process can also save valuable time. The specialist lending market has evolved significantly over the past decade and I think borrowers’ expectations have changed with it. Speed will always matter but, increasingly, they’re looking for certainty, transparency and lenders who can make pragmatic decisions. For me, that’s where in-house legal teams can make a real difference. Not because they make deals easier but because they help identify challenges earlier, solve problems more efficiently and keep transactions moving without compromising the quality of the decision-making. Ultimately, fast lending isn’t about doing less due diligence. It’s about doing it sooner.
July/Aug 2026
Bridging Finance, Done Differently. Whether it’s a quick purchase, a time-sensitive opportunity or a property chain in need of a solution, our bridging finance helps your clients move fast with confidence.
Fast decisions
Quick turnaround from enquiry to offer.
Flexible lending
Tailored solutions for a wide range of scenarios.
Experienced team
Specialists hwo understnad complex property deals.
Brokers first
Clear communication and common sense approach.
Key features
Bridging loans from £100k - £5m
Loan terms from 2-36 months
Up to 75% LTV day one
Heavy refurb up to 70% LTV
Fast decisions and practical solutions
Need a bridging solution? Talk to our team today.
Common-sense underwriting We take a practical view of each case and focus on finding solutions that make sense.
What else we do
Bridge-to-Let Bridge now, exit onto a BTL.
Buy-to-Let Long-term lending for specialist cases.
Talk to our sales team sales@lendco.co.uk +44 (0)333 414 1495 www.lendco.co.uk
Development Exit Exit finance for completed schemes.
OPINION
If a property does not qualify for a buy-to-let loan because it needs work, bridge-to-let finance is an option that is straightforward and time-efficient and can help with profits when timescales shift
With funding costs still high and property investors adapting to new legislation and changing market conditions, choosing the most appropriate finance has become as important as selecting the right property. For investors buying assets that need some work before they can be let, bridge-to-let finance is becoming an increasingly popular route.
If a project is completed ahead of schedule, many bridge-to-let products also allow borrowers to refinance onto their BTL mortgage early. As bridging finance is naturally more expensive than long-term borrowing, moving onto the lower-cost mortgage sooner can reduce the overall cost of funding the project. For investors carrying out straightforward light refurbishments, this flexibility can make a meaningful difference to profitability.
The specialist lending market has evolved to support this type of investment. Many properties purchased by experienced landlords don’t fit the criteria for a standard BTL mortgage on day one. They may require cosmetic improvements, have a poor EPC rating or simply not be in a lettable condition.
The refinance itself can also be more straightforward than arranging two separate facilities. Depending on the lender, much of the underwriting has already been completed during the initial application, meaning there may be less paperwork at the refinance stage. Some lenders are also able to minimise or even remove the need for a second set of legal work. While every lender structures their products differently, these efficiencies can save both time and money.
Bridge-to-let products are designed with these projects in mind, allowing investors to complete the purchase, carry out the necessary works, then move on to a longer-term mortgage once the property is ready.
Some lenders also reward borrowers who stay with them by offering a reduced rate on the subsequent BTL mortgage. These
Certain exit One of the biggest benefits is the certainty of having an exit strategy in place from the outset. Rather than arranging a bridging loan and then starting to search for a BTL lender several months later, the route onto long-term finance is already established. That gives borrowers greater confidence that, once the works are complete, they can refinance without having to begin the process from scratch. That certainty can be valuable because refurbishment projects rarely run exactly to plan. Timelines can change, contractors can finish earlier than expected, and works may take longer than anticipated. Knowing what the refinance process looks like before the project starts allows investors to focus on the refurbishment itself instead of worrying about arranging their exit.
Bridging & Commercial
Words by
BEN PIKE
Senior broker sales executive at Lendco
96
OPINION
incentives won’t be available across the whole market but, where they are, they can reduce the overall cost of the transaction and are worth considering alongside fees, flexibility and service. Simpler for brokers
Knowing what the refinance process looks like before the project starts allows investors to focus on the refurbishment itself instead of worrying about arranging their exit”
Bridge-to-let can also simplify things for brokers. Instead of managing two separate applications with different lenders, products that combine the bridge and the exit mortgage often mean one underwriting team oversees the case from beginning to end. That continuity can reduce duplication, improve communication and make the process easier for everyone involved. There can also be a commercial benefit for brokers. Some lenders pay procuration fees on both the bridging loan and the BTL mortgage, recognising that advisers are supporting clients through two stages of the same transaction. While product suitability should always come first, it’s a structure that reflects the additional work involved in guiding a client from purchase through to long-term finance. Bridge-to-let will not be the right answer for every investor or every property. However, where a property needs work before it qualifies for a standard BTL mortgage, it offers a practical and well-planned route from acquisition to long-term ownership. With a clear exit strategy, the ability to refinance as soon as works are complete, and the potential to reduce both administrative and funding costs, it’s easy to see why the product is continuing to grow in popularity within the specialist lending market.
97
July/Aug 2026
K
Up to 75% L T G DV
ONVERS I O N
AST TRAC
OC
48 h ours
M F L I E G R to H T Up 90
U
RB
0.
V
B M V R
I Up
to
10 0%
LT P P
E: enquiries@colenko.com
D G E
Products Products Products T: 020 3920 6150
RA Fro T m % 55
LT
STEPPED
E
%
Built for decisive lending.
B
thin
H
colenko.com
G
R
OPINION
Paint the big picture When broker, lender and valuer combine their expertise, complex transactions can be visualised and opportunities arise
Words by
Photography by
LUKE WATSON
CONNIE BURKE
Director of intermediary sales and lending at Recognise Bank
Bridging & Commercial
100
Luke Watson
OPINION
T
he most interesting specialist lending deals rarely fit neatly into a box. Hotels, leisure assets, mixed-use estates and properties with future development potential don’t always fit neatly into traditional lending criteria. However, for experienced brokers and specialist lenders, these are often the transactions where genuine value can be created. Success in these markets depends on more than simply assessing bricks and mortar. It requires lenders, brokers and valuers to understand the wider story behind an asset, the borrower’s long-term objectives and how the business will evolve over time. A recent £4.75m bridging transaction completed by Recognise is a good example. Large leisure estate The deal involved a long-established, family-owned estate in Scotland, comprising a hotel, two 18-hole golf courses and land with planning consent for a golf driving range, alongside proposals for holiday lodges. The client wanted to refinance existing borrowing while releasing additional capital to invest in improving the estate and supporting the next phase of its development. For broker John Hewitt, director at Lathro, the transaction began long before any lender became involved. Having worked with the client for many years, he understood not only the existing borrowing arrangements but also the broader ambitions for the estate. As discussions progressed, it became clear that consolidating several facilities into one structured loan would provide
Bridging & Commercial
102
OPINION
“We have to be prepared to look beyond a checklist, work closely with good brokers and experienced valuers and properly understand the story behind the numbers” the flexibility the business needed. After reviewing the specialist lending market, John identified that we could arrange a viable lending option, and the process became a genuinely collaborative exercise. Over several weeks, he worked closely with the client to gather detailed financial and operational information while maintaining regular dialogue with the lending team as the proposal progressed through credit approval. Complex deals are rarely straightforward—that’s rather the point of specialist lending. Multiple income streams, varied asset classes and future development plans inevitably generate questions but, when brokers have a deep understanding of their clients, and lenders have direct access to decision-makers, those conversations become productive rather than problematic. Puzzle pieces put together The more we understood about the estate, the clearer it became that the valuation alone didn’t tell the whole story. The underlying assets were established, the family had owned and operated the estate for generations and there was a clear, credible strategy for creating additional income through further investment. Rather than viewing the hotel, golf course and development land as separate components, we assessed how they worked together as a single business with a well-defined growth plan. That holistic assessment allowed us to structure a
£4.75m bridging facility that not only refinanced existing debt but also released capital to fund refurbishment works, site preparation for the new golf range and costs associated with securing further planning permission. Specialist lending is often described as relationship-driven, and transactions like this show why. Every participant brought different expertise: the broker understood the client, we focused on structuring the right solution and the valuer provided independent insight into both the existing asset and its future potential. Unconventional future My view is that the commercial property market will continue to produce more of these complex, less conventional opportunities. Investors are diversifying, businesses are looking for new ways to maximise the value of their assets, and many of the best transactions simply won’t fit neatly into a standard lending model. That’s where specialist lenders need to earn their keep. We have to be prepared to look beyond a checklist, work closely with good brokers and experienced valuers and properly understand the story behind the numbers. That doesn’t mean stretching appetite or ignoring risk. Far from it. It means asking the right questions, getting close to the detail and making informed lending decisions based on the whole picture. When the broker, lender and valuer all bring their expertise to the table, complexity does not have to be a barrier. Sometimes, it’s exactly where the opportunity lies.
103
July/Aug 2026
Tomatoes are fruit. And ScotLend lends across England, Wales and Scotland.
The name may cause a few misconceptions. Our lending doesn't.
No drama. Just deals. Go on then. Give it a scan.
LARGER LENDING. SAME ORTUS APPROACH. OVER £75M+ OF LENDING DEPLOYED ACROSS RECENT TRANSACTIONS.
£39M (MV)
LONDON MIXED USE PORTFOLIO
27 property titles Completed in 15 working days
£17M
HOTEL DEVELOPMENT EXIT
Premium UK hotel portfolio redevelopment Major investment and repositioning programme
£12.25M
GRADE A INDUSTRIAL STABILISATION
Five unit Grade A industrial scheme Entering stabilisation phase
£10.7M
HOTEL PORTFOLIO STABILISATION
28 keys across three UK locations 36 month term
BACKED BY
020 3637 505
ortussecuredfinance.co.uk
enquiries@ortussecuredfinance.co.uk
OPINION
Developments can take a major turn for the unexpected. Seasoned finance professionals can respond with decisions to keep projects on the rails
Words by
GAVIN DIAMOND
CEO at Inspired Lending
I
have always admired people who make difficult jobs look uncomplicated—those who have spent years mastering their trade and rarely make a fuss about what they do. They simply have the confidence to keep making the right judgement as circumstances change. Specialist lending is much the same because, for all the focus on pricing, products and process, experience still counts for a great deal.
Never straightforward The deals that genuinely require specialist funding usually have something sitting underneath them that needs proper judgement. It might be the ownership structure, the proposed exit or the security itself, but every transaction has its own characteristics, and every borrower brings a different set of circumstances. That’s why I’ve never believed specialist lending can simply be reduced to a straightforward product set.
I’ve always believed the first lending decision is rarely the one that defines a loan. Once the money has gone out the door, circumstances change, new information comes to light and projects develop in ways nobody could have predicted at the outset. That’s where experience really earns its keep, because good specialist lending is about continuing to make sensible decisions throughout the life of a loan, not simply making a good decision on day one.
People sometimes assume experience is measured by how many deals somebody has completed. Personally, I’ve never really agreed with that because I think experience is measured by the quality of the decisions you continue making throughout the life of the loans that you write. There are transactions where we’ll compete as hard as anybody because we understand the borrower and believe in the exit. Equally, there are deals where the risk simply doesn’t justify trying to compete with somebody who has reached a different conclusion.
There has probably never been more competition in specialist lending. More lenders are chasing the same business and pricing has become far more aggressive than it was only a few years ago. What I am not convinced by, though, is the suggestion that specialist lending has somehow become simpler because, if I’m honest, I think the opposite has happened.
Bridging & Commercial
Everything I’ve talked about up to this point sounds perfectly sensible in theory. The question, of course, is whether you stick to those principles once a project becomes more difficult because
106
OPINION
that’s when experience either proves itself or it doesn’t. We’ve just seen exactly this type of situation ourselves on one of the largest facilities we’ve ever written. The loan was originally a £5.7m refurbishment facility secured against a mixed-use property in Surrey. As the works progressed, costs increased and a number of issues outside the development itself had to be worked through. The overall proposition therefore looked very different from the one we’d originally funded. Now, you could look at those developments and decide the loan had become a problem. We looked at exactly the same information and asked ourselves a different question. Does the underlying project still make commercial sense?
“That’s where experience really earns its keep, because good specialist lending is about continuing to make sensible decisions throughout the life of a loan, not simply making a good decision on day one”
That was why we agreed to additional funding, extended the facility and continued supporting the borrower while the refurbishment reached completion. By the time the loan was repaid through a long-term refinance, the facility had grown to £6.3m, but the thinking behind every decision remained exactly the same, and this approach resulted in a successful outcome for the client. Our private funding model facilitated this in a way that may not have been possible with a different funding structure.
For us, that’s what specialist lending has always been about. It isn’t about producing the quickest terms or writing the biggest loan. It’s having the confidence, experience and ability to keep making the right decisions when circumstances change because, more often than not, they’re the decisions that determine a successful exit for both the borrower and ourselves. The first lending decision gets the loan completed. Those that follow usually determine whether it was the right one in the first place.
107
July/Aug 2026
IT’S OFTEN THE LAST KEY IN THE BUNCH THAT UNLOCKS YOUR REDEMPTION When a loan defaults, securing possession quickly and effectively becomes critical. Our LPA Receivers & Recoveries team identifies the most effective route to possession, tailored to your specific circumstances — cutting through complexity and protecting your position. Fast assessment. Decisive action. Quicker recovery. We don’t stop at the first door. We keep working through every option until we find the key that fits, moving swiftly to deliver results. Contact our team to discuss the key to unlocking your redemption.
Hinesh Varsani
Matthew Perrett
Mark Downham
Michael Yianni
hvarsani@bmortlakes.com
mperrett@bmortlakes.com
mdownham@bmortlakes.com
myianni@bmortlakes.com
07841 249737
07377 596758
07494 104857
020 7323 1100
17 Hanover Square, Mayfair, London W1S 1BN t: 020 7323 1100 www.bmortlakes.com
OPINION
Every experienced developer was once a beginner, and supporting their growth goes far beyond agreeing a loan
Words by
SIDORELA TAYLOR
Portfolio manager at BLG Development Finance
JUSTIN FRIEND Senior valuation surveyor at BLG Development Finance
Bridging & Commercial
One of the most rewarding parts of working in development finance is seeing clients grow in confidence and experience. Many of the projects we fund are delivered by established developers with a strong track record. However, some of the most satisfying transactions are those where we support someone through their first development finance facility. Every experienced developer had to start somewhere. Behind every successful portfolio is a first project, a first lender and a first experience of navigating the development finance process. Recently, we had the opportunity to introduce a client to BLG Development Finance and support him through his first development finance facility. The transaction was a good example of why such funding is more than simply providing a loan. It is also about understanding the borrower, recognising the experience they already have and guiding them through the parts of the process that are new to them. Adjacent but different field Although this was the client’s first development finance facility, he was not new to construction. He had successfully operated their own scaffolding business for many years and built up extensive practical knowledge of the construction industry. Through his work on residential projects, he understood how sites operate, how works are sequenced and why quality and good project management are so important.
110
OPINION
The client had also completed several residential renovations, which gave him experience of managing contractors, budgets, programmes and building works. From a construction perspective, he had a strong foundation. However, borrowing development finance introduced a different set of requirements. For many first-time borrowers, the challenge is not necessarily delivering the development. It is understanding what a professional lender requires, which documents need to be provided, how the due diligence process works and what will be expected throughout the life of the loan. These are areas where even experienced developers may benefit from guidance and support from their lender.
The development comprised two residential properties. The project progressed successfully through the agreed funding stages, supported by regular monitoring and communication. As it moved forward, the client also became more familiar with the requirements of working with a professional development lender. The scheme has now reached a milestone; the project is completed and the first sale achieved. For a first-time developer, this is a significant accomplishment. It represents months of planning, financial commitment, hard work and problem solving. It also provides valuable experience that can be carried into future projects.
Seeing the wood for the trees Branching out Development finance involves much more than agreeing a loan and releasing the funds. Before a facility can complete, there are valuations, legal documents, planning information, build cost reviews, monitoring surveyor appointments and a range of due diligence checks to work through. These steps are important because they ensure both lender and borrower have a clear understanding of the development, the costs and the proposed delivery plan. The relationship continues after the loan has completed. Monthly monitoring visits, progress reports and staged drawdowns all form part of the process. For someone using development finance for the first time, this can feel unfamiliar and, at times, overwhelming.
One successful project often creates opportunities for the next. Every development will bring its own challenges, but the client now understands both the practical delivery of a residential scheme and the requirements of a development finance facility. He has gained experience in lender reporting, monitoring visits, staged funding and the importance of maintaining regular communication throughout the loan. That experience will be valuable as he considers his next development. For BLG Development Finance, the transaction has also allowed us to build a relationship with a client whose ambitions are continuing to grow. Strong lending relationships are not built through transactions alone. They are built through trust, communication and working together to achieve a successful outcome.
Cleared path From the beginning, it was clear that our involvement would go beyond arranging the facility. The client had the practical knowledge and experience needed to deliver the development, but also benefited from our support through each stage of the finance process. By clearly explaining how the facility worked, what information would be required and what he could expect as the project progressed, we were able to make the process more straightforward and reduce uncertainty. Development finance should not feel like an obstacle to delivering a project. When expectations are clear, and communication remains open, clients can focus on managing the development and delivering good-quality properties. Throughout the transaction, we encouraged the client to ask questions whenever he was unsure. Whether the discussion related to valuation reports, legal documents, monitoring visits or drawdown requests, regular communication helped build a strong working relationship from the outset. Rather than seeing BLG Development Finance as a distant lender, the client saw us as a partner who was invested in helping the project succeed.
“DEVELOPMENT FINANCE SHOULD NOT FEEL LIKE AN OBSTACLE TO DELIVERING A PROJECT” 111
July/Aug 2026
OPINION
Groundwork for growth
can help a first-time borrower feel supported throughout the project. Seeing this client progress from securing his first development finance facility to completing the development and achieving the first sale has been extremely rewarding. The successful outcome reflects the hard work, commitment and construction experience he brought to the project, together with a collaborative funding relationship that supported him throughout. Every experienced developer started with a first project. Being able to help someone successfully navigate that first step is one of the most rewarding parts of working
There can sometimes be a perception that development finance is only available to large or highly experienced developers. In reality, many successful developers begin with smaller schemes. The size of the project is only one consideration. The strength of the proposal, the borrower’s experience, the quality of the professional team and the willingness to communicate openly are all equally important. A background in construction, experience in a trade or a
BEING AVAILABLE TO ANSWER QUESTIONS, EXPLAINING UNFAMILIAR PROCESSES CLEARLY AND PROVIDING REASSURANCE WHEN NEEDED CAN HELP A FIRSTTIME BORROWER FEEL SUPPORTED THROUGHOUT THE PROJECT track record of completing renovation projects can provide a strong foundation for someone looking to take the next step into property development. With the right funding and professional support, that experience can be turned into a successful residential scheme. This transaction is a reminder that development finance is ultimately about people as much as it is about property. Loan facilities, interest rates and security structures are all important, but the quality of the relationship can make a real difference to the borrower’s experience. Being available to answer questions, explaining unfamiliar processes clearly and providing reassurance when needed
Bridging & Commercial
in development finance, and it reinforces something we strongly believe at BLG Development Finance: our role is not simply to fund developments, but to support the people delivering them. We look forward to continuing that relationship as this client takes the next step in his development journey, and to helping many more first-time developers turn ambition into successful, completed schemes.
112
Funding Smaller Developments
Made Simple
Tailored funding solutions for smaller developments Smaller Development Funding Loan sizes from €37,500 to £1,000,000, including single-unit and single property developments Up to 65% LTV on land with residential planning consent Up to 65% LGDV towards build costs No loan-to-cost calculation – helping to simplify the funding structure Flexible security options, including additional collateral where required Lending across England, Wales and Scotland
Let’s discuss your project Fast decisions. Flexible solutions. Built around your ambitions.
First-time developers considered
www.ascotbridgingfinance.co.uk
01925 467170
LIMELIGHT
Masthaven raises £15,000 at Three Peaks charity mountaineering They’ve only gone and done it. A team of 14 from Masthaven Finance has completed the National Three Peaks Challenge— climbing the highest mountains in Scotland, England and Wales in just 24 hours, covering 26 miles and almost 3,000 metres of ascent along the way. The team took on the gruelling challenge to raise money for Spread a Smile, the UK charity that supports seriously ill children and young people receiving treatment in NHS hospitals, hospices and at home, bringing moments of happiness and relief to families going through incredibly difficult times. The lender set out with a fundraising target of £10,000 but thanks to the generosity of brokers and industry partners across the sector, the final total smashed through that goal, raising over £15,000. The challenge was as demanding mentally as it was physically, but the team say it was worth every step for a cause they’re immensely proud to support. Every donation, big or small, will make a huge difference to a child’s life, and Masthaven would like to thank everyone who donated, shared and cheered the team on every step of the way.
Bridging & Commercial
114
LIMELIGHT
Masthaven summer party recap
July/Aug 2026
Backstory
J
JOSH KNIGHT You’ve spoken about having a clear vision of what you want to achieve. What are your key priorities for your first six to 12 months months in the role?
osh Knight joined Glenhawk as sales and marketing director in May, moving on from another management role at Octane Capital. He discusses what drives volume, being in the same room as brokers, cutting through a noisy market and the biggest growth opportunities in niche and complex asset classes
We’ve hired five people—three external BDMs, one internal BDM and a product leader— since the turn of the year, so my first priority has been to help our new team members settle in and ensure they feel happy and confident they can deliver.
What attracted you to this position, and why was it the right time to move? I had been eager to test myself in a more senior position and the Glenhawk role presented itself at the right time. I’m relishing the opportunity to have oversight of the distribution and marketing strategy and product development—the three things that interest me the most. I’m loving it already.
In the longer term, I will be implementing a distribution and marketing strategy, with the aim of cutting through the noise in the market and driving consistent deal flow. I’ll also be working with our product team to create loans to sharpen our edge, some of which will be announced very soon.
You’ll be leading sales, marketing and product teams—three areas that need to work closely together. How is this arranged at Glenhawk?
You’ve built a career around sales and relationshipsled growth. What do you think brokers appreciate when working with others?
We view ourselves as one team; including all three in decision-making is key. We sit together in the office, we socialise together and everyone’s opinion is valid when we form strategy.
I don’t think brokers have unreasonable expectations: availability, honesty, reliability and a splash of personality. Not too much to ask, is it?
Having spent years in origination and marketing at Octane Capital, what lessons or experiences from your previous role will you bring to Glenhawk?
What changes have you seen in the specialist finance market during your career, and what do you think will define the next phase for lenders?
That, for BDMs, effort and output are key to driving volume. In a market as competitive as ours, being physically present with your brokers as much as possible is imperative. Relationships drive what we do and building relationships is infinitely more effective in person.
The bridging market has changed considerably over the last few years. It’s become very saturated and, consequently, very noisy. The lenders with a true point of difference—whether that be product, service, trustworthiness or all three—and those with robust funding lines will stay the test of time.
Where do you see the biggest emerging opportunities in niche and complex asset types, and how is the market evolving in these areas? If you weren’t working in financial services, what career do you think you might have ended up in? Sales was always my calling; I’m sure I’d have ended up selling in another market.
What’s a small thing that always makes your day better? My children. I am lucky to have three young sons. They drive me loopy but never fail to make me smile.
What’s your hidden talent—or a talent you wish you had? I wish I could sing. When I was a young chap, I had ambitions of making it in a tragic 1990s boy band (and, in all honesty, still do).
As mortgage rates climb, as they have done this year, we see investors targeting asset classes that can deliver better yields compared to single-tenancy, residential properties. An increase in mixed-use enquiries has been notable for us this year. I think it’s a combination of improved returns, diversified income and development opportunities within the permitted development framework that is fuelling this demand.
What excites you most about the next chapter for Glenhawk, and what are you hoping to achieve that will leave a lasting impact? The team. I’m so proud to lead the group we have. And I’m confident we can surpass our ambitious lending targets.
Bridging & Commercial
116
Choosing the right commercial lender shouldn’t be one of them. Commercial lending backed by OSB Group. Intermediaries only.