








Editor-in-chief
Beth Fisher
Magazine manager
Dhuha Al-Zaidi
Creative direction
Beth Fisher
Dhuha Al-Zaidi
Sub editor
Christy Lawrance
Contributors
Alex Upton, Chris Gardner, Kevin Gibson, Jade Keval, Michael Clifford, Guy Harrington, Adam Tyler, Jonathan Samuels, Hafsteinn Hauksson, Gavin Diamond, Tom Cantor, Phillip Evans, Roz Cawood, James Bloom, Michelle Powell, Jamie Chamberlain, Rob Hutchins, Frankie Bromwich, Will Calito, George Ormerod, Liam Lawlor, Andrew Fraser, James Brocklebank, Jamie Jolly
Photography Connie Burke, Adrian Pope
Sales and marketing
Beth Fisher beth@medianett.co.uk
Ellen Townsend ellen@medianett.co.uk
Special thanks SQ1 Team
Cover story respondents Sofia Picciuto, Octane Capital Haftseinn Hauksson
Printing Jam Print
Design and image editing BePro
Bridging & Commercial Magazine is published by Medianett Publishing Ltd
Managing director
Beth Fisher beth@medianett.co.uk 0203 818 0160
Follow us: LinkedIn @Medianett Publishing | Instagram @medianettpublishing
To read about our commitment to the environment and sustainable print publishing, please visit https://bridgingandcommercial.co.uk/page_magazine.
The fallout from the implosion of Market Financial Solutions amid allegations of double pledging has sent a ripple through the bridging sector— one that’s hard to ignore. What started as a single lender issue is now a sector-wide reckoning; it’s another reminder that the consequences of one often don’t stay isolated. They echo across global funders, lenders, brokers, and ultimately borrowers, raising questions about how risk and security is managed, loans books are monitored, and trust and reputation is earned. While the human cost, particularly the staff that were left hand in pocket at the end of February, shouldn’t be overlooked, the bigger picture is hard to ignore: this backlash has exposed weaknesses that were already there.
As Guy Harrington of Fortacre highlights in this issue [p17], warehouse funders are now taking a far closer look at the lenders they choose to back. Following a string of high-profile failures, senior funders are on high alert, scrutinising not just performance, but governance, structure, and long-term sustainability. While that may create challenges for newer entrants or those seeking funding, it also raises an important question: did the market need this reset? As Guy puts it, “things had become too fast and loose in places”—and perhaps this tightening is exactly what will lift standards going forward.
In a market that has taken a few knocks, the conversation is naturally shifting toward sustainability. That’s why we spoke with the BDLA in this issue [p22], exploring what the association sees as its priorities in the months ahead. Its ‘six pillars’ framework spans everything from engagement with regulators and policymakers to strengthening fraud prevention across the sector. But perhaps most pressing is its focus on fostering open dialogue, bringing the industry together to share challenges, insights, and solutions at a time when collective clarity feels essential. Whether these pillars go far enough is a question we leave open, but it’s one worth considering.
Elsewhere, Jonathan Samuels of Octane Capital [p26] offers a timely reminder that choosing a lender should go far beyond the numbers on a term sheet. With nearly two decades in specialist lending, he argues that it’s the less tangible elements—people, judgement, trust, and culture—that ultimately define successful outcomes. In an environment where confidence has been shaken, those qualities are becoming harder to overlook.
Our cover story [p44] presents the 2026 UK Bridging Market Survey, offering a detailed snapshot of how the sector has evolved over the past year and where it may be heading next. The findings point to a market still moving forward, but with some headwinds.
Profitability among lenders is down, while reputation has emerged as one of the most important factors for brokers and borrowers when selecting a lending partner. At the same time, access to talent remains a growing concern, second only to competition.
The survey also highlights broader pressures shaping the landscape. Falling property values, rising defaults, and a cautious macroeconomic outlook are all weighing on sentiment. Some 62% of respondents expect the wider economic environment to have a moderately negative impact on the market this year, while 67% anticipate borrower default rates ticking upwards.
Taken together, the themes running through this issue are clear: standards, scrutiny, and sustainability are no longer background considerations, they’re front and centre. And at the heart of it all sits the need to rebuild and reinforce trust, not just through stronger systems, but through better decisions and more open conversations.
Currently, the market is still finding its footing after a turbulent period. As the dust begins to settle, bigger questions start to surface: is the bridging industry truly bigger than this ripple, or are there further shocks still to come? Will more lenders emerge from the woodwork, or has the sector already absorbed the worst of it? Ultimately, the question is simple—just how strong are we?
Short-term and flexible financing for your clients property projects. From Refurbishments to Regulated Bridging we have fast and flexible solutions.
Highlights include:
• Regulated and unregulated
• Dual-representation: one solicitor for both parties saving time and money
• Refurbishment Bridging up to 73% net LTV
• Covering auctions, house-flips and landlord refurbs
• Access to expert support, including Underwriters
• AVMs available up to 65% LTV on regulated bridging, and up to 75% LTV on unregulated bridging.
www.lendinvest.com
“Brokers remember which lenders are pragmatic rather than defensive, transparent rather than evasive, proactive rather than reactive. Those memories shape long-term partnerships, influence future decisions and build reputations that outlast any market
Identifying key growth areas and rising borrower expectations
Creating Fortacre at the right time / Adam Tyler reveals route to supporting lenders this year
This underrated company structure sets lenders apart
An economist’s take on geopolitics and its impact on bridging
UK bridging market survey exposed
Compelling credit / A hidden lender test
A technical solution for broker pain points
The evolution of case packaging / The resurgence of SME developers
Michelle Powell
Celebrations and adaptations at Anderson Wilde & Harris
Building a new era at United Trust Bank
MIPIM diary entry / SIP events worth attending
Jamie Jolly
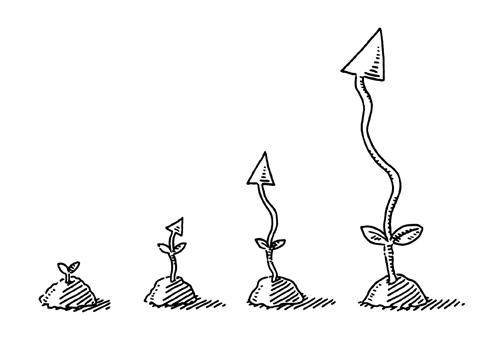
Despite concerns over standards in specialist lenders, bridging lending is resilient and demand remains high. We speak to professionals who share where they’re observing, areas of opportunity, how they are adapting to capitalise on these and how borrower expectations influence their products
Alex Upton Managing director for specialist mortgages and bridging finance at Hampshire Trust Bank
The strongest demand is coming from established landlords who are actively restructuring portfolios with intent. This is not expansion for growth’s sake. It is disciplined capital recycling, strategic refinancing and a deliberate shift into semi-commercial and mixed-use assets where income and risk profiles can be shaped more precisely. Bridging is increasingly being used as a planned part of an investment lifecycle rather than as reactive finance. That shift reflects a sector that has matured.
The driver is structural pressure. Regulation, taxation and funding costs have permanently altered holding economics. Investors are responding by becoming more deliberate about leverage, ownership structures and long-term resilience. The private rented sector is consolidating around experienced operators who understand that finance must underpin strategy from the outset, not repair it later.
Chris Gardner CEO at Atelier
The strongest demand is for residential development. Looking at our pipeline, 2025 roughly saw a split of 50% residential, 25% care and 25% purpose-built student accommodation (PBSA). This year, that has already jumped up to 75% residential, with the remainder split between care and PBSA. This shift in demand is being driven by lower interest rates, as well as greater site availability at more acceptable prices. Many landowners had been maintaining high prices even in the diminished market of the last few years, but schemes are now looking to yield much better value, which in turn is helping shape more positive market sentiment.
Kevin Gibson Operations director at Ascot Bridging
We’re seeing the strongest growth in demand from professional property investors and SME developers, particularly those seeking short-term funding to unlock value in transitional assets. This includes light and heavy refurbishment projects, auction purchases and properties that fall outside mainstream lending criteria. There is also notable momentum in semi-commercial and mixed-use assets, where borrowers are capitalising on pricing opportunities and yield differentials. Much of this demand is being driven by continued market fluidity, motivated vendors, restructuring of portfolios, planning gains and investors repositioning assets ahead of anticipated rate stability. Speed and certainty of execution remain critical, particularly where borrowers are competing at auction or managing time-sensitive exits.
Jade Keval Sales director at Somo
We’re seeing three clear fertile areas.
First, SME growth funding. This is the most encouraging trend. We’re seeing established UK businesses looking to expand, acquire stock, invest in premises or restructure existing borrowing onto more sustainable terms. That’s a positive signal. But many of these businesses are finding unsecured routes expensive, restrictive or capped too low. When there’s property in the background, securing the loan can materially change the economics.
Second, we’re meeting increasing demand for AVM and desktop-based deals. Brokers and borrowers are getting comfortable with AVM and desktop assessments. That confidence is being driven by familiarity, speed and the need for certainty earlier in the process.
Third, landlords. Our Landlord’s Breathing Space product was only launched in January and demand has been strong from day one. A significant proportion of enquiries are refinancing existing debt, often where rate pressure or expiring facilities are creating unnecessary strain. Landlords aren’t exiting; they’re restructuring intelligently.
Michael Clifford Commercial director at DCI Finance
We are seeing the strongest growth from professional investors and SME developers who are focused on execution rather than speculation. Specifically, demand is spiking in three key areas.
The first is refurbishment and transitional assets, where projects require light-to-medium work and borrowers prioritise speed and certainty to stabilise cash flow before refinancing.
Next are mixed-use and commercial segments where mainstream banks remain constrained by low leverage appetite or rigid asset-class restrictions.
The final area of demand is time-critical transactions. These can include auction purchases, portfolio restructures and urgent capital raises, where certainty of delivery is more valuable than the headline interest rate.
The primary catalyst is the evolving supply of capital behind specialist lenders. Unlike previous cycles, there is a significant influx of flexible capital that is fundamentally changing lender behaviour. There is a move away from vanilla so, instead of retreating to low-risk, standard assets to protect origination flow, lenders are leaning into their niche strengths, be it higher leverage, asset complexity or rapid execution.
This shift has created more choices for borrowers with non-standard assets. However, it also means the market is no longer uniform and success now depends on knowing exactly which lender will back which specific risk and why.
Alex Upton Managing director for specialist mortgages and bridging finance at Hampshire Trust Bank
Expectations have become more exacting. Efficiency is assumed. What borrowers are assessing is judgement.
They expect early, credible indications of appetite. They expect direct access to decision-makers who can navigate layered ownership vehicles and complex portfolios without reverting to formulaic solutions. And they expect funding structures that remain coherent when plans evolve.
The conversation is no longer centred on speed in isolation. It is about whether funding has been structured correctly and whether the lender has the conviction to hold that structure steady when circumstances shift. That demands depth of expertise rather than reliance on automated processes.
Chris Gardner CEO at Atelier
Speaking to developers shows the need for speed is often proving to be a fallacy—what borrowers are actually looking for is certainty in decision-making and execution. Once certainty has been established, however, we are seeing more momentum and a greater emphasis from borrowers to execute deals more quickly. In a fast-moving market, slow deals can easily fall by the wayside and regulatory roadblocks can often mean agreements become protracted when a scheme is in the pipeline.
In a competitive market, borrowers are looking for lenders that can offer certainty of execution to get deals completed and spades in the ground.
Jade Keval Sales director at Somo
“Speed” and “flexibility” are words every lender uses. The difference now is that they are baseline expectations, not differentiators.
Borrowers expect fast decisions, clear communication and digital convenience but they still want a human being who understands nuance and has years of experience to draw on. We’ve been lending for 11 years and our model has always been relationship led. AI enhances that; it doesn’t replace it.
Practically, that means: AVMs and desktop valuations; retypes to keep momentum when valuations shift; indicative offers issued in 30 minutes; dual representation and streamlined legals; and, soon, a seven-day bridge. The key is matching the tool to the case. Borrowers don’t want shortcuts; they want efficiency. That’s a very different proposition.
Kevin Gibson Operations director at Ascot Bridging
Borrowers are more commercially sophisticated than ever. They expect clarity, responsiveness and flexibility, not just headline rates. Speed remains essential but so does transparency around process and decision-making. We’ve adapted by refining our underwriting approach to focus on common-sense lending, backed by experienced decision-makers who can assess the full context of a deal rather than relying purely on automated outputs. At the same time, we’ve streamlined internal processes to reduce friction, improving turnaround times from enquiry to issuing credit-backed terms. Flexibility around structuring has also become increasingly important. Tailored repayment options, staged drawdowns for refurbishment projects and pragmatic views on complex income structures are all areas where we’re evolving to meet borrower expectations.
Michael Clifford Commercial director at DCI Finance
Borrower expectations for speed, flexibility and certainty have matured and they are now benchmarked against the high standards of the specialist market. As lenders differentiate themselves, borrowers are shifting their focus toward deal structure and execution rather than just the headline price. This evolution is driving product adaptation in four primary ways. First is sophisticated capital structuring. We are seeing a move towards net-drawn and uncapitalised interest structures. These allow borrowers to preserve liquidity and avoid interest drag, ensuring capital is used efficiently throughout the project life cycle. Second is early-stage credit clarity. Borrowers now demand transparency from day one. We are adapting by providing greater upfront clarity on how leverage, risk and exit strategies are assessed, reducing the black-box feel of traditional underwriting. Next is velocity through case ownership. Speed isn’t just about the initial offer—it’s about maintaining momentum. We’ve prioritised proactive case ownership, ensuring that the transition from offer to drawdown is seamless and doesn’t get stalled by administrative friction.
Finally is purposeful digital integration. From a digital perspective, borrowers value reduced friction over novelty and we know how important it is for borrowers and brokers to always have access to our underwriting team so that deals can be talked through to get to the right lending decision. Our use of technology and AI is strictly functional and is designed to help our team focus and use their experience to fund deals for more borrowers.
Chris Gardner CEO at Atelier
The common refrain in recent years across the market was “survive to 2025”, but it’s no longer far-fetched to anticipate a market upswing and, indeed, we’ve been planning for the market to turn since 2024.
From our conversations in the industry, this year it is clear that there is newly engaged optimism across the sector and resource planning is being prepared in light of this. When the market turns, it turns quickly, and we’ve invested to be prepared for the opportunities across all areas including residential, care and PBSA.
Kevin Gibson Operations director at Ascot Bridging
Strategically, we’re continuing to strengthen our relationships with brokers and professional introducers, ensuring we remain closely aligned to emerging borrower requirements. Market intelligence at ground level is invaluable.
We’re also investing in operational efficiency, enhancing systems, refining credit workflows, and ensuring senior accessibility within the business. In a competitive market, reliability and certainty of funding are powerful differentiators. Looking ahead, our focus remains on disciplined growth. We aim to expand selectively within refurbishment and value-add bridging, while maintaining a prudent risk framework. The ability to combine agility with underwriting discipline will be key to sustaining long-term growth in the current environment.
Michael Clifford Commercial director at DCI Finance
Our strategy is built on a back-to-basics philosophy, prioritising consistent, high-speed execution and we are making deliberate adjustments to our model to better support origination in a high-demand environment. These key strategic adjustments include: clearly defining and communicating our credit appetite, so brokers can place deals efficiently and with confidence; understanding the borrower outcomes we are serving (higher-net lending and profit protection) and designing products around borrower cash-flow and execution risk, not just LTV metrics; and actively managing risk throughout the loan’s life, not just at entry.
Crucially, as lender differentiation increases, brokers and intermediaries have a greater responsibility to stay current on appetite, criteria and funding nuances. With more choice comes more complexity, and successful outcomes increasingly depend on matching the deal to the capital that is right, not just what is available. At a strategic level, we see ourselves as a credit-led business operating in a capital-rich environment.
Jade Keval Sales director at Somo
Alex Upton Managing director for specialist mortgages and bridging finance at Hampshire Trust Bank
We have responded by reinforcing the core principles of specialist lending rather than diluting them. Increasing aggregate exposure limits enables us to support larger professional portfolios with confidence. Enhancing flexibility within our bridging range reflects how short-term finance now integrates into longer-term investment planning. Manual underwriting remains fundamental because complex portfolios require informed judgement where asset classes, ownership structures and exit strategies intersect.
In a market defined by structural change, specialist lending is not about accommodating complexity. It is about mastering it.
Two big shifts are giving brokers the silver-service treatment and new product development— we won’t stop innovating until every borrowing need has been met.
Behind the scenes, we’re working on a major enhancement to how brokers interact with us, which we’ll unveil this year. For the first time, we’re formally bringing to market upgraded functionality that will give introducers greater visibility, faster feedback and more control across the life of a deal.
In addition, we’ve launched Somo Secured Business Loans. We’ve long funded business-purpose borrowing through bridging, but this marks a clear expansion. This will offer loans from £27,500 to £3m, with terms from one month to three years and rates from 7.5%—with no reliance on trading accounts or turnover-based assessments.
So, instead of defaulting to unsecured lending for business needs, brokers are increasingly asking a different question: “Is there property security here?” That reflects a wider shift in thinking.
Why make finance difficult?
When growth is prioritised over governance, lenders can fail. Diversification becomes non-negotiable as warehouse lenders take a closer look at those they are funding. Being a new wholesale funder at this time has proved positive
Words by GUY HARRINGTON Founder of Fortacre
The name Fortacre is deliberate. “Fort” speaks to strength, security and resilience. “Acre” is the land, the real estate that underpins everything we do. In a market where trust and stability have never mattered more, that felt like the right foundation to build on.
Fortacre is a new wholesale funding platform founded this year. We provide warehouse facilities to non-bank bridging and commercial lenders, typically those with loan books of between £20m and £100m. We sit behind the lender, not in front of the borrower.
Think of us as an aggregator: our capital is deployed across a diversified portfolio of lending businesses rather than concentrated on a single balance sheet. That structure is deliberate, and it matters now more than ever.
The idea didn’t come out of nowhere. I founded Glenhawk in 2017 and spent several years scaling it into one of the UK’s more active bridging lenders, with annual origination reaching circa £500m and over £2bn raised from institutional capital partners, including major investment banks. Those were formative years. Every funding negotiation, every facility restructure, and every credit committee meeting taught me something about what lenders actually need from their senior funders and, just as importantly, what they don’t get.
on the other side of the table from the investment banks. Most were excellent. But it became clear that there is a significant funding gap in the market for lenders operating between £20m and £100m in assets under management. These businesses are often too large for high-net-worth or family office capital, but too small to justify a full warehouse line from an investment bank. That gap is exactly where Fortacre operates. We are building a bridge, if you’ll excuse the pun, between early-stage lending
than 50% higher than the same period in 2024. The sector’s growth trajectory is undeniable.
But growth alone does not tell the whole story. The past 12 months have delivered some hard lessons. Several high-profile lender failures have shaken confidence, not in bridging itself but in the governance and oversight structures around it. Allegations of double-pledging, questions around beneficial ownership and sudden funding line withdrawals have, rightly, put senior funders on alert. Warehouse lenders and institutional capital providers are now scrutinising the quality of loan books, the integrity of the borrower base and the operational infrastructure behind the lenders they are funding.
platforms and the scaled institutional funding they aspire to.
Strong market undermined
I sat through hundreds of meetings
The UK bridging market is in strong shape. According to the Bridging & Development Lenders Association, total lender loan books stood at £13.4bn at the end of Q3 2025, with bridging applications reaching £11.7bn in the quarter alone. That followed a record Q3 in which loan books hit £13.7bn, more
I don’t think that’s a bad thing. In fact, I’d argue the market needed it. Things had become too fast and too loose in places, with growth prioritised over governance. What we’re seeing now is a recalibration, a raising of the bar and, for well-run operators, that is an opportunity rather than a threat.
Eggs in one basket
The concentration risk exposed by recent events is something Fortacre is specifically designed to address. Several senior funders found themselves overexposed to a single lender when things
went wrong. Our model spreads capital across tens of lending businesses, creating a genuinely diversified portfolio of borrowers, asset types and geographies. No single lender failure can materially compromise the platform. For institutional investors looking to deploy into bridging, that diversification is increasingly non-negotiable.
As a new entrant, the heightened diligence environment works in our favour. We have built our platform from scratch with institutional-grade compliance, technology and reporting baked in from day one. We are not retrofitting controls onto an existing operation. An experienced team, robust technology, genuine sourcing networks and a deep connection to real estate are no longer nice-to-haves. They are the minimum requirements for any credible new entrant. The diligence hurdle for securing senior funding has risen materially and that is healthy.
Bridging finance is a sector I love. The people in it are sharp, entrepreneurial and genuinely collaborative. Having spent years building within it as a direct lender, stepping into the wholesale funding space felt like a natural evolution, using everything I’d learned about institutional capital to support the
“What we’re seeing now is a recalibration, a raising of the bar and, for wellrun operators, that is an opportunity rather than a threat”
next generation of lending businesses.
I’ll be honest, the launch has gone rather better than expected. We have discussions in place covering over £2bn of potential funding at various stages of progression. My keyboard is starting to show the wear. It seems the appetite for a well-structured wholesale funding platform in this part of the market was even greater than I’d anticipated.
Our target is £1bn in loans under management by 2028; this is ambitious, but I believe we can do it. Key to getting there will be hiring exceptional people, building deep relationships with our lending partners and, critically, having some fun along the way. The bridging market is full of talented operators who deserve access to properly structured, reliable senior funding. Fortacre exists to provide exactly that.
Collaboration is essential for the specialist finance industry, and spending time with peers tells you a lot about what may be happening behind the scenes. The Bridging and Development Lenders Association is therefore looking at how it supports and oversees members, and has set out six key pillars to shape its priorities
Words by ADAM TYLER CEO at the Bridging and Development Lenders Association
This year marks my 21st year of running trade associations within the specialist finance industry. Over that time, I have seen the market go through many cycles, from periods of exceptional growth to moments of real challenge. Perhaps the most dramatic was the financial crisis of 2008, when the commercial finance sector was reduced to just 42 lenders across the entire market.
Experiences like that tend to stay with you. They shape how you look at the industry and, more importantly, what role you think trade bodies should play. One of the most important lessons I have taken from those years is that sectors are at their strongest when those involved work together.
That philosophy sits at the heart of the Bridging and Development Lenders Association (BDLA) today.
When I first started measuring the bridging market back in 2005, the total loan book stood at around £300m. Today, the loan book of BDLA members alone stands at £13.4bn. That level of growth is remarkable by any measure and demonstrates just how far the sector has come.
Bridging and development finance has evolved from what was once considered a niche product to an essential component of the UK property market. Investors rely on it to move quickly on opportunities, developers use it to unlock projects
that might otherwise stall, and homeowners increasingly turn to bridging solutions to help manage complex transactions or fix broken property chains.
However, growth at this scale also brings responsibility. As the sector expands and attracts more attention from regulators, investors and borrowers, maintaining high standards becomes more important than ever.
The role of the BDLA is not simply to represent the industry but also to help guide its continued development in a way that supports sustainable growth and strengthens confidence in the sector.
As we move forward into what I see as a new era for the association, our work will be guided by six key pillars that will shape the BDLA’s priorities in the years ahead.
Alongside these pillars, we are strengthening how we support and monitor our membership. As the sector grows, maintaining high standards across it becomes increasingly important. We are therefore continuing to evolve our onboarding procedures for new members, ensuring that lenders joining the association demonstrate a clear commitment to responsible lending, transparency and strong operational processes from the outset. In addition, we are enhancing our annual review process for existing members, taking a closer
look at areas such as internal procedures, customer engagement and charging structures. The aim is not oversight for its own sake—it is to ensure that BDLA membership continues to represent a genuine mark of quality and professionalism.
The first pillar focuses on our relationship with regulators, the government and policymakers. Bridging finance operates in a complex regulatory environment, particularly as large parts of the market sit outside traditional regulated mortgage frameworks. That makes representation all the more important.
The BDLA has long worked with regulators such as the FCA and policymakers within the Treasury to ensure the realities of short-term property finance are properly understood when decisions are being considered. Building on that work, we are strengthening our engagement with Westminster, helping policymakers recognise the important role our sector plays in supporting property investment, refurbishment and housing supply.
The second pillar centres on fraud prevention. Fraud is an evolving hazard for all financial services businesses and becoming increasingly sophisticated.
No lender can tackle this issue alone. It requires cooper-
trade associations, open dialogue has always been central to how I operate. The industry forums I have organised over the years have consistently been well attended, and I intend that same spirit of collaboration and discussion to continue within the BDLA.
The fifth pillar focuses on education and professional standards. As bridging finance becomes more widely used, it is vital that those working within the industry have access to structured training and professional development.
Initiatives such as the certified practitioner in specialist property finance qualification have already helped to provide a recognised educational pathway for professionals. Encouraging more lenders, advisers and brokers to engage with these programmes will help ensure the industry continues to build credibility and maintain high standards. Looking ahead, greater collaboration between trade associations across the specialist finance space will also play an important role in improving education and training opportunities for the next generation of industry professionals.
The sixth pillar looks at technology and the evolution of origination. Over the past decade, we have seen significant advances in loan origination systems, sourcing platforms and data-driven underwriting tools.
“Looking ahead, greater collaboration between trade associations across the specialist finance space will also play an important role in improving education and training opportunities for the next generation of industry professionals”
ation between lenders, technology providers, insurers and professionals working across the sector. The BDLA has already begun bringing members together to share knowledge and develop collective responses to emerging threats. Our aim is to build further momentum around these initiatives, ensuring lenders have access to the tools and intelligence they need to identify potential risks earlier and protect both their businesses and their customers.
The third pillar focuses on data and market insight. Over the years, the BDLA’s quarterly lending data has become one of the most widely referenced sources of insight into the performance of the bridging market.
As the industry grows, the importance of reliable, detailed data only increases. That is why we are continuing to enhance our data collection processes and invest in systems that allow us to gather and analyse information more effectively. At the same time, we are exploring opportunities to work with partners across the sector who hold complementary data. By collaborating with technology platforms and specialist data providers, we can build a more complete picture of how the market is evolving and provide insights that benefit lenders, brokers and investors alike.
The fourth pillar is about bringing the industry together. Trade bodies play an important role in creating opportunities for open dialogue and collaboration across the market.
There has never been a better way to understand what is happening in the industry than by spending time with your peers. Conversations between lenders, brokers and other professionals often reveal the trends and challenges that statistics alone cannot capture. Throughout my career running
These innovations are helping lenders operate more efficiently while improving the experience for borrowers and brokers. The BDLA is fortunate to have a growing number of technology providers among its associate members, and we intend to showcase more of these through future events and initiatives.
Ultimately, the continued expansion of bridging and development finance reflects strong demand for flexible, short-term funding from property investors, developers and homeowners. At the same time, the industry’s increasing focus on professionalism and higher standards has encouraged more brokers and borrowers to engage with the market, creating what many would describe as a flight to quality.
As the trade body for the sector, the BDLA remains committed to championing transparency, responsible lending and strong professional standards. Our members operate to high standards and the sector itself remains robust, well capitalised and an important source of liquidity for the UK property market.
Property lending will always be cyclical and there will inevitably be peaks and troughs along the way. The key is how we navigate those cycles together as an industry.
If the past two decades have shown us anything, it is that when lenders, brokers and industry partners collaborate and share knowledge, the industry becomes stronger, more resilient and better equipped to support the wider property market.
That spirit of collaboration will continue to guide the work of the BDLA as we move into the next phase of the sector’s development.
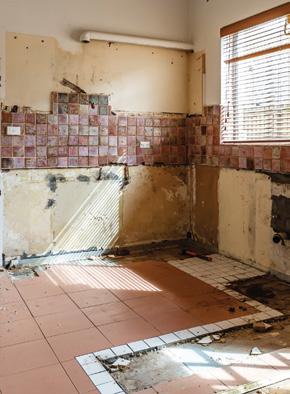
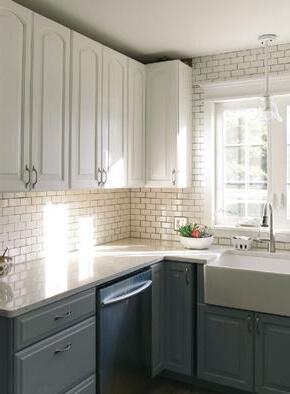
Bridging transactions are rarely straightforward and can come unstuck at any stage. What sets a lender apart is how its people handle pressure and face up to tortuous problems. Brokers seeking a lender should look beyond the term sheet
Words by JONATHAN SAMUELS CEO at Octane Capital
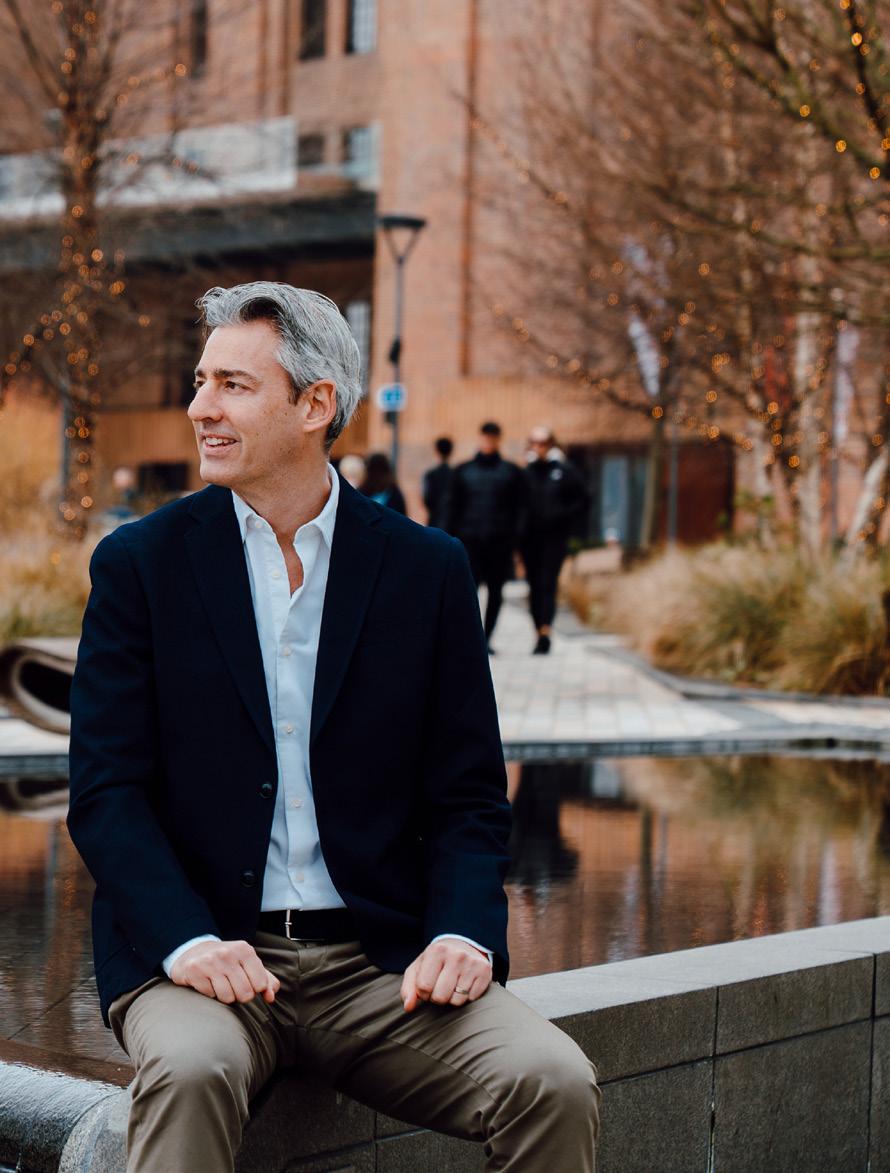
n bridging finance, conversations often revolve around numbers—rates, leverage, criteria, turnaround times. And these are important. But anyone who has worked in the sector knows that what brokers and clients remember most isn’t what appears on the term sheet. It’s how a lender responds when a deal becomes complex.
Bridging transactions are rarely straightforward. Valuations may come back differently from expected, legal issues can emerge late in the process and exit strategies often require adjustments. When that happens, products and processes take a back seat. What really matters is the people making the decisions and how they handle the pressure.
That lesson becomes clearer the longer you spend in our market. I founded Octane Capital in 2017 alongside Matt Smith, since inception, the business has lent more than £2bn across the UK specialist property market. Prior to that, I founded Dragonfly in 2009, which also originated more than £2bn of lending before the sale.
Having spent nearly two decades in specialist lending across multiple market cycles, one lesson stands out consistently: while products, funding structures and technology evolve, the quality of people and judgement remain the defining factors in successful lending.
Bridging is a fast-moving, specialist market, but it is relationship-driven at its core. Brokers don’t just submit cases—they are putting their own credibility on the line with every introduction. That means they need confidence that the lender has depth, experience and ownership to navigate challenges.
Choosing a lender isn’t simply about the maximum LTV, the advertised turnaround or the latest pricing model. It’s about trust: the ability to rely on someone to make the right call when things don’t go according to plan. And that trust comes from people—the senior executives, the underwriters, the BDMs and the credit teams—who form the backbone of the business.
The industry has ways of highlighting individual performance, such as power lists, awards and peer recognition. These are flattering but their real significance is deeper. They signal consistency, capability and the environment in which people operate.
When a professional is recognised for their influence or contribution, it reflects not just personal achievement but also the culture around them. Consistency, ownership and collaboration are amplified in an environment that values them. It is no coincidence that high-performing individuals emerge from teams where shared standards are enforced, where expertise is respected and where leadership is active, not passive.
Awards and recognition are, of course, welcome. They are evidence that the principles of service and professionalism
are working in practice. Nonetheless, the most enduring measure of success is the ability to maintain those standards day after day, particularly when the pressure is high.
The true test of any lender is not how smoothly the deals that fit neatly within policy complete, but how teams respond when things get complicated. Last-minute valuation adjustments, unforeseen legal challenges or shifting borrower circumstances are the moments when service, judgement and culture are truly tested.
Brokers remember those moments. They remember which lenders are pragmatic rather than defensive, transparent
“Having spent nearly two decades in specialist lending across multiple market cycles, one lesson stands out consistently: while products, funding structures and technology evolve, the quality of people and judgement remain the defining factors in successful lending”
rather than evasive, proactive rather than reactive. Those memories shape long-term partnerships, influence future decisions and build reputations that outlast any market cycle.
In this context, individual talent matters, but systemic alignment matters more. It is the combination of capable professionals within a culture that empowers them that delivers consistent results. A lender may have the brightest people but, if the environment is siloed, competitive in the wrong way or focused purely on short-term metrics, the benefit is diluted.
As the sector matures, the tools at a lender’s disposal have evolved. Technology improves efficiency, institutional funding lines deepen and competition intensifies. Yet, while processes and systems can be replicated, human judgement cannot.
Experienced professionals make critical decisions about complex exit strategies, property quality and sponsor credibility. They assess nuance and context that data alone cannot capture. And they communicate with brokers in ways that machines cannot, anticipating concerns, clarifying expectations and providing assurance in uncertain moments.
“Brokers remember which lenders are pragmatic rather than defensive, transparent rather than evasive, proactive rather than reactive. Those memories shape long-term partnerships, influence future decisions and build reputations that outlast any market cycle”
“For brokers evaluating lenders, the advice is simple: look beyond the term sheet”
“In a sector increasingly dominated by process, technology, and capital, culture has become the ultimate differentiator”
This human factor is increasingly important in a market where capital and technology alone no longer differentiate lenders. Price and process can attract initial attention, but relationships and trust sustain long-term partnerships.
Service excellence is often misunderstood. It is not simply the speed of decision or transactional efficiency. It is consistency, clarity, accountability and a willingness to take ownership. It is visible in everyday—the timely return of a call, the proactive management of expectations and the competence to solve problems without unnecessary escalation.
Recognition from the industry, including service-based awards, is one way to validate these behaviours. Yet the real proof is in the memory of brokers and borrowers: do they know that the lender will deliver when it matters most? Do they trust that the people on the other side of the transaction understand the nuance, the risk and the consequences?
Bridging finance is often described as short-term lending, but the businesses behind it are built over the long term. Recruitment is not just a functional exercise—it is a strategic decision.
Bringing in the right people ensures that growth is sustainable. High-performing individuals thrive in an environment that provides clarity, support and accountability. Misaligned recruitment, by contrast, creates friction, slows decision-making and erodes the consistency that brokers rely on.
It is not just about filling roles. It is about developing teams where leadership is active, collaboration is embedded, and expertise is applied consistently. That alignment allows firms to remain agile while maintaining disciplined risk management—a balance that is essential in bridging.
In a sector increasingly dominated by process, technology and capital, culture has become the ultimate differentiator. Strong culture doesn’t happen by accident. It is deliberately nurtured through leadership, recruitment and standards of accountability.
The right culture aligns sales, credit and operational teams around a common purpose. It ensures that ambition is balanced by discipline, that growth does not come at the expense of consistency and that service is embedded into every interaction rather than being an afterthought.
High-quality recruitment is critical. Technical expertise alone is not enough. Individuals must have commercial judgement, resilience and the ability to navigate ambiguity. They need to understand that in bridging, reputation travels fast; every interaction is noticed and every decision has implications for brokers and borrowers alike.
Culture is intangible but its impact is tangible. A strong culture underpins consistency, builds trust and provides the framework for individuals to act decisively. Weak culture allows inconsistency, encourages short-term thinking, and erodes confidence among brokers and partners.
For lenders, investing in culture means more than internal communications or team-building exercises. It means recruiting thoughtfully, retaining top talent, establishing clear frameworks and leading by example. It means recognising that the human element is not a cost
to be managed but a differentiator to be leveraged.
In the end, capital can be raised, products adjusted and systems upgraded. But judgement, trust and culture are anchored in people. Those are the attributes that create enduring advantage in bridging finance.
In an industry where deals rarely follow a straight path, where pressures are high and time frames tight, the strength of a lender is measured by the strength of its people and the environment in which they operate. Firms that recognise this, invest in it and nurture it, position themselves not just to succeed in individual transactions but also to shape the market itself.
For brokers evaluating lenders, the advice is simple: look beyond the term sheet. Assess the people behind the business, the environment in which they operate and the consistency of their service. These elements influence outcomes more than any headline rate or advertised turnaround.
Ask about how decisions are made when deals are complex. Ask about tenure and experience across teams. Ask about alignment between credit, sales and operations. These questions will reveal far more about a lender’s capacity to deliver than marketing materials ever could.
At times of political and pricing stress, specialist lenders can be an important shock absorber, making credit markets more resilient. Each episode of instability bring more brokers and borrowers to bridging as a tool for certainty rather than a last resort
Words by HAFSTEINN HAUKSSON Chief economist at Kvika Banki/Ortus Secured Finance
The old line often attributed to Lenin about there being “weeks where decades happen” has been overused in recent years, but the underlying point has rarely felt more relevant. Since Russia’s invasion of Ukraine in 2022 and with US foreign policy becoming harder to predict under the current administration, geopolitical shocks have become more frequent, more persistent and more consequential for markets. For UK property finance, that matters. Geopolitics is no longer a distant backdrop to domestic lending conditions. It is increasingly one of the forces shaping them.
That has become clear again in recent weeks. Military escalation involving Iran
triggered a sharp market reaction in early March, with oil prices jumping and rate expectations shifting rapidly, as investors reassessed the inflation outlook and the likely response from central banks. In the UK, two-year swap rates moved materially higher in a short period of time, and high-street lenders were forced to respond quickly. Fixed-rate mortgage products were repriced—some were withdrawn altogether—and brokers found themselves having to navigate moving terms in the middle of live transactions.
None of this is unprecedented. The pattern has been visible before, including during the 2022 gilt crisis. When markets become disorderly, high-street mortgage lending often gets more cautious and less predictable. Credit does not disappear, but it becomes harder to access on the same terms, at the same speed and with the same confidence.
Stress and structural advantage
if prolonged, put pressure on property values as well as refinancing conditions. But they do tend to highlight the areas where bridging has a structural advantage over more standardised forms of lending: speed of decision-making, flexibility of underwriting and a greater ability to keep transacting when mainstream channels become more hesitant.
There are several reasons for that.
First, bridging lenders are typically funded differently from the major banks. On the high street, the marginal cost of capital is effectively repriced on a near-continuous basis through the spreads and yields on traded debt, while deposit funding is callable on demand. Many bridging lenders, by contrast, operate from committed institutional facilities, private capital or balance-sheet equity that is agreed for a term, does not trade in secondary markets and is not marked to market overnight. That does not eliminate funding pressure, but it can provide more stability and more room to keep lending through periods of market dislocation.
Geopolitics is no longer a distant backdrop to domestic lending conditions. It is increasingly one of the forces shaping them”
This is when specialist finance—bridging in particular—tends to earn its spurs. That does not mean bridging is somehow immune to macro volatility. It is not. Periods of market stress can raise exit risk, weigh on confidence, and
Second, bridging loans are short-duration instruments. That matters. A lender trying to price a five-year fixed mortgage needs to hedge his interest rate risk using interest rate derivatives such as swaps. A lender writing a 12-month bridge or a floating rate instrument is not exposed to the same interest rate risk. In an environment where these swap rates are shifting sharply from one moment to the next, that shorter duration can be a meaningful advantage since it alleviates some of the need for costly hedging.
Third, bridging remains rooted in asset-based underwriting. Mainstream mortgage lending is often more dependent on income-based stress tests
and standardised affordability models, both of which can become increasingly restrictive when rate expectations move abruptly. Bridging lenders look first at the security, the LTV and the credibility of the exit. That can allow them to respond more pragmatically to market shocks.
Taken together, these features help explain why brokers and borrowers often turn to bridging during periods of instability. When timing becomes critical and the risk of losing terms rises, execution certainty becomes more valuable. For an auction buyer, a homeowner trying to hold together a chain or an investor working to complete ahead of a regulatory or commercial deadline, certainty and speed can matter at least as much as headline price.
Specialist lenders then become an important shock absorber, making credit markets as a whole more resilient during periods of stress.
That helps explain why bridging has continued to grow from a niche product into a more established part of the UK property finance landscape. According to the BDLA, outstanding loan books now exceed £13bn, reflecting the steady expansion of the specialist lending market over recent years. Some of that growth is cyclical—but some of it is clearly structural. Each episode of volatility introduces more brokers and borrowers to bridging as a practical financing tool rather than a last resort.
Risks and confidence
That is an important shift—and one the sector should welcome. But it is not a reason for complacency.
If geopolitical volatility is becoming a more permanent feature of credit markets, then the industry also needs to think carefully about where the
associated risks may surface. The most obvious is exit risk. Just as a bridge is only viable if there is solid ground on the other side, a bridging loan only works if there is a realistic and durable path to repayment, whether through sale, refinance or another source of capital. If mortgage pricing remains elevated for longer or if product availability stays constrained, that path becomes more difficult. If weaker growth and higher energy costs were also to weigh on property values, some equity cushions could prove less comfortable than they appeared at origination.
That does not invalidate the case for bridging. It simply reinforces the need for careful risk management, which has already been made abundantly clear by recent failures in the asset-backed lending space.
For the bridging sector, this is both an opportunity and a test. The opportunity is clear: in a less predictable world, there is real value in being able to provide timely, flexible finance when other parts of the market pull back. The test is whether the sector can continue to scale that up without allowing confidence in the product to outrun prudence in the credit process.
The era of stable geopolitics and broadly predictable monetary conditions is behind us. For UK property finance, that is likely to mean regular episodes where funding markets reprice abruptly and where transaction certainty becomes harder to secure. In that environment, bridging has an opportunity to prove its value not just through speed but also through discipline. The lenders that will define the sector’s next phase of growth are not simply those that can move the fastest in volatile markets but those best able to underwrite the risks volatility leaves behind.
We are a principal development and bridging lender with a forward-thinking approach.
Funding for light, medium or heavy refurbs
Grade listed and student accommodation considered
No exit fee regardless of the build cost
Flexible on experience
Solution driven equity structures
Flexible on PGs
Ability to step in at any stage of the build Experienced team with strong track record in funding PCDs
Pre-agreed equity release available
Acquisitions and development exits
Net Sales proceeds available
Lend against market value NOT 180 day value
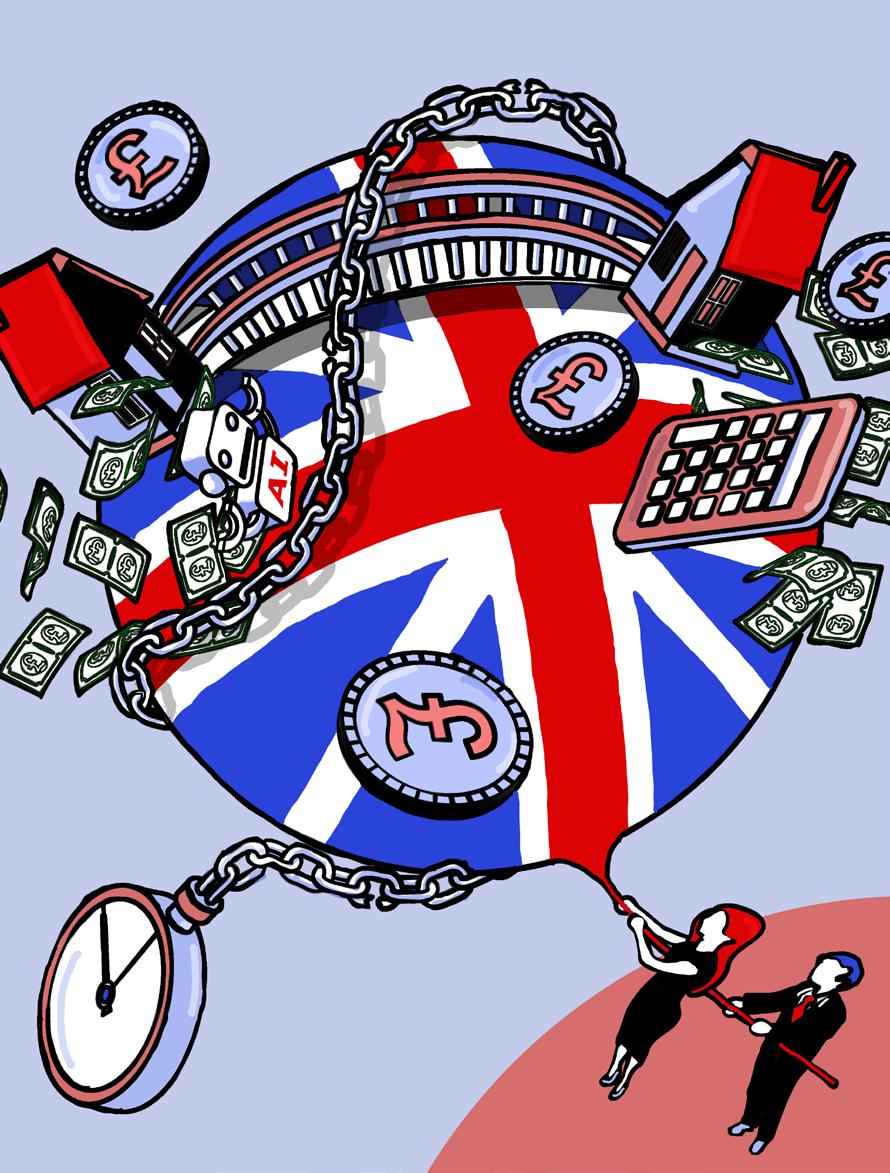
For the ninth consecutive year, Bridging and Commercial discloses its exclusive annual UK Bridging Market Survey. The findings showcase the progress of the bridging industry over the past 12 months, highlighting the trends and challenges that formed loan enquiries and progressed the specialist finance industry. This year’s survey spotlights AI implementation, ESG initiatives in businesses, tackling fraud initiatives, and political impact on bridging—including market predictions for year ahead
Words by DHUHA
Illustrations by VALF
* This publication contains information in summary form and is therefore intended for general guidance only. It is not intended to be a substitute for detailed research or the exercise of professional judgment.
The survey had 29 respondents—27 bridging lenders, one development financier and one specialist residential, bridging BTL and development under. 48% of participants are based in London, while 21% are in the North , 14% in the South, 7% in the Midlands, and 3% in both Scotland and Wales. The business sizes varied, with 28% employing up to 10 people and 50-plus, 17% between 31-40 and 10% between 11-20 and 21-30.
DAYS TAKEN TO COMPLETE
of respondents claimed that profitability in their business went up in 2025, compared to 76% in 2024 of lenders have loan books of £100m or less, up from 57% last year
The number of bridging lender respondents lending over £100m per year has increased to in 2025, compared to 43% in 2024
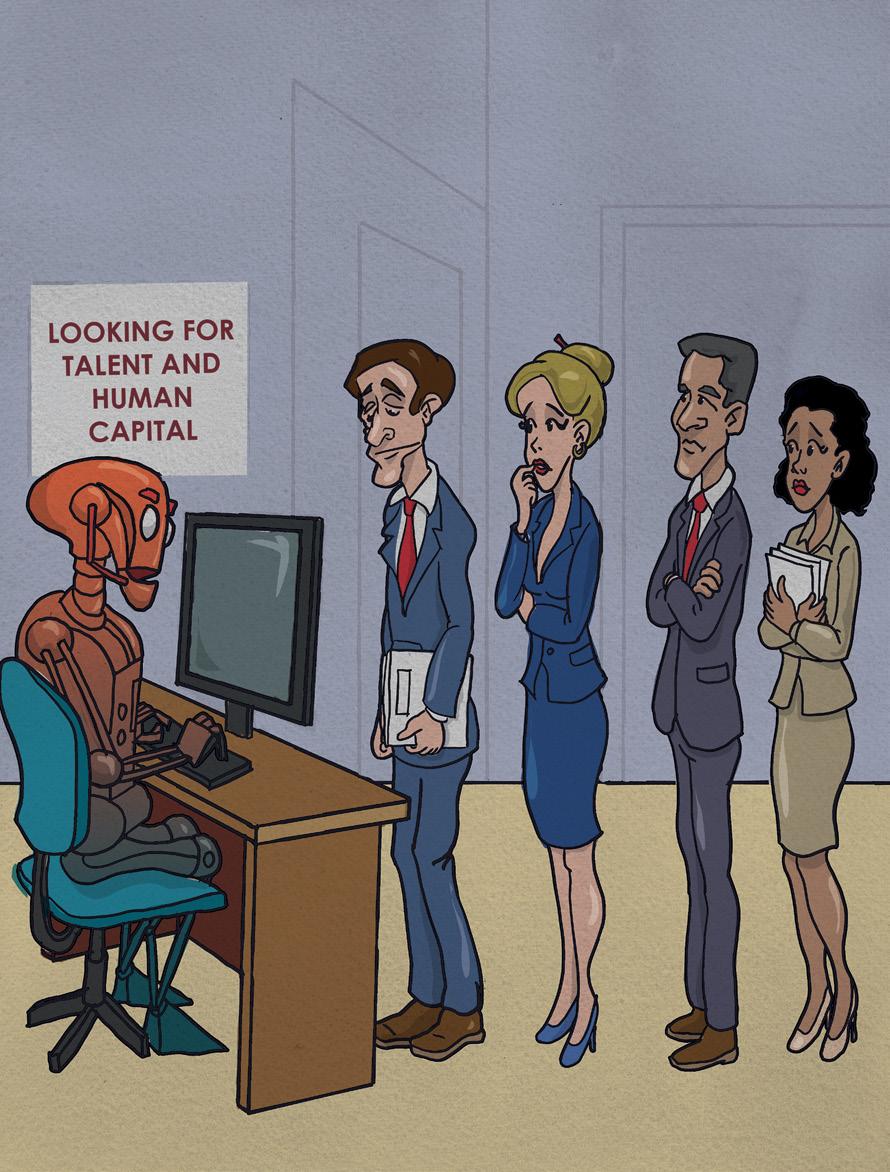
“The growing focus on talent and human capital highlights an important shift within the industry. In specialist lending, where experience, judgement and relationships are critical, people remain a lender’s greatest asset.
Creating an environment where individuals can develop, feel valued and contribute to the wider business is essential. Culture plays a significant role in this. Businesses that prioritise internal progression and invest in their teams tend to build stronger, more sustainable organisations. At Roma, a key measure of success has been the number of colleagues progressing through the business as it continues to grow.”
Senior and Mezzazine
HNW, Private and family office
Forward flow arrangements
Retail deposits
Principa;;y funded
Equity funded
Other types of instituational funder
62%
believed that institutional funding increased in 2025, compared to 73% in 2024
thought competition increased last year, compared to 70% in 2024
• Refurbishment remains the most popular use of a bridging loan, followed by auction purchase
• Pre-development purchase continues to be the least popular reason to obtain a bridging loan
• Independent brokers remained the primary channel for bridging loan originations, followed by master brokers
Speed of execution and reputation of lenders are tied as the most important qualities to a customer (or broker) when choosing a bridging lender, followed by funding flexibility as second, and low pricing and repayment flexibility are tied as the third most crucial quality
Once again, strong origination capabilities overtook strong relationships with brokers as the most important capability for a lender to stay successful—both remain the top picks, cited by over
17%
of lenders introduced variable rates in 2025, compared to 22% last year
Limited access to talent and human capital is mentioned as the second most important business challenge in 2026 Macroeconomic
think maintaining strong relationships with brokers is the most important element to remain successful in the bridging market
of firms are considering implementing AI in their business strategy, compared to 50% in 2025
are considering investment in technology—a decrease from 70% last year
believe that the automated loan management systems that allow live data to be accurately extracted at the click of a button are a key differentiating factor among lenders
24% 69% 35% 62%
of lenders intend to use AI as part of their credit decision-making in the next 12 months-plus, while 21% are already using this
of lenders agree that the introduction of broker portals will significantly increase the volume and efficiency of business
of lenders plan to invest in AML systems
of firms are currently using AVM technology—up from 46% last year, with 17% reporting no plans to implement this
of respondents are using electronic signatures for legal documents—an increase from last year’s 67%
"In periods of uncertainty, structure and discipline become even more important. A clear approach to underwriting, combined with strong internal processes, allows lenders to respond to changing market conditions with confidence. Where some see uncertainty, others see opportunity, and we continue to see experienced borrowers progressing projects with a clear plan."
Irene Thomas Managing director at Mint Property Finance
of respondents believe that the 2026 macro outlook will impact the bridging finance market negatively to a moderate extent
predict borrower default rates will go up slightly in 2026
expect loan extensions to increase slightly
believe origination volumes will remain unchanged, while 24% anticipate it will go up slightly
The extension fee rate is expected to stand at an average of 1–2%, according to
expect the average loan size to remain unchanged in 2025
expect a slight rise in forbearance requests and 66% predict a slight rise in foreclosures over the next 12 months
expect the average loan term to remain the same, while 41% believe it will slightly increase
of respondents


Flexible interest structures
No ERCs or Exit costs
Equity releases to support projects
Bespoke structuring
Rapid execution
Ideal for auction purchases or repositioning
Support for complex borrower structures
No ERCs or Exit costs
Hybrid interest structures available
Underwritten on forward rental income
Terms up to 36 months
Ideal for repositioning or lease-up
Revolving credit ensures funds are already to hand when an opportunity presents itself, and investors are increasingly using them rather than one-off transactions within portfolio management
Words by GAVIN DIAMOND CEO at Inspired Lending
here are instances in specialist lending when a structure that has long existed begins to feel newly relevant, not because it has been entirely reinvented, but because the market around it has changed in ways that make it more closely aligned with how borrowers now operate. In my view, it would seem that revolving credit facilities are having that moment.
As Bridging & Commercial has heard from talking to our team at Inspired Lending, brokers are not simply referencing revolving facilities more often, they are raising them much earlier in discussions and across a broader range of scenarios.
A revolving credit facility provides flexible access to a defined funding line over an agreed term. Capital can be drawn, repaid and redrawn as activity dictates, with interest charged only on the amount actually in use rather than on the full limit, so undrawn funds do not incur cost. At its core, it is a simple structure. However, in practice, where portfolio activity is ongoing, the effect on capital efficiency can be significant.
Historically, these facilities were often described as “chequebook” arrangements or even a “hunter’s licence”, and were typically offered to established landlords with substantial equity who were effectively pre-approved to move quickly when new opportunities arose. At that stage, the emphasis was as much on relationships as it was on speed.
“For us, it is about putting discipline around flexibility, not replacing one with the other”
What is changing now is not the structure itself but how and when it is being considered.
The same core concept is being framed more formally and introduced far earlier within structured portfolio funding discussions, rather than being reserved for a small group of long-standing clients. That change, in itself, says something about how investor behaviour has developed.
The concept has always existed in the specialist space but investors are now planning their funding in a more deliberate way. Increasingly, they are managing pipelines of acquisitions and refurbishments across the year and, as a result, they want structures that support continuity rather than treating each deal as standalone.
Professional landlords are now managing sophisticated, limited-company portfolios. Acquisitions are mapped across the year and exit timelines can extend beyond original expectations. In this kind of environment, liquidity management becomes central to performance rather than an afterthought once a deal completes.
This thinking informed our decision at Inspired Lending to formalise and widen our flexible funding offering. We were already seeing experienced clients ask us for more in-life flexibility. Rather than respond on a case-by-case basis, we chose to establish something to meet that demand within a defined framework. Our approach has been to structure facilities with clear parameters around leverage and term, while still giving borrowers the ability to draw and repay capital as their portfolio activity evolves. For us, it is about putting discipline around flexibility, not replacing one with the other.
In a market where margins are scrutinised carefully and timing can influence overall return, paying interest only on drawn capital can materially affect the economics of repeat activity.
Owen Bentley, our sales director, notes the balance between certainty and cost is increasingly central to broker conversations.
“Clients want certainty that funds will be available when the right opportunity appears but they are equally conscious of servicing capital that is not yet deployed,” he explains. “The ability to draw and repay within an agreed framework can materially change the shape of a year’s activity.”
The enquiries crossing our desk reflect this continuity of activity. They demonstrate that borrowers are seeking funding solutions aligned with portfolio management rather than one-off transactions.
Facilities secured against lowly geared portfolios are being structured to support incremental expansion, enabling borrowers to draw funds as new properties are acquired rather than committing capital in a single tranche at the outset.
The same pattern is evident in our second-charge enquiries too. This includes, for example, an £800,000 flexible facility on a property valued at approximately £3m with a £900,000 first charge outstanding, where the objective was to secure auction purchases, complete refurbishment then recycle capital until the next opportunity arose.
Nathan Wilson, lending manager at Inspired Lending, who was included in the Bridging & Commercial Power List 2026, describes the tone of discussions as increasingly forward-looking. “Experienced clients are already thinking about what comes next,” he states. “The conversation moves from completing a single deal to structuring funding that supports successive stages without layering unnecessary cost.”
The renewed interest in revolving credit facilities does not imply a relaxation of underwriting standards. LTV thresholds remain clearly defined. Use of funds must be understood from the outset. Exit routes must be credible. Exposure, including rolled interest where applicable, must remain within agreed limits.
Formalising our flexible facility was about bringing clarity and consistency to something clients were already asking for. The objective is not to dilute credit discipline but to provide a funding line that reflects how professional investors actually run their businesses day-to-day, year-on-year.
For brokers active in the bridging and commercial space, the increasing prominence of revolving credit facilities appears less like a passing development and more like an indicator of market maturity. The concept itself may not be new, but what is becoming more evident is how naturally it now fits the way experienced investors conduct business—and that alignment is what is placing revolving credit back at the forefront of the specialist lending conversation.
“For
brokers active in the bridging and commercial space, the increasing prominence of revolving credit facilities appears less like a passing development and more like an indicator of market maturity”
Bridging lenders all boast of how quickly they can issue a loan that will meet individual circumstances. The test is how funders perform under pressure–and how adaptable they genuinely are
West One
Since the dawn of time—or so it feels—bridging lenders have been inclined to describe their proposition as, you guessed it, fast and flexible.
Those who require secured short-term lending have come to expect nothing less.
The inherent need for fast, flexible bridging loans is obvious from the way brokers phrase their questions:
“How quickly can you do X?”
“Would you be able to do this even though Y?”
“I know you typically may not do Z, but can you do it for my client?”
While many lenders describe themselves using these two well-worn words, only some have been able to back these claims up in practice.
Niche versus scale
Over the past decade, bridging completion timescales have been steadily getting shorter. As novel technology is integrated and new bridging lenders enter the market (leading to greater competition for deals), this is expected to continue. Meanwhile, many bridging lenders, especially smaller
ones, have had to position themselves within niche areas and offer distinctive products built to be adaptable for non-standard cases.
Economies of scale, on the other hand, assume that larger, established bridging lenders are able to increase throughput and decrease lead times. Larger lenders can do so based on their ability to afford better systems, diversified product ranges for varying levels of risk and larger, specialist teams. It’s only natural, then, that speed and flexibility are ramping up.
Almost every lender describes itself as fast.
Speed can mean many things in the world of bridging, so it would be wise to make sure you understand what a lender means by that.
On one end of the spectrum, some simply use the word fast because bridging loans typically move more quickly to completion than traditional fixed-term loans such as mortgages. However, if that is the only point of alignment a lender has with fast, it’s equivalent to selling a lightbulb on basis of it being bright. True speed becomes clear when
“LENDERS CAN PROMISE TO BE FAST AND FLEXIBLE, BUT THE DIFFERENCE ONLY BECOMES VISIBLE IN HOW A LENDER
a lender can consistently complete faster than the average bridging loan.
To others, fast is associated with charging head first into structuring a loan, taking a bird’s-eye view of the components that make up the loan and figuring out the details as they go along. However, this agile approach can come back to bite the brokers who place cases with lenders who prioritise speed over detail. Rushed efforts can quickly become botched jobs, leaving customers frustrated if a lender decides to back out of a deal once they’ve gained the full picture.
Doing things rapidly also has little value if the progress is held back if the case meets multiple bottlenecks along the way. What sets those who can commit to true speed apart is their ability to keep things moving at the various stages of the application journey, ensuring alignment across sales, underwriting, brokers, legals, valuations and more.
Track records matter in completing bridging deals at pace. They come from applying years of experience in managing the moving parts of transactions, ensuring seamless progress from start to finish.
Like fast, the word flexible is used so often in bridging that its meaning can easily get diluted.
For some lenders, flexible means little more than being open to adjusting rates based on circumstances. Again, this is expected in any bridging loan. Real flexibility in bridging lending goes far beyond such a simple definition. Meanwhile, bridging loans, by their very nature, are flexible in the sense that they provide a level of versatility to borrowers who want to snap up opportunities that cannot be financed through a mortgage. Bridging lenders who describe themselves as flexible on that basis do so only because they offer what is widely considered to be an adaptable product, rather than adjusting their offer themselves. True flexibility means having both the expertise and capacity for structuring funding around a client’s specific needs.
For instance, some loans may require a term for a short period because of an imminent exit plan. In such cases, the borrower benefits from quick access to funding without a lengthy commitment.
Flexibility also extends to property type and use. Many bridging lenders will specialise only in unregulated cases or shy away from mixed-use or commercial assets. However, those who are genuinely flexible have lending criteria that reflect a truly multi-purpose approach covering regulated, unregulated, commercial, semi-commercial and land transactions.
Perhaps most importantly, flexibility should not be confined to the bridging loan itself. In a market where regulated bridging alone now accounts for several thousand loans a year and more than billions of pounds of lending annually, exit routes into longer-term finance are becoming central to delivering certainty around repayment. Therefore, those who want to provide their clients with a complete solution may want to gravitate towards a lender that can produce solutions once the time arrives to exit the bridge.
With many bridging loans exiting onto longer-term finance, lenders that offer refinancing products such as commercial, BTL or residential mortgages can provide additional value. For brokers, this means that when a short-term loan’s exit calls for a longer-term solution, borrowers can access tailored next-step finance from the same trusted lender. Working with the same lender also typically means that a refinancing exit can be achieved at an expedited rate.
Test of the unexpected
Lenders can promise to be fast and flexible, but the difference only becomes visible in how a lender performs under time pressure, under scrutiny or when a deal veers off script.
Consistency in execution, regardless of the loan size or the complexity of the deal, is a strong indicator of a lender worth working with. Over time, this consistency builds trust, which is vital in the broker-lender relationship, and this is what brings certainty and confidence to brokers and their customers.
• Loan size £75,000 - £3,000,000
• No minimum term
• No VAL up to 70% LTV on residential houses
• All types of borrowers considered
• Cosmetic works permitted
• Interest can be serviced or deducted
• Heavy adverse credit considered where exit is sale
• Second charge loans considered
• Dual Representation available on kerbside residential properties
Our Bridge product is perfect for borrowers requiring fast finance. Ideal for the purchase and refinance of residential BTL and HMO
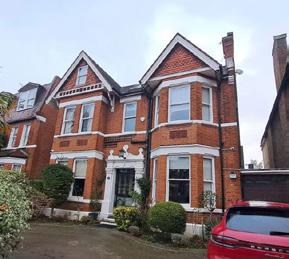
Mint structured a capital raise secured via a second charge against a six-bedroom detached property in West London. The facility enabled the borrower to unlock equity and inject working capital into their established slate supply business to support continued growth.
Location: London Full Facility: £725,000
Loan Term: 18 months LTV: 49%
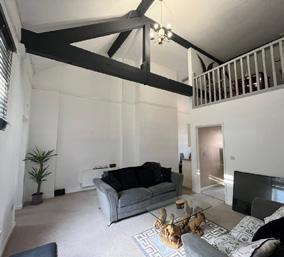
Mint provided a flexible bridging facility to support the purchase of a mixed-use investment comprising a convenience store and coffee shop with three residential flats above. The flats were fully tenanted at completion, with Mint structuring a pragmatic solution ahead of a planned refinance.
Location: Leicester Full Facility: £401,250
Loan Term: 12 months LTV: 75%
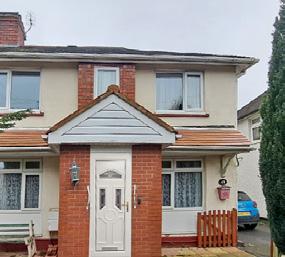
Mint supported a borrower purchasing an ex-local authority four-bedroom semi-detached property at auction. With fast, pragmatic underwriting and a credit-backed decision in principle, the borrower was able to complete quickly and begin refurbishment works ahead of a planned refinance.
Location: Cannock Full Facility: £153,000 Loan Term: 12 months LTV: 75%
Commercial finance is stuck in a rut. Commercial brokers can waste days finding suitable lenders with varying success, while mortgage intermediaries just upload client data and get a suitable funder straight away. So, I built a platform to close the technology chasm between the two
Words by PHILLIP EVANS
Founder and CEO at FundingSearch
Four years ago, I nearly didn’t come back to work. A health scare stopped me mid stride—the kind that forces you to recalibrate everything. Recovering at home, I wasn’t thinking about deal flow or commission. I was thinking about whether I’d spent the last decade doing what actually mattered to me.
I’ve been a commercial finance broker for longer than I care to admit. I’m good at it. I understand the market, I’ve built relationships and I know how to structure deals. But, sitting there in that hospital bed, I realised something uncomfortable: I’d outsourced my creativity to a system that wasn’t particularly creative at all.
The technical side of broking hadn’t challenged me in years. I was doing the same things the same way, just faster. Meanwhile, the whole industry was doing the same things the same way, collectively leaving money on the table and solutions on the shelf.
Market failure, not good business
When I returned to work, I started paying closer attention to something that had always frustrated me: the absolute technology chasm between commercial finance broking and mortgage broking.
Think about it. A mortgage broker can upload client data and instantly see which lenders they qualify for, in order of probability. They get automated document generation, integrated compliance checks, and decision times measured in days. The whole operation feels like 2024 technology.
Now look at commercial finance. We’re still spending 10–20 hours per deal manually researching lender criteria. We’re hunting through pdfs, making spreadsheets, ringing underwriters and hoping the application we’ve painstakingly constructed matches what the lender actually wants. Half of what we send back gets rejected because it doesn’t fit their parameters. Underwriters waste time on mismatched applications. SMEs wait weeks
for funding decisions that should take days.
It’s not a minor inefficiency. It’s a market failure dressed up as business as usual.
And what made me angrier was this: it wasn’t about the brokers being backward. It was about the tooling. We had the skills and the market experience. We just didn’t have the technology that matched what our mortgage colleagues were using. That gap wasn’t there for good reason. It was there because nobody had built the right solution yet.
To start: what drives you up the wall?
That’s what sparked FundingSearch. Not a clever idea from a fintech entrepreneur; a genuine frustration from someone who lives this market every day.
I spent the first six months talking to brokers, lenders and accountants, not asking what they wanted to hear but asking what actually drove them up the wall. The answers were consistent and damning: time waste, mismatched applications, compliance headaches and tools that treated commercial finance like mortgage finance’s awkward younger sibling.
We’ve spent the last two years building something different. FundingSearch connects borrowers, brokers and lenders through intelligent matching technology backed by verified financial data. The platform integrates directly with Xero and Sage, pulling live profit and loss, balance sheet and cash flow data automatically. No self-reported figures. No manual data entry. Just clean, verified information.
From that single business profile, brokers get an instant ranked list of suitable lenders. Matched probability scores. Clear reasoning for why lender A is more suitable than lender B. That 10–20-hour research phase becomes minutes.
On the lender side, they receive pre-qualified applications with complete financial data already verified and included. No more guessing whether figures are accurate. No more underwriters wasting time on applications that never stood a chance.
The platform covers the full commercial finance spectrum: asset finance, invoice finance, working capital, trade finance, merchant cash advance and property finance. Not a vertical solution. A horizontal platform that brokers actually asked for.
Tech heavy lifting with a human
There’s a narrative doing the rounds that fintech and AI are eroding broker relevance. Nothing could be further from the truth.
Yes, FundingSearch is a fintech platform. Yes, it uses AI for intelligent matching. But here’s what matters: the broker is the one enjoying those benefits while remaining completely in control.
The technology doesn’t replace the broker’s judgement. It amplifies it. The broker still decides which lender to approach. They still manage the relationship. They still advise the borrower. What they don’t do anymore is waste 20 hours on manual research that the platform handles in minutes.
We’ve built FundingSearch with what I call a “human in the loop” philosophy. The AI does the heavy lifting: data verification, lender matching and document generation but the broker remains the trusted adviser throughout. The borrower has a real person guiding them from initial enquiry through to completion. That relationship, that expertise and that accountability—those are what borrowers value, and they remain non-negotiable in our model.
If anything, fintech and AI should worry brokers less and empower them more. The real threat to brokers isn’t intelligent technology; it’s being locked into someone else’s network while commissions get negotiated away. We’ve built FundingSearch the opposite way: brokers keep 100 per cent of their commission. They maintain their lender relationships. The technology serves them, not the other way round.
I’m not naive enough to think one platform fixes a market with decades of entrenched practice. But I do think FundingSearch represents what commercial finance could become if we took ourselves as seriously as the mortgage market does.
We’ve built technology that brokers actually want to use, that lenders recognise reduces their risk and their workload, and from which SMEs
benefit because funding decisions happen more quickly. We’ve designed it to preserve broker independence. We haven’t built a network that extracts value from every transaction. We’ve built intelligent software that brokers stay in control of.
The FCA has been clear about where it wants SME lending to go by 2030: open finance, verified data and streamlined processes. FundingSearch exists because that vision matters—because the gap between what commercial finance is and what it could be is too big to ignore.
The technology I wished existed when I started broking years ago isn’t a fantasy anymore. It’s built, it’s working and it’s ready to change how you do deals.
That health scare four years ago taught me something valuable: life’s too short to build things that don’t matter. FundingSearch matters because it solves real problems for real brokers doing real deals.
Let’s close the gap together.

Turn complexity into completion with personal and commercial loans over £1m.
With bespoke underwriting, our dedicated team can support:
• Diverse income streams
• Foreign nationals
• Complex business structures
Contact our dedicated team on 03330 601 565.
Brokers are preparing packages in detail from day one, planning for contingencies such as a change in the market at exit and using structures more creatively to get knotty deals over the line
Words by ROZ CAWOOD Managing director for property finance at StreamBank
The bridging market has continued to grow but the way brokers are structuring those deals has shifted in the past year, with much of that change happening well before a case even reaches a lender’s credit team.
Over the past 12 months, I have seen far more detailed packaging of cases, particularly around exit strategies, timeframes and security. Brokers are now stress testing deals with clients at a much earlier stage and asking the difficult questions upfront.
One of the biggest shifts has been around timeframes. Planning delays, build costs and rate volatility have made it harder to predict how long a development project will actually take. As a result, brokers are now working through worst-case scenarios with borrowers much earlier in the process.
It is not unusual for a client to assume that planning will take six months. A good broker will usually challenge that assumption and ask what will happen if it takes 12 months instead. Often the compromise will be somewhere in the middle, perhaps structuring the finance around a nine-month expectation with contingency built in.
Of course, extensions can still be required. The difference now is that lenders are increasingly seeing deals where the broker has already tested those timescales and discussed the potential outcomes with the client.
Often, brokers are also preparing more than one exit strategy to chime with and exceed lender expectations.
In the past, a sale might have been assumed to be the natural exit from a project. Today, that assumption rarely holds water.
That might mean preparing both a sale schedule and a rental strategy for the same property. If the sale market softens or the timeframe extends, the borrower may then be able to refinance the property onto a term product and retain it as part of a portfolio.
From a lender’s perspective, seeing those options laid out from the outset provides reassurance that the deal has been carefully considered.
Security structures have also become more flexible as brokers work to strengthen applications.
One recent StreamBank completion involved a London-based investor who had secured a property at auction and needed funding to complete within the standard 28-day deadline while also raising capital for light refurbishment works across other properties in their portfolio.
The loan totalled £290,000 at 56% gross LTV. The security structure included a first charge over the auction purchase in Battersea alongside three additional investment properties owned by the borrower.
Part of the funds allowed the client to complete the auction purchase without losing the 10% deposit already paid and the remainder was used to carry out the light refurbishment works ahead of new tenancies. For the broker involved, the key was presenting the deal as a structured portfolio solution rather than a single transaction.
Not every bridging case involves an investor or developer. Some reflect the practical realities of personal circumstances where timing is critical.
For one case in Nottingham, a borrower needed £280,000 to secure the purchase of a new home after separating from a partner. Unless she completed the purchase quickly, she risked being left without
The loan was structured at 61% LTV with a first charge over the new purchase and a comfort charge over another property held in a limited company. An AVM was used to accelerate the process and the exit strategy centred on the sale of the company-owned property, providing a clear route to repayment once the borrower’s situation had stabilised.
While more detailed packaging has become common, the need for speed never disappears.
For a property in Dorchester, borrowers needed bridging finance quickly so they could secure an onward purchase after their property sale stalled.
The loan totalled £317,500 at 43% LTV, secured against both the new purchase and the existing residential property that would ultimately be sold. The application moved from submission to offer within one working day and involved an automated valuation process.
Across all of these cases, one factor stands out more than anything else: broker experience.
The more volatile the market, the more valuable that experience is. Brokers who understand planning timeframes, investor behaviour and lender expectations are often able to shape a deal in ways that make it workable before it reaches underwriting.
That preparation benefits everyone involved. Borrowers gain a clearer view of the risks and the possible outcomes while lenders receive cases that have already been carefully thought through. And much of that progress begins with the work brokers do long before a case reaches a lender’s credit desk.
Whether you’re navigating the strict requirements of a regulated loan or the unique structure of an unregulated asset, we provide expert guidance needed to cut through the noise. Find out more.
Client accepts terms after minor tweaks, broker is on-boarded with us, and a case is submitted via Morpheus platform.
Legals completed via dual rep and title & search indemnity, documents signed virtually.
Monies are drawn.
Have a deal? Get in touch. www.morpheuslending.co.uk
Enquiry lands from a brand new broker, initial diligence undertaken, DIP issued to broker with varying options.
Case underwritten in full, legals instructed and solicitors start working (whilst relying on KYC/DD already completed).
One statistic really caught my eye recently from a report issued by the Home Builders Federation. During the third quarter of 2025, just 45,075 homes received planning permission in Great Britain. According to the findings, that was the lowest quarterly figure recorded since 2012 and more than one-third lower than over the same period the year before.
Let’s face it, that’s the sort of statistic that can very easily filter through the industry news cycle without too much reflection. However, for those of us who spend many hours working in the development space, it says a great deal about how the market has been feeling over the past few years.
Paradoxically, specialist property finance continues to reach near all-time high levels. The most recent figures from the Bridging and Development Lenders Association show lender loan books standing at £13.4bn at the end of the fourth quarter of 2025, still close to the highest levels the sector has ever recorded. Development lending itself increased during the final three months of the year, with more than £420m of development loans written during that period.
Risks in development finance do not fade after completion—exit can quickly turn complex as assumptions made at the outset no longer hold. Looking at the whole life of a project rather than stages aligns better with how developers operate in reality
Words by JAMES BLOOM Director at Alternative Bridging Corporation
If you put these two distinct realities side by side, the picture begins to make more sense. On one hand, the development pipeline may have slowed but, on the other, the demand for specialist funding has not disappeared. If anything, I think this indicates that developers and brokers are approaching projects in a more selective and considered way.
It is precisely in this environment that the structure of development finance begins to come to the fore. Anyone involved in funding projects will know that practical completion rarely marks the moment when the financial risk begins to fade and, in many cases, it is simply the stage where that risk profile starts to change shape.
Even once construction is complete, the project can be far from over in terms of the financials. Units still need to be sold into the market and valuers may revisit their assumptions once the finished scheme is assessed.
I have seen many situations where what initially appeared to be a straightforward exit suddenly became a more delicate exercise than expected. When that happens, the timing of the funding structure can become just as important as the funding itself.
If development finance and exit funding are structured as entirely separate facilities, this moment can coincide with the point where the development loan itself is approaching the end of its agreed term. Developers can therefore find themselves arranging refinancing precisely when leverage is highest and flexibility is already limited. For many, that becomes the most sensitive stage of the entire funding journey.
This is where the traditional sequencing of development finance begins to reveal its limitations.
A development scheme can easily run for two years or more and, as we all know, the wider market rarely stands still during that time. Sales activity can soften, lender appetite can shift and valuation assumptions can evolve as comparable evidence develops. Each refinancing stage therefore becomes a point where the original funding plan must align with whatever the conditions happen to be at that moment.
As many brokers will recognise, market factors do not always cooperate.
It is for this reason that we are beginning to see a gradual change in how development finance is structured. Rather than treating construction and exit funding as entirely separate conversations, some lenders are now looking more closely at how funding behaves across a scheme’s life cycle.
In practical terms, this can mean development facilities that transition naturally into the exit phase once practical completion is achieved, with pricing adjustment to reflect the lower risk profile of a completed scheme. Borrowers may also benefit from greater flexibility around the sales period, allowing units to be sold in line with market demand rather than under pressure from a short refinancing deadline.
Importantly, this approach is not about pushing higher leverage
or loosening underwriting standards. Far from it: it reflects a growing recognition that funding structures need to align more closely with how developers operate in practice.
Residential development certainly remains viable, but the market is far less forgiving of timing assumptions than it once was. Financial risk does not disappear once the build phase concludes. In many cases, it simply moves further along as developers manage sales activity and refinancing options.
At Alternative Bridging Corporation, for example, we have been looking closely at how acquisition finance, construction funding and exit lending interact across the life cycle of a scheme. As a result, we have recently reshaped our development finance proposition to create an integrated funding structure that supports a project from construction through to the sales period without requiring a separate refinance.
The intention is not to introduce something radically new but to remove unnecessary refinancing points and give brokers greater certainty over how a project will be funded from start to finish. Ultimately, the question today is no longer simply whether funding works at the start of a project. It is whether that funding continues to support the scheme all the way through to the point where the final unit is sold.
Funds ready. Clear credit appetite. Our mandate doesn’t change with the headlines.

For intermediaries only and subject to T&Cs.
• Lending up to £50m
• LTVs up to 75%
• Competitive rates from 0.75%
• Certainty of Finance
• Regulated & Unregulated loans
• Residential, commercial, semi-commercial and land lending
• Complex offshore structures considered
• Loans up to £5m considered
• Competitive commercial and semi-commercial rates
• Purchases up to 75% LTV (70% for remortgages)
• Day-One lending available
• Lending based on Vacant Possession Market Value figure
• Owner-occupied and investment options available
• Heavy Refurbishment and Ground-up Development projects
• Residential-led schemes (Residential aspect min 65%)
• Loan sizes from £1m up to £30m
• Funding up to 65% LTGDV and 85% LTC
• 100% of build costs funded
• Initial loan-to-value up to 70%
Michelle Powell, senior relationship support specialist at Hope Capital Property Finance, has quickly established herself as a standout member of the team since joining the post-completions business in January two years ago. Known for her ability to navigate complex cases, she made an immediate impact and has continued to exceed expectations. Following a team restructuring, Michelle was promoted to her senior role in August—an achievement that reflects both her strong performance and the value she brings to the business
Why was this role right for you?
After building my career in regulated finance, joining Hope Capital Property Finance marked my first step into unregulated bridging. As a portfolio case manager, I reviewed deals across the entire loan book, gaining a deep understanding of borrowers’ needs from completion through to redemption.
When the business restructured and established two dedicated teams—loan support and relations, and resolutions and recoveries—I was well placed to take a senior role in the loan support and relations team. My experience in managing loans across the book and working closely with borrowers meant I understood exactly where focused support could make the greatest difference, and I was ready to take that on.
Looking back at your first few months, what were some of the biggest issues and how did you approach them?
Stepping into the senior role during a period of growth and structural change presented an immediate challenge—maintaining service consistency while we refined our support process. My priority was to be a steady, reliable presence for the team and for our borrowers, making sure every request was handled with the efficiency and
care people expect from Hope Capital Property Finance. A key part of our approach is staying ahead of the curve. Rather than reacting to situations as they arise, the team focuses on proactively monitoring each loan so we can identify anything that needs attention early and work with borrowers on the right path forward. That mindset has made a real difference and the results show it; facilities funded are up 46%—the most significant increase in deal volume we have experienced—yet loans over term have reduced by 49%.
For me, it has always been about going above and beyond for every borrower. From day one, I was focused on making sure every interaction left borrowers feeling genuinely supported and confident in the process. That means being proactive, being available and never leaving a borrower without a clear next step or a solution. Hope Capital Property Finance is known for delivering an exceptional level of service, and I wanted to be someone who embodied that every day, not just meeting expectations but consistently exceeding them. Keeping the borrower’s end goal at the centre of every decision is what I believe contributed most to the progress.
What is one thing you wish more people knew?
There is a common perception that bridging finance is defined by the speed of completion, but the support borrowers receive after that point is equally important to a successful outcome. My team works closely with every borrower throughout the full term of their loan, from managing and releasing refurbishment tranche drawdowns to handling facility increases or arranging extensions and supporting exit strategies.
We are particularly proud of our ability to release refurbishment tranche drawdowns on the same day once all approvals are in place and, in many cases, within 24 hours. For borrowers working to tight project timeframes, that speed is crucial. Whether a borrower needs to draw down funds to keep a refurbishment on track, explore their exit options or extend their term to complete works, the loan support and relations team is there to make sure they have the support and solutions they need at every stage.
What is one golden piece of advice that motivates you?
Stay solution-focused and keep the borrower’s end goal in sight. In bridging finance, challenges arise quickly—and so do solutions when the loan support and relations team is aligned around successful borrower outcomes.
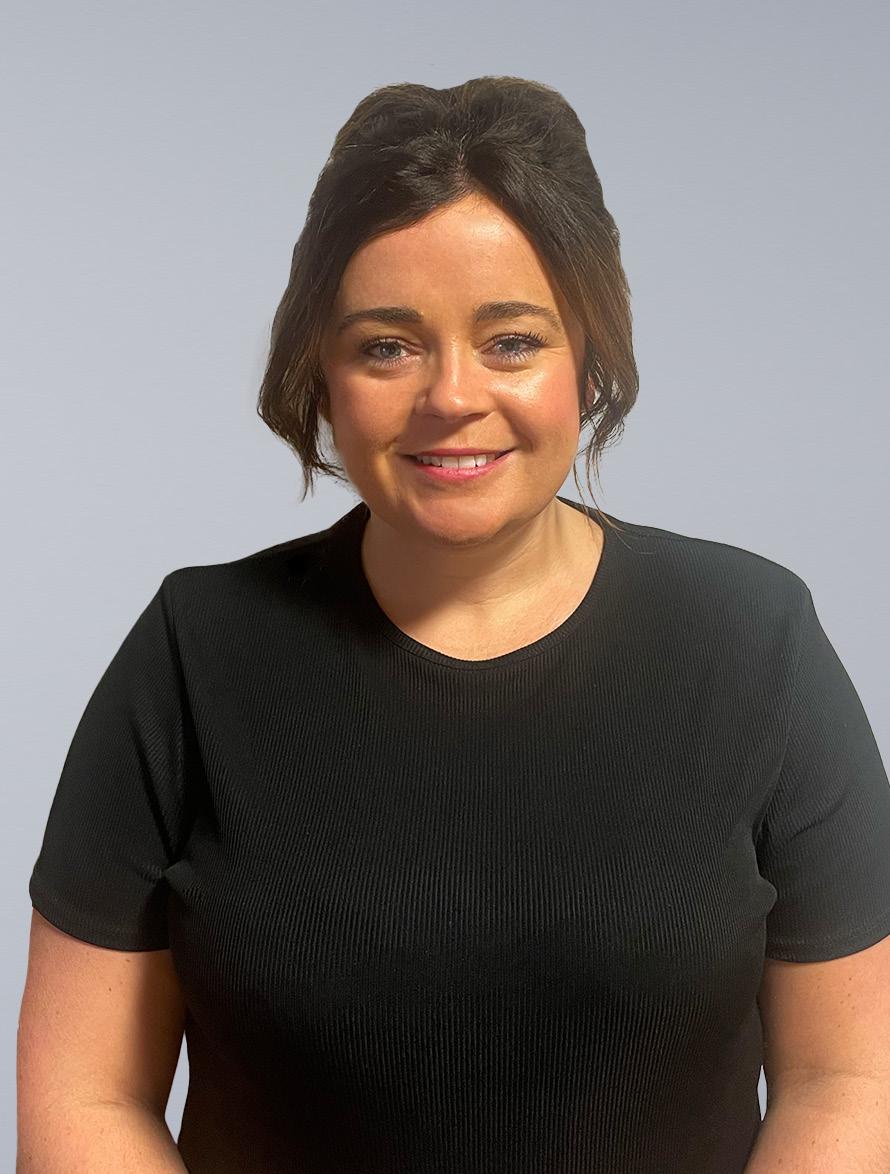
Anderson Wilde & Harris is celebrating 30 years in the surveying business. Rob Hutchins, director; Jamie Chamberlain, director of business development; and BDM Frankie Bromwich talk about the phenomenal growth in specialist finance, friction points, what has changed the surveying profession, and why valuation is a critical safeguard
Dhuha
Al-Zaidi:
Congratulations on your 30th anniversary. Talk us through the defining moments that have helped shape the firm.
Jamie Chamberlain: Thank you. We are looking forward to celebrating with our valued clients and contacts this month after our initial attempts at celebrating it last year were scuppered by the tube strikes last September. I was still in nappies when George Palos started Anderson Wilde & Harris (AWH) from his garden office. AWH has grown significantly since then and has navigated its way through significant challenges, not limited to the 2008 financial crash, Brexit and, most recently, Covid. Out of these, the pandemic probably had the biggest impact on the way we work as a company. The advent of hybrid working has allowed us to significantly increase our coverage as well as attract high-level talent, widen the types of properties we can value and raise our standards across the board. At the heart of what we do is striving to work to the highest standards by clearly communicating detailed, well-researched advice to our clients, who rely on us to help them manage their risk in what can be a very risky industry.
DZ: How has the surveying landscape evolved over the past three decades, and how has the business adapted to stay competitive?
JC: How the surveying landscape has changed is heavily linked to how technology has changed. How you adopted these changes was instrumental to staying competitive because much of surveying— valuation in particular—is reliant on both the quality of the information you can find and the tools you have available to analyse it. For example, when AWH was founded, the World Wide Web was in its infancy, and mobile phones weren’t widely available, so even the simple process of finding comparables would have been much more challenging. In the past couple of years, the advent and rapid growth of AI have very similar echoes to those early days, and will likely cause a similar sea change in the way we all work. We are eager to grasp any benefits available that allow us to improve the quality of the work we deliver to our clients. In the 10 years that I have worked here, the growth in the specialist finance market has been staggering in terms of not only the volume of deals completed but also in the level of sophistication of the lenders in the space. It’s an industry packed with talent and one we are very proud to work in.
DZ: Are there specific sectors within specialist finance— eg. bridging, development or commercial conversions—that you’re targeting more actively?
JC: We are very proud that across our team we have the expertise to
value almost every asset type, apart from agricultural. A big focus of ours is growing our trading valuation team—Rob is a director— that works across healthcare, leisure, hospitality, education and the living sector. Historically, the lending in this sector has been dominated by high-street banks, but a number of specialist lenders have identified a demand for products that enable stabilisation of an asset over a couple of years as it reaches maturity, which then allows the owners to refinance to the high street. Being able to work with these lenders, who are willing to lend off the trading value of the property, has been very rewarding.
DZ: Where do you see the most common friction points for brokers and lenders when it comes to valuations and surveying?
Rob Hutchins: In our experience, the quality of the information provided at the instruction stage is fundamental to enabling the valuer to properly form and formalise their opinion of value. Being organised from the outset is critical. This includes issuing a clear instruction letter, confirming the required basis (or bases) of value, verifying the property address, arranging access details and providing all supporting documentation necessary for the valuation, such as accounts, lease documentation, floor plans, business plans and development cost information where relevant. Where these elements are incomplete or inaccurate, delays are often unavoidable and can impact reporting timescales. At AWH, we firmly believe that transparent communication and proactive updates throughout the process deliver the best outcomes for all parties—brokers, lenders, borrowers and valuers alike.
DZ: Communication is an ongoing industry concern. How are you addressing this?
Frankie Bromwich: A key aspect of my role as a BDM is managing relationships with brokers and lenders while ensuring communication remains clear, efficient and effective throughout the process. I prioritise building strong, professional relationships with all stakeholders, including clients, brokers, lenders and solicitors, to ensure that each deal progresses efficiently from start to finish, and that the valuation is completed to the highest standard within the agreed time frame.
I’m a big believer that clear and consistent communication during the valuation process enables any challenges to be addressed promptly and effectively, helping to ensure a positive outcome for all parties involved. Echoing Rob, communication is key. I place significant value on speaking directly with brokers and lenders, whether over the phone or in person, providing regular updates and working collaboratively to manage expectations and maintain transparency throughout the valuation process.
DZ: What still frustrates you about how surveying is perceived within the finance market? In turn, are you adapting your strategies to combat this?
at AWH, our valuers specialise in specific asset classes, providing lenders and brokers with confidence and clarity when instructing us on a particular deal. This specialist expertise ensures that each valuation is handled by professionals with a deep understanding of the relevant market sector.
RH: Valuation is often viewed simply as a procedural step within a transaction, bringing with it cost and potential time pressures. However, without obtaining independent professional advice, a lender exposes itself to significant and potentially unlimited risk. Instructing a qualified chartered surveyor is a fundamental riskmitigation measure, ensuring that lending decisions are supported by informed, evidence-based analysis. Our role is to provide clear, professional and objective advice, enabling lenders to make confident and properly considered decisions. When understood in that context, valuation is not an administrative hurdle but a critical safeguard within the lending process.
DZ: What opportunities do you see in working more closely with specialist lenders and brokers this year?
JC: The market this year will likely remain quite slow. Therefore, working with good lenders and brokers who truly understand the market they are in as well as the needs of their clients should lead to a greater chance of us them writing good business. We never want to stand in the way of a good deal and, by working closely with our lending and broking partners, we are able to truly understand the deal from both sides. With the market being slow, we are also seeing a number of borrowers and lenders pivot their strategy to get the returns they require. With our breadth of expertise across the property market, we are well placed to work with them to diligently assess the risks and upsides of any new opportunities.
FB: Working closely alongside specialist lenders and brokers is always a positive and significant advantage for us as it allows us to gain a full understanding of each transaction and ensures the deal is being managed with the highest level of expertise. Equally,
JC: I wouldn’t say we ever have or are doing anything particularly groundbreaking. We understand the amount of work that goes into getting a deal to the valuation stage, and how heartbreaking it can be when the numbers don’t come in where everyone expects. Thankfully, it feels like that has been happening a bit less frequently in the last half a year or so. But the team and I are always happy to have a call to discuss a case you may have, and we will assist where we can.
FB: At AWH, we prioritise clear communication and building good, longlasting relationships with all our brokers and lenders across the industry. As Jamie mentioned, it can be both frustrating and disappointing when the numbers don’t come in as expected. However, it always helps when a good relationship is established as you can have an open discussion about the valuation process with the aim of ensuring that both parties can reach a clear and mutual understanding of the outcome.
Additionally, last year, I set up a female networking group called SIP (sisters in property), alongside Bianca Howl. SIP is a network created to bring together successful women in the property industry at all ages and any stage of their career.
Last November, we partnered with Bridging & Commercial. Through promoting SIP events in this magazine, we hope to encourage more female brokers and lenders to attend our events and feel supported within the industry. This April, we are hosting a breakfast event in collaboration with Bridging & Commercial and hope to see women in the property finance industry attend and network in a friendly, safe space.
We are so grateful for the opportunity to work with supportive companies and hope this partnership will encourage more female lenders and brokers to attend future events and become a part of a supportive community. It always makes my day when people I work
“Instructing a qualified chartered surveyor is a fundamental riskmitigation measure, ensuring that lending decisions are supported by informed, evidence-based analysis”
closely with attend SIP events.
JC: As mentioned earlier, we will be focusing heavily on our trading valuation team and growing our market share in this sector. Across the rest of the team, we are constantly reviewing our processes and making the most of the technology and data available to us. This should lead to an improvement in quality and turnaround times too. Beyond our valuation team, we are looking to grow our neighbourly matters team, focusing on daylight sunlight, rights of light and party wall work.
If we were having this conversation again in 12 months’ time, what would you hope to have achieved—both personally and professionally?
JC: From a personal point of view, I had a big year last year—getting married. So, for me, I’m happy to have a quieter year this year, spending some quality time with my wife. But, having cycled the length of Portugal with some great people in the industry a few years ago, I am keen to do some sort of fitness challenge again—any suggestions are very welcome. Professionally? I’d love to get my golf handicap down to single figures.
FB: Personally, I’d love to be more disciplined and establish a better work-life balance, including a good fitness and wellness routine. However, this is not always easy when you work as a BDM and enjoy a drink and socialising. Professionally, I love my role at AWH and am very grateful for the opportunities AWH has given me. As someone who is still relatively new to the industry, I’m keen to maintain and strengthen my existing relationships while expanding my network across the property sector. Alongside this, I’m excited to continue growing SIP through spreading the word, hosting monthly events and doing more amazing collaborations within the industry. If anyone would like to collaborate with SIP in the future, please feel free to get in touch as we are always open to new opportunities.
United Trust Bank has merged its mortgages, BTL and bridging teams and cut admin, which has seen it streamline processes, reduce underwriting requirements and make faster, better decisions for brokers. And more big changes for underwriting are in the wings
At United Trust Bank (UTB), they’ve been working hard on a new formula for bridging and believe they now have the answer on how to turn brain-aches into no-brainer improvements that will really shake things up.
It turns out that medicine has become an unlikely reference point for the specialist lender’s quest to kill off pointless and onerous paperwork. As Gene Clohessy, director of underwriting for bridging and BTL, puts it: “We really looked back at the things that caused everyone pain, from brokers to our own underwriters, and have set about coming up with the treatments that will make everyone feel better – we are cutting out the things that just weren’t adding value.”
Translation? UTB has been on a mission to scrap the administrative fluff and concentrate on what really matters— collaboration with brokers.
BTL and bridging teams into one division with the aim of driving growth and expanding its offerings to customers.
The new division is led by managing director Buster Tolfree, who has been a part of the company for more than a decade. Bridging & Commercial sat down with the leadership team to discuss the rationale for this change.
“We got both businesses to the scale where it made sense to leverage them
He observes that, by bringing those areas together, the team has identified strong opportunities to improve its service and, ultimately, enhance the broker and customer journey.
Becoming a broker’s best friend is no easy feat. It begins with understanding the lender’s distribution system. Andrew Ferguson, commercial director of mortgages, BTL and bridging explains: “For bridging, it’s about having a personal touch. In the unregulated space, it’s also more about certainty of decision and getting access to decision-makers,” he states.
Technology will be a crucial investment priority for the bank this year.
“BEING THE BROKERS’ BEST FRIEND IS ABOUT BEING TRUSTED AND HAVING CONFIDENCE IN DELIVERY. WE WANT BROKERS TO UNDERSTAND WHAT WE DO—CLEARLY ARTICULATED”
This has seen the bank halve its bridging processing and completion times and boost its use of AVMs to more than 50% of bridging cases.
If you’ve followed the news about this bank, you may be aware that UTB has undergone several changes in the past year alone. Most notably, in September 2025, it decided to merge its mortgages,
together,” says Buster. “We’ve kept independence in underwriting where there are real specialisms, but bringing together our operational and servicing teams gives us a much better structure.”
This move was made last autumn and, he explains, has led to a sharp increase in new hires and promotions with the aim of simplifying and accelerating the broker transaction journey.
“When I think about the broker journey and how brokers interacted with us, it was through two completely independent sales teams, two independent portals and two totally different processes. It can be jarring where firms deal with multiple product sets because you want coordination,” says Buster.
“We’re trying to deploy technology where we can automate poor processes or administration. That gets us to a decision quicker, but we also want to retain our people to make the value-added decisions,” he comments.
Buster reiterates that brokers get access to customer-centred service and a team that has a mandate to decide rather than blindly rely on criteria. “Things change during applications; things change in life. How can we work with our brokers and customers to deliver?” he questions.
“Being the brokers’ best friend is about being trusted and having confi-
“THE APPETITE ACROSS THE WHOLE BUSINESS IS TO IMPROVE ALL FOUR PROPOSITIONS IN THE WIDER DIVISION. . . GET THAT RIGHT AND, WITH THE STRENGTH OF OUR BRAND, WE CAN BUILD SOMETHING VERY SPECIAL”
dence in delivery. We want brokers to understand what we do—clearly articulated.”
For Bradley Illman, who was promoted to head of bridging sales at the start of the year, having been a BDM previously and then an underwriter in 2012, it’s all about the pace of delivery. “We’ve got a great reputation, and it’s about enhancing that with the technology coming in the future for our broker partners. Speed in bridging wins every time—it’s not always about the rates,” he explains.
Although many lenders commonly use speed as a main selling point, for Bradley the bank holds a unique position in the market, thanks to its product offerings. “UTB has the full gambit: site acquisition with bridge, development, exit into BTL. We understand the specialist property market and brokers can interact with us on multiple fronts,” he says.
He explains that the team are seeking to ensure products are associated with each other. For example, customers acquiring a property at an auction with a bridging loan as a refurbishment deal will have access to bridge-to-let and heavy refurb products.
Expansion with auction and refurb
Andrew Ferguson joined UTB in December last year as part of the team refresh to deliver its wider goals. Andrew was attracted to the bank’s “strong brand” and “well-respected” values.
His experience spans term products and BTL, and this role will also enable him to apply his know-how to bridging and second-charge propositions. “We’re well regarded on regulated bridging, but non-regulated is where we can improve and see opportunities,” he says.
He adds: “We want to serve a broader range of customers through auction finance and refurb loans, working closely with our BTL team. We just recruited Alex Alexandrou in a key role to drive non-regulated bridging forward, so you’ll see a lot from UTB over the next 6–12 months in BTL and non-regulated bridging.”
With bigger plans to work more closely with intermediaries this year, Andrew explains that brokers are seeking the right blend of technology and invaluable service: “Technology won’t replace UTB’s traditional values around personal interaction. That blend is something the bank has done well. It’s prevalent in the mortgages team, and we’re bringing it to bridging.”
This year, Andrew’s priority is quality. “The appetite across the whole business is to improve all four propositions in the wider division. Whether it’s product, distribution, tech or people—there’s a real appetite to improve. Get that right and, with the strength of our brand, we can build something very special,” he states.
Bradley drew on his experience as an underwriter when he helped to set up the bank’s internal bridging sales team. This, he notes, has shaped his perception of the market and the challenges lenders face.
Yet one key issue stands out, and it’s one almost every broker needs. “Brokers are telling us they have a need for speed. I’ve been in bridging a long time, the Top Gun is often whoever completes quickest gets the deal. Sometimes we’ve fallen away, other lenders have too, but the changes we have made put us right back on top” he shares.
“Other areas of importance are certainty and relationships. We’re not a tick-box lender; we don’t want to say no, but a quick no works because brokers appreciate it. We do want to say yes—being upfront with a quick yes and delivering.”
He’s excited about leading the sales team as it undergoes technological advancements.
“When you’ve been somewhere that’s grown from 40–50 staff to 440, you’re part of it. You care about doing the right thing and being the best in class,” says Buster. “Last year, over 20 people in our division received promotions or career advancement. We care about developing people and succession planning; it’s in our DNA”
Gene Clohessy joined UTB last summer as director of underwriting of bridging and BTL. She shares that she has kept a close eye on the bank from when it was a competitor, and now her focus is on training and transforming the underwriting team.
“My plan is to be market leading, diversifying credit appetite where others aren’t, operational improvements, and training and developing underwriters,” she states.
Closing the gap between experienced and new underwriters is a priority. “. The market’s evolving, so training is key. Tech will come, but I can control credit appetite and team development,” she says.
She sees the biggest opportunities from working more closely with the sales team, with whom she will coordinate to ensure the team and, consequently, brokers, understand risk appetite. “We have a clear risk appetite, so what’s a UTB deal? Sometimes, we competed everywhere. Now we know our sweet spots and have focused our growth plans. As the market evolves, we can quickly change our risk appetite. If we’re seeing deals we aren’t saying yes to, let’s look into that market,” she asserts.
Internally, she shares that the team has been restructured so brokers will be connected with the right person
who is making the decisions. “We’ve restructured who’s running the deal from what point. We’ve removed having to go through an underwriting assistant; now cases go straight to a mandated underwriter so there are fewer questions going back and forth, and it’s the owner and decision maker on the case getting it over the line,” she explains.
This move has already reaped the rewards. “Empowering the team with the right person making decisions at each point has delivered the most monumental improvement. We’ve shaved off the biggest chunk of time. We’ve saved days and weeks, now we’re down to hours and minutes,” she states.
“In six months, we’ve halved underwriting requirements when a deal is first worked. We asked ourselves: why are we asking for that information? Can we obtain it without the customer jumping through hoops? If we can, let’s do it that way. We cut out the things that weren’t adding value.”
Technology will refine UTB’s underwriting approach this year, but it comes down to “need to know versus nice to know”, she says. “I look at technology differently—I look
at what hasn’t gone through. Cases we declined, could we push our appetite more? Price differently? Was it our speed? Not enough AVMs? I use data analysis to strategise and find opportunity.”
She believes that AVMs are important for speed and the getting on board with them quickly will benefit auction purchases and bridging enquiries later on. “It is standard in the market to have contact with the customer prior to loan completion. We moved all of that journey into the UTB app at the turn of the year so, when people apply for a UTB bridging loan now, they’ll do their ID through the app,” she explains.
For customers, this means secure contact through the app rather than phone calls, a move the team view as a modern way of dealing with incoming customer requests. “By investing in technology, we’re able to take advantage of the speed and ease that this offers our customers in the specialised bridging segment of the market, and that’s exactly the kind of opportunity we intend to build on,” she says.
Once the merging of the lending divisions is complete, brokers will be able to submit residential mortgage, BTL
“WE’LL AUTOMATE VANILLA CASES— BROKERS GET A BINDING YES OR NO AT POINT OF SALE. COMPLEX CASES STILL GET SKILLED UNDERWRITERS, BUT IF BROKERS CAN GET QUICKER ANSWERS WITH CONFIDENCE EARLIER, THAT’S POWERFUL”
and bridging proposals through a single portal that is set to go live in the summer.
“It’s about automating admin and empowering humans to add value. We’re making a seven-figure investment in our application portal and we’re taking what works in our flow businesses and applying it where it makes sense for bridging,” shares Buster.
He adds that there’ll be a fully digitised journey, with no paper forms or manual processes. “Brokers can still pick up the phone—that’s very important. Everything will upload through the portal and we’re leveraging something like 27 API integrations in Gene’s area, saving time on manual stuff,” he divulges.
“We’ll automate vanilla cases—brokers get a binding yes or no at point of sale. Complex cases still get skilled underwriters, but if brokers can get quicker answers with confidence earlier, that’s powerful.”
The portal has been gradually improved based on broker feedback on what works and what could be better.
Past approaches that have proved useful have underpinned UTB’s strategy, and Gene says this has helped transition the bank into using more AVMs. “In bridging, 90% of people do some enhancement to the property anyway. AVM is tried and tested across the long term, so why wouldn’t you use it more in bridging?” she questions. “We’ve been smart and it hasn’t happened overnight. We’ve steadily grown it, always reviewing appetite.”
On gauging whether this was the right move, Andrew says: “For lower LTV and lower-geared loans, why wouldn’t you go the route that gets you from application to completion quickest? For higher LTV, larger loans and unusual assets, it’s not appropriate. Any responsible lender identifies where it makes sense and where it doesn’t.”
The leadership team assert that the decision is based entirely on criteria, and whether the due diligence run on a property suggest if the AVM worked or not. Gene reiterates that the opportunities don’t stop at AVMs; but desktop valuations may also be considered in certain cases, but
what is key is judgement.
“We look at confidence levels, loan amounts. If there’s too much risk for AVM but the desktop gives more confidence than full valuation, we’d opt for that. Certain properties always need a full valuation. With UTB’s experience, we know where they work and where they don’t,” she states.
Customer permission, however, is the top priority. “Sometimes, customers choose physical valuation if they’ve done more building and want more leverage. Having that offering is important and we always ask,” Bradley explains
“Most times, it’s accepted; that’s why numbers increased. But sometimes, customers need a physical valuation to negotiate the purchase price. Heavy refurb always gets a physical, it gives them power depending on how quickly they want to move.”
Buster points out that, where automated models fail in certain cases, the data allows the bank to compare with when it opts for a full valuation. “We do a lot of bridging and mortgage lending, and the learnings from property we see weekly, monthly and yearly are massive. That informs future choices; where we see opportunities or increasing risk where we might want to change something,” he states.
“Capturing data points is key—otherwise, you’re just doing what another lender does.”
The next few months will prove significant for the bank and its internal shift in processes and technological advancements. Along with the upcoming broker portal launch, Buster reports that the bank’s underwriting department will undergo change.
“The biggest change is what underwriters use. We have a new workflow management system coming as part of the portal, which will help with third-party referencing for KYC, AML and fraud checks,” he says.
“We’ll shout about the snazzy broker portal, but 70% of the upside is internal. Brokers will see it in quicker service, better conversion, point-of-sale automated dips. That’s based on all the internal back-end improvements.”
Andrew highlights that the merger of the BTL and bridging divisions has positioned the bank for a productive and collaborative journey ahead. “The external sales team is now covering BTL and bridging together; we see those as natural companions across those two products. You will see UTB over the coming months really building its own identity into BTL as well. So, while bridging has got massive focus simultaneously, we see that as just a synergy that works well across the business,” he expresses.
Gene says that her underwriting division will work on further operational development opportunities for training between the bridging underwriters on BTL, and vice versa. “Use the time to challenge ourselves, what does and doesn’t work on both sides of the coin?” she considers.
“We’ve taken weeks and months away. Now we’re looking at days and hours. We talk constantly—feedback’s important. When guys are on the road or what I’m hearing
from teams, we provide feedback and align.”
Humility is intrinsic. “It’d be arrogant to say we’ll get everything right the first time. We won’t. That’s why relationships matter, and we want feedback from brokers, customers and colleagues,” says Buster. “How can we continue moving the bar up? Low-hanging fruit exists, but it’s about continuing every quarter, every year. This market is massively entrepreneurial and competitive. If you don’t move forward, you get left behind.”
In a nutshell
As UTB looks ahead, the merged lending teams are already delivering, the new broker portal is due to be launched this summer with automated valuations and point-of-sale decision built-ins, and underwriting requirements have already been halved.
The goal is simple: grow non-regulated bridging to better complement the existing regulated suite, offer a genuine multi-product platform and keep humans on the phone for the complex stuff. But the team’s real bet is on humility—accepting they won’t get it perfect and listening to brokers to keep improving.
New tech, restructured teams and a reminder that speed matters—as does picking up the phone.
doesn’t either.
Scan to get on with it.
Bridging finance for when timing matters. Lending across England, Wales and Scotland. Including the Highlands and Islands.
Our ground-up product - a classic reimagined
MIPIM is where the property world descends on Cannes— part conference, part networking marathon, part… rosé-fuelled chaos.
From beachfront meetings to back-to-back handshakes, it’s the place where conversations turn into deals (sometimes quicker than you can say “another round”).
We caught up with a few lenders to hear how they really experienced MIPIM this year
Relationship manager at Avamore Capital
Head of sales and business development at Magnet Capital
The Boules tournament was probably the standout event, although I might be slightly biased as our team came second. It struck the perfect balance between networking and some friendly (and at times fierce) competition.
That said, some of the most productive moments actually came later in the evening at Café Roma. After a full day of meetings, it became a natural meeting point where you would inevitably bump into people you already knew, while also being introduced to plenty of new faces. It created a relaxed environment where conversations flowed easily, and a bit of liquid courage certainly does not hurt when it comes to networking.
It is very hard to choose. Obviously, Avamore’s event on Monday was the highlight of everyone’s week. However, I also enjoyed playing boules with Gunnercooke, sipping cocktails on the beach with SC&W and DJ-ing in the club with Steve Williams at the Redgate event. If I had to choose one, though, it would be an intimate lunch at Le Sud in Hôtel Martinez on Thursday with our key broker partners. With this small group, set away from the crowds on La Croisette, we could celebrate completions and build on relationships over a fabulous meal.
Sales director for structured property finance at United Trust Bank
The joint UTB, James Andrews International & Bridge Insurance 30th anniversary drinks reception was fantastic. A packed event with about 400 of the biggest players in UK real estate catching up, renewing longheld relationships and sharing insight and opinions on the future for the industry. A close second was the UTB-Iron Bridge Finance commercial broker lunch exclusively for invited introducers at Vega Plage in the sunshine. Another excellent opportunity to talk to key people on the front line of dealmaking, listening to their take on the market and what they need from lenders right now.
Senior BDM at Bluecroft Finance
The standout event for us was the drinks and networking sessions at the venue. These gatherings provided a fantastic opportunity to engage face-to-face with a wide range of brokers, both familiar contacts and new introductions. The informal yet productive atmosphere allowed us to have meaningful discussions about Bluecroft’s current position, the wider market landscape, and the challenges and requirements brokers are encountering. These insights are invaluable and will help shape and refine our product offering over the next year, ensuring we continue to deliver solutions that align with the evolving needs of our partners.
Chief commercial officer at Assetz Capital
Gunnercooke’s annual Boules Fight is one of the most popular events in the Cannes calendar. It’s a great way to catch up with developers, brokers and finance partners in a relaxed environment…but competitive!
Relationship manager at Avamore Capital
Head of sales and business development at Magnet Capital
Not direct deals on the spot, but that was never really the intention. We approached MIPIM with a longer-term view, focusing on building relationships and expanding our network.
What it did provide was a huge number of introductions. One of the most common phrases you hear is, “You should meet so-and-so, let me introduce you.” That ripple effect of connections is where the real value lies. Those conversations often lead to a wider network and, ultimately, future opportunities.
JAMES BROCKLEBANK Senior BDM at Bluecroft Finance
Yes. Just by catching up with brokers, updating them on our criteria and talking about where Avamore are winning business, the conversations unlocked opportunities to help with new enquiries and keep us fresh in mind. The best meetings were actually ones that I didn’t plan or expect to have, just by networking on the streets and being introduced to new clients or bumping into people that I haven’t seen or spoken to for years. Hopefully, these spontaneous encounters will lead to us working together.
Sales director for structured property finance at United Trust Bank
Although I came away with three very strong deals to progress, MIPIM is generally more future looking. If you go with the sole intention of securing deals, you can come away disappointed and, in my view, you probably haven’t made the most of your time there. What was great this year was UTB Structured Finance and Property Development divisions really joining forces as UTB’s real estate finance lending team, often going to the same meetings and fringe events together.
As is often the case with major industry events like MIPIM, the true impact will be realised over the coming months and years, as new relationships mature and existing ones are strengthened. However, even in the immediate term, the outcomes have been very encouraging — we already have two brand-new deals on our desk directly stemming from conversations at MIPIM. This early traction highlights the tangible commercial value of the event and validates our ongoing commitment to being present and visible within the market.
ANDREW FRASER
Chief commercial officer at Assetz Capital
You can measure MIPIM by the number of deal opportunities, and it more than pays for itself. What excites us about MIPIM is connecting people from our massive whole of UK network, last year we were able to connect a developer contact with a large contractor, a developer with a land owner wanting to consider a joint venture, and a finance partner wanting to provide mezzanine into one of our developer transactions to make it work. These are just three examples of our footprint and network impact when out there
We lend based on the open market value rather than just the purchase price. That means your client could access 100% of the Purchase Price or even more, depending on the deal . We do not limit the loan to 90% of purchase price!
Rates starting from 0.69% at 75% LTV
Lending across England, Wales, and Scotland
Loan amounts from £37,500 to £1 ,000,000
Terms from 3–12 months (up to 18 months by referral)
Security types: Residential , Land with Residential planning, Commercial and Semi-
Commercial considered case-by-case
Title insurance with sole representative available to help speed up transactions
Dual representation available to save time and costs
Fast application and approval process
Email : enquiries@ascotmortgages.co.uk
Web: www.ascotbridgingfinance.co.uk
Telephone: 01925 467 170
Relationship manager at Avamore Capital
Definitely, although I’m not sure my social battery can hack the whole five days again! It was a very productive week, and great to condense meetings with brokers in a more relaxed environment. I certainly feel that our discussions will continue and result in doing more deals. It was also nice to have members of Avamore’s credit team out there too, who now have more of an appreciation of how hard it is to work in sales!
Head of sales and business development at Magnet Capital
Absolutely. Magnet Capital will be back in 2027. There are a few places where an entire town essentially becomes one giant networking event. Everywhere you go, every person you pass could be someone who shares knowledge, expertise or becomes a potential business connection. The best way I would describe it is like London on a busy Thursday evening, multiplied by a thousand, but everyone is in the same industry and there for the same reason.
Senior BDM at Bluecroft Finance
Absolutely. The chance to meet such a diverse mix of people—long-standing contacts and fresh faces alike—made the event more than worth the investment. MIPIM offers something unique: the ability to connect with so many industry professionals in a short time, away from the usual pressures of daily work. The informal environment allows for deeper, more personal relationship-building, which is often where the most valuable opportunities begin. It’s an experience that simply can’t be replicated through emails or standard meetings.
ANDREW FRASER
Chief commercial officer at Assetz Capital
Sales director for structured property finance at United Trust Bank
Yes absolutely. This was my eighth MIPIM running, and it is still the best event for meeting key industry contacts, old and new. I can meet or catch up with half a dozen people in a day at MIPIM that it may otherwise have taken weeks or months to schedule in the UK, purely because we all have very busy diaries. Also, you get an immediate and very honest snapshot of the market’s mood, which you just don’t get from surveys or price indices.
Property has and always will be a relationship-driven contact sport. MIPIM, property, and property relationships must be viewed as a long-term commitment, and we will be back year on year.
Head of sales and business development at Magnet Capital
One thing that really stood out to me is how collaborative our industry is. While there is healthy competition, people are always willing to share insights, make introductions and help where they can. That competition ultimately pushes everyone to raise their standards.
On a personal level, it also gave me a deeper appreciation for the different layers within development funding. It is one thing to talk about your own offering but having a broader understanding of how the entire capital stack works is incredibly valuable.
Relationship manager at Avamore Capital
There is a lot of positivity around the year ahead and a sentiment that 2026/27 will be better than previous years, especially in the development space, which we specialise in. It was also apparent that the industry is becoming increasingly saturated and homogenous in terms of lenders’ products, so speed, service and unique solutions are ultimately the determining factors that will win business.
JAMES BROCKLEBANK Senior BDM at Bluecroft Finance
One clear takeaway was the remarkable level of optimism that continues to define our industry. Despite recent challenges and broader global uncertainties, the general sentiment among delegates was resoundingly positive. There’s a shared belief in the enduring fundamentals of our market and its capacity to adapt and thrive. That sense of confidence and forward momentum is both encouraging and energising—and it reinforces why forums like MIPIM are so important for maintaining perspective and collective ambition.
Chief commercial officer at Assetz Capital
Make sure to put your Outlook calendar invites as GMT+1 to ensure your diary doesn’t implode with the French time zone. Top tip that!
Sales director for structured property finance at United Trust Bank
The overarching feeling was that almost everyone started the year with optimism that the real estate market was picking up pace and confidence. Then the war started in Iran and the handbrake was pulled. However, uncertainty opens opportunities and that creates markets. UTB’s diversified Real Estate Finance proposition, backed by dependable deposit funding, puts us in a great position for the coming months
Wednesday April 29th
Venue: Assmann Showroom
Time: 8:30am hosted by Spacemann in Farringdon
Bridging & Commercial Magazine has teamed up with sip to bring a little breakfast energy to your morning meet-ups.
Think great coffee, even better conversations, and a side of fresh opportunities—because the best connections don’t just happen over emails…they happen over brunch
Wednesday May 6th
Sip is bringing back another book club night at Yuu Kitchen in London—and this time, they’re diving into The Great Alone by Kristin Hannah.
Expect thought-provoking conversation, incredible food, and a room full of people who love a good story as much as a good atmosphere.
.
Thursday May 7th
Venue: Dentons Law Firm in London
Time: 8:30am
Stacey Baxter, lending director for real estate finance at Downing and Dentons Law is teaming up to bring a little zen to networking—with an exclusive yoga event designed to reset both mind and inbox.
Expect calm energy, meaningful conversations, and a fresh take on how we connect in the industry.
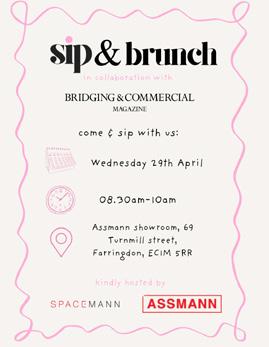
Scan the Whatsapp QR code to keep up with any new events on the rise
In February, Jamie Jolly joined Secure Trust Bank as head of bridging, bringing 25 years of expertise in the field with him. His role includes leading and growing the new bridging division. He discusses the priorities when growing a department and engaging with brokers
What attracted you to this opportunity?
Secure Trust Bank has a strong heritage and a reputation for reliability—that really stood out. It’s a well-capitalised bank with real stability, which gives our team a solid platform on which to build something meaningful. The chance to establish a dedicated bridging division from the ground up was compelling for the bank; we can shape a proposition and culture in a way that genuinely reflects the way we think bridging should be done.
What’s the first thing you prioritise when expanding a department?
People—every time. Experience is one thing we can’t teach and it’s probably the most valuable thing we have. We’re not looking to build a huge team quickly. Rather, we’re focused on bringing in experienced individuals who understand the market, the introducers and the borrowers, and know how bridging works. If we get the people right, everything else follows. You’ve spoken about building a team with the “agility and culture of a dedicated bridging business”. What does that culture look like? It’s about always acting and operating like a bridging lender. Bridging can be different to other forms of lending—deals are nuanced, complex and time sensitive. Therefore, being responsive, accountable and accessible is key. It means strong, open lines of communication and a culture where people pick up the phone rather than hide behind processes. We need the efficiency of good systems, but we also need human judgement and dialogue.
If you could only watch one movie for the rest of your life, what would it be and why?
How will you work with brokers to adapt and refine the bank’s bridging proposition?
Partnerships are essential as brokers are at the heart of this market. It’s important we listen and evolve, based on real-world feedback. We’re developing a broker hub that will make it easier to do business with us but we’re equally focused on regular engagement—meetings, education sessions and open conversations. The balance between digital efficiency and relationship-led lending is where we can really differentiate ourselves.
What makes bridging finance such a compelling space to operate in right now?
Bridging supports real momentum in property, helping developers and investors move quickly, solve short-term funding needs and unlock value. The variety of deals and the problem-solving nature of the work make it engaging for me and that is why I’ve spent over 25 years in it.
Where do you see the biggest opportunities and risks?
Opportunity comes from being clear about where we operate and doing it well. We focus on land and development exit lending and there’s strong demand for those when deals are structured properly. The risk is when lenders try to be everything to everyone or prioritise volume over discipline. Bridging works best when you stay within your area of expertise and maintain strong underwriting standards.
In your view, what frustrates brokers most about bridging lenders? How can that be improved?
Communication gaps and moving goalposts. Brokers want clarity and certainty. If a lender says they’ll do something, they expect that to be honoured, subject to the agreed fundamentals. One thing we’re keen on is doing more of the heavy-lifting, robust underwriting upfront so there are fewer surprises later on and, when issues do arise, direct conversations solve far more than long email chains. This is where quality introducers can add huge value through their attention and commitment to thorough enquiry details that are shared early in the process. Providing as much information as possible on day one is key.
Rocky. I’ve always loved it. The story of missed chances, grit and making the most of an opportunity really resonates. What people sometimes forget is he doesn’t even win in the first film—but it’s still inspiring. It’s simple, believable and brilliantly made.
What’s the most spontaneous thing you’ve ever done?
After a few too many margaritas on a night out many years ago, I managed to buy an expensive watch online. I only found out when it turned up a few days later.
What’s one thing your family tease you about?
My hair—or rather the lack of it. I get plenty of jokes and regular suggestions that I should book a trip to Turkey.
What will success look like for you 12 months from now?
A trusted team of bridging finance experts who brokers know and want to work with. Strong conversion rates, repeat business and a reputation for delivering consistently.