Editor-in-chief
Beth
Magazine
Creative
Sub
Contributors
Ben Allen, Connor Ross, Wendy Twaits, Pankaj Thukral, Matt Mawdesley, Mahesh Vekaria, Dan Narwal, Josh Hawker, Jonathan Samuels, Matt Smith, Jemma Hayes, Mia House
Photography Connie Burke, Sean Gannon
Sales and marketing
Beth Fisher beth@medianett.co.uk
Ellen Townsend ellen@medianett.co.uk
Special
Printing
To read about our commitment to the environment and sustainable print publishing, please visit https://bridgingandcommercial.co.uk/page_magazine.
Welcome to the Jan/Feb 2026 Power List issue. As specialist lending enters another year of recalibration, this edition focuses on where real influence sits in today’s market—and why judgement, not just capital, is once again king.
That theme runs through this year’s Power List [p54], which turns its attention to underwriting. Thirty leading underwriters feature for being the individuals brokers rely on when certainty matters, and complexity is the norm. In a market that increasingly rewards disciplined flexibility, these are the people who can balance risk with realism and keep deals moving when others stall. Competition to make the list was intense, and rightly so.
The renewed focus on judgement is also evident in the lenders entering the market. New arrivals are coming with confidence rather than caution. We speak to the team behind Pallas Capital [p28], which launched in the UK in January, backed by the wider Pallas Group’s £1.8bn loan book. Founded in Sydney, the group’s expansion into our borders signals continued overseas appetite for specialist real estate lending. We also meet Kozo [p78], another new bridging and development lender whose proposition is rooted in mindset, aiming to address what borrowers and brokers feel the market has been missing. As competition increases, language in lending matters more than ever. Few words are used more loosely than “USP”. Morpheus Lending founder Matt Mawdesley cuts through the noise to examine what genuinely differentiates a high-quality specialist lender, arguing that execution and consistency trump headline claims every time.
The same tension between systems and judgement is explored by Allica Bank’s Mahesh Vekaria [p36]. He examines how underwriters can help close the SME lending gap by placing human judgement alongside data. As automation accelerates, his case for decision-making confidence as a growth enabler is both timely and compelling. When judgement is removed from the process, deals often fall out of the mainstream altogether. Together’s Dan Narwal looks at what happens when traditional lenders step back from large or complex loans, and outlines how brokers can continue to deliver outcomes when conventional routes are no longer available [p42].
Despite these pressures, growth remains firmly on the agenda within the market. Octane Capital outlines plans to double its loan book to £1bn this year while expanding its team, reflecting a broader theme of selective but confident expansion across the sector [p86]. People, ultimately, remain the constant. Our magazine manager Dhuha hosts a broker roundtable on how new entrants can succeed in specialist finance, offering candid insight into the realities of building a career in brokering [p100]. In our backstory, Mia House, recently appointed originations director at Maslow Capital, shares her perspective on leadership, energy, and the influences that shape her approach [p117].
To help readers navigate what lies ahead, we’ve also included our 2026 events guide: a practical, rip-out-and-pin-up overview of upcoming dates shaping the year [p114].
Taken together, this issue reflects a market that is maturing rather than retreating. With international capital still engaged, new lenders entering with intent, and smart underwriting at the centre of decision-making, the conditions for sustainable lending remain firmly in place.
“As
Optimism, the broker way
GB Bank sets eyes on a glamorous target / Getting over a USP
Pallas Capital opens its doors across the world
Underwriters are the backbone of the UK economy
How to secure larger loans in 2026 / Bridging offers hope
Which underwriters are leading in the game?
Watch out for these inevitable circumstances Is there room for new broker blood? A list of events to look forward to this year
Last year gave the specialist finance industry plenty to talk about, with bridging firmly in the mainstream rather than a last resort. Meanwhile, many lenders and brokers entered the market, their sights set on a multiplicity of targets—not to mention the aftermath of the Budgets. We speak to specialist finance brokers about where they feel positive, opportunities on the horizon and what to watch out for
Ben Allen
Business development manager at E18 Specialist Property Finance
I’m optimistic about the depth and maturity of the specialist lending market. Over the last couple of years, lenders have become far more pragmatic and underwriting is still disciplined. There’s also a much better understanding of real-world borrower scenarios. We’re seeing lenders willing to look beyond rigid templates and focus on exit strength, asset quality and borrower experience, which are exactly where specialist finance adds value. For brokers and clients who understand how to structure deals properly, that creates genuine opportunity rather than constraint.
Connor Ross Head of specialist finance at Capital Finance/ Founder of BridgeCross Finance
With the highly anticipated Autumn Budget finally done, we now know what we are working with in the property industry. Unfortunately, longterm landlords who have held a portfolio in their personal names have been hit, with tax on property income increasing. While this is upsetting overall, it does suggest that some of these landlords will be looking to exit the market, which of course creates opportunities for others to enter it. I am optimistic that a new wave of investors will come in and I believe lenders will compete a lot for their business, reducing the cost of borrowing.
Wendy Twaits Sales director at Synergy Commercial Finance
Heading into 2026, my biggest source of optimism for the commercial finance market is the stabilisation and anticipated decline in interest rates. With central banks expected to continue easing monetary policy, borrowing costs should become more predictable and affordable. This is critical for businesses, as improved cash-flow positions encourage investment, expansion and refinancing activity. For brokers, this renews momentum in deal flow as clients re-engage with funding conversations that may have been delayed during higher-rate cycles. Alongside this, increases in lending volumes are forecast across the market. UK bank-to-business lending is expected to grow by around 5.6% net in 2026, while commercial real-estate lending could rise by as much as 30–35%. The return of traditional lenders, combined with the continued growth of alternative funders, is significantly expanding the pool of available capital. This competitive lending environment benefits brokers, who are well positioned to match clients with the most suitable and flexible funding solutions.
Wendy Twaits Sales director at Synergy Commercial Finance
We are seeing a growing appetite for commercial and semi-commercial property, particularly assets that offer mixed-use or conversion potential. High-yielding investments such as HMOs and MUFBs continue to attract strong interest, driven by persistent demand for rental accommodation and investors seeking a resilient income in a changing market. More lenders are now expanding into this space so clients should see an increase in the offers available in what has in the past been a much narrower field of appetite.
Ben Allen
Business development manager at E18 Specialist Property
Finance
One emerging indicator is that clients are using specialist finance more strategically rather than as a last resort. We’re seeing experienced landlords and developers proactively using bridging and second charges to move quickly on opportunities, particularly around auctions, planning-led acquisitions and refinancing timelines. Speed and certainty are becoming just as important as headline rate.
Planning-related opportunities continue to be a key area of focus. Clients acquiring land or property with planning upside or bridging through planning risk are finding strong lender interest where the strategy is clearly defined. Even in more cautious markets, lenders are backing projects that demonstrate a clear route to value creation.
Connor Ross Head of specialist finance at Capital Finance/ Founder of BridgeCross Finance
Personally, I am seeing savvy investors looking past traditional BTL and focusing their attention on more commercial assets. On the residential side, I am seeing a lot more attention to higher-yielding and larger sui generis HMOs, as well as some clients going one further than this and focusing on commercial use-class property. I believe we will see more landlords with mixed portfolios than before, but this will then in turn create opportunity in the residential space. It’s a never-ending circle, which goes to show that property will long remain a great industry to be in.
Ben Allen Business development manager at E18 Specialist Property Finance
The biggest shift for us is a deeper focus on second charges and structured capital solutions, alongside bridging. Clients are increasingly looking to work smarter with existing equity rather than refinance everything and that plays directly into our strengths as a specialist brokerage. Operationally, we’re investing heavily in process and lender relationships so we can move faster while maintaining clarity for introducers and clients. In a market where speed, certainty and experience matter more than ever, that combination will be key.
Connor Ross Head of specialist finance at Capital Finance/ Founder of BridgeCross Finance
BridgeCross Finance is positioned as a specialist finance brokerage and already has a focus on bridging, development and commercial as well as complex BTL so, in terms of changes, we just plan to do more. In that respect, we have a hire in the pipeline and we plan to continue growing. We aim to employ more brokers and admin staff over the next 12 months: watch this space.
Wendy Twaits Sales director at Synergy Commercial Finance
A change that we are constantly planning for is in the competitive landscape. As costs rise, all brokers are looking for the best value for money in the services they receive and new ways to differentiate themselves from their competition. In turn, their customers now expect greater transparency, expertise and reassurance that the brokers they work with truly understand their needs and the market. In response, we have recently introduced the Synergy Standard across our network. This sets out the clear expectations, processes and ongoing support we provide to ensure our brokers consistently operate to the highest professional and compliance standards.
Alternative lenders are becoming the first choice for brokers, particularly when complicated deals over £2m are sought—which led this bank to set an ambitious target
Words by PANKAJ THUKRAL
Photography by CONNIE BURKE Chief lending officer at GB Bank
ntermediaries are getting more proactive, working more closely with lenders than before, as clients become more sophisticated and have what can be complex requirements. And this is proving positive for finance companies.
Last year was a real turning point for GB Bank, thanks to the strength of our intermediary partnerships, alongside growing market demand. In our financial year ending September 2025, lending surged by an incredible 439%. With this momentum, we now have our sights firmly set on reaching £1bn in lending.
In our latest annual report and accounts, we confirmed our first full year of post-tax profitability and balance sheet growth. Total assets rose from £1.2bn to £2.6bn. Core lending activity grew from £86m to £464m, and customer deposits increased by £1.2bn to over £2.3bn.
The growth in lending has been driven by the increasing prevalence of complex bridging and BTL loans. These are loans where intermediaries need flexibility, speed and certainty—where standard solutions can often fall short. In response to this demand, we have built a reputation for regularly completing large,
time-sensitive loans that require a bespoke, hands-on approach.
A couple of loans spring to mind. First is a £6.15m bridging loan delivered in Uxbridge, where the borrower needed to refinance a commercial asset ahead of securing development funding. It involved a multi-layered offshore structure and closed within nine weeks of the first enquiry. Another was a £3.5m refinance structured for a Monaco-based expat, secured on a prime London asset in Bayswater. These cases are bespoke but share a common thread; they involve complex company structures or non-standard income streams, which are being seen more frequently by intermediaries. Consequently, we’re seeing intermediaries take on a more proactive role as their clients grow in sophistication and, with this, a truly collaborative partnership between an intermediary and a lender is becoming more important. This means alternative lenders are emerging as a first choice for many.
Many intermediaries have told us they are submitting more applications to alternative lenders, with some reporting that more approaches are being made to non-traditional providers, particularly on deals above £2m. These are deals where swift decision-making is the top priority for their clients, but where size and complexity mean that they can get caught up in lengthy approval processes at other lenders.
Flexibility, speed and collaboration aren’t just about added value any more—they’re baseline expectations. Intermediaries recognise this and are actively building relationships with lenders that will meet those expectations consistently. At GB Bank, this has been a crucial part of our success and will continue to be so as we aim for £1bn in lending.
As the market continues to evolve, I expect to see more borrowers and intermediaries recognise how specialist lenders can support larger, more complex transactions, and this will only increase opportunities for lenders like GB Bank.
Of course, reaching milestones requires more than good lending decisions—it needs a strong operational foundation behind the scenes. Over the past year, we’ve made deliberate moves to strengthen our internal structure and processes. Speed of completion, clear communication, quality and consistency at every stage of the process are all crucial to the overall experience of intermediaries and their clients.
Alongside recruiting experienced people in our team, we have invested in the tools and platforms brokers use to engage with us, launching an intermediary-focused website designed from
“Flexibility, speed and collaboration aren’t just about added value any more—they’re baseline expectations”
“Working towards £1bn in lendingensuringmeans our people, our processes and our evolveproposition in line with what intermediaries need from us”
the ground up. The new site was developed in direct response to intermediary feedback and includes an improved lending enquiry form, a smart chatbot for initial triage and clearer visibility of buy-to-let and bridging options; it also highlights the customer segments that we serve, including foreign nationals, complex structures, limited companies and semi-commercial properties.
Working towards £1bn in lending means ensuring our people, our processes and our proposition evolve in line with what intermediaries need from us. Whether that’s through leadership, technology or simply the way we communicate, our intention is to scale without losing responsiveness and pragmatism.
There’s still work to do, but the direction is clear. Intermediaries are at the heart of our growth story, and we remain committed to supporting them with the service, structure and speed that specialist property finance demands.
Lenders may boast about having a USP—but do such claims genuinely boost business? A different approach helped Morpheus Lending secure a £110m funding line within months of making its first loan
Words by MATT MAWDESLEY Founder of Morpheus Lending
Everyone says they have a USP, right...? Are you calling bullsh*t on this?
When a market is crowded, full of cheap capital and has well-established players, it’s difficult to claim you have a USP—however much as people want to say they have one.
Bridging has gained fame and acclaim and sometimes disdain in recent history. So that leaves: what makes a brilliant specialist lender?
Before we go into that, who the hell am I?
I am Matt, founder and CEO of a newly established bridging company. Your stereotypical northerner with grandparents as miners with a can-do attitude and all that, here to reshape the world… just kidding. We are here to be sensible, trustworthy and leverage the best tech available to make everyone’s lives easier—and that’s it really.
After doing our first loan in May last year, we have built a quality team (I’m biased, of course) and platform, worked with some great brokers and partners, and completed a few deals along the way too. We have, of course, learnt loads since inception, and it’s helping us form what we hope will be a brilliant lender for the future.
This all meant we managed to do something I thought would take a few years (at least). In December, we completed a £110m funding line with a credit provider in Pollen Street Capital. This was the first time I sat back and thought—perhaps we are on to something. This is when Bridging & Commercial decided to throw this Lancashire lad into its rather fabulous publication.
What does securing this funding tell us? Should lenders be focused on a USP or something different entirely?
We often hear—and we always want to hear more—of the frustrations brokers experience. From complicated systems to slow responses, changing the deal at the 11th hour or lenders being just being flat-out hard work, the list is pretty endless.
For a lot of them, however, it boils down to one key gripe—deliverability. You can be 0.1% a month or have a 99.99% leverage product but, if you cannot deliver for your broker partners and their clients, it counts for nothing.
In my humble opinion, good lenders need a few basics. Trust is the backbone of any healthy relationship, and the delicate one between client, broker and lender is no different. Have great people and sensible funding lines. Consistency
and doing exactly what you say are the currency of the day and have been for centuries. If you’re going to win business, you need to deliver consistently, bring new products and features to market and continue pushing the boundaries—only this way can we drag our long-established sector into the modern era.
In a world becoming flooded with AI and automation, some think the role of us mere humans is dwindling. But not this grandson of a miner. It becomes even more fundamental and important.
Despite our tech-first platform, I am an avid believer that we are nothing without humans and their partners. Finding the balance between the two is the real beauty of the modern world. Double down on all the above and that’s
“You can be 0.1% a month or have a 99.99% leverage product but, if you cannot deliver for your broker partners and their clients, it counts for nothing”
90% of the battle—and you should get a group of brokers and clients who come back time and time again. Outside of this, I firmly believe the rest is up for grabs.
So, what does that mean for us?
Speed. Certainty. Simplicity. It doesn’t mean chasing a USP above everything else. How can we make your life easier? How can we help you win more business? I am in the enviable position of being able to build and push out a new product in a few days or, indeed, to change a part of the process that doesn’t work as you’d expect.
In the end, we are just humans who want to make clients’, brokers’ and everyone else’s lives as easy as possible. Our market—and indeed life for that matter—is hard enough, right?
So, back to where we started—it’s not necessarily a USP. If you combine being quick, which everyone claims to be, with trust, consistency and a sensible approach to clients who we want to keep forever—that’s the real USP.
There you have it. Grand wisdom from a guy who’s never given it before.
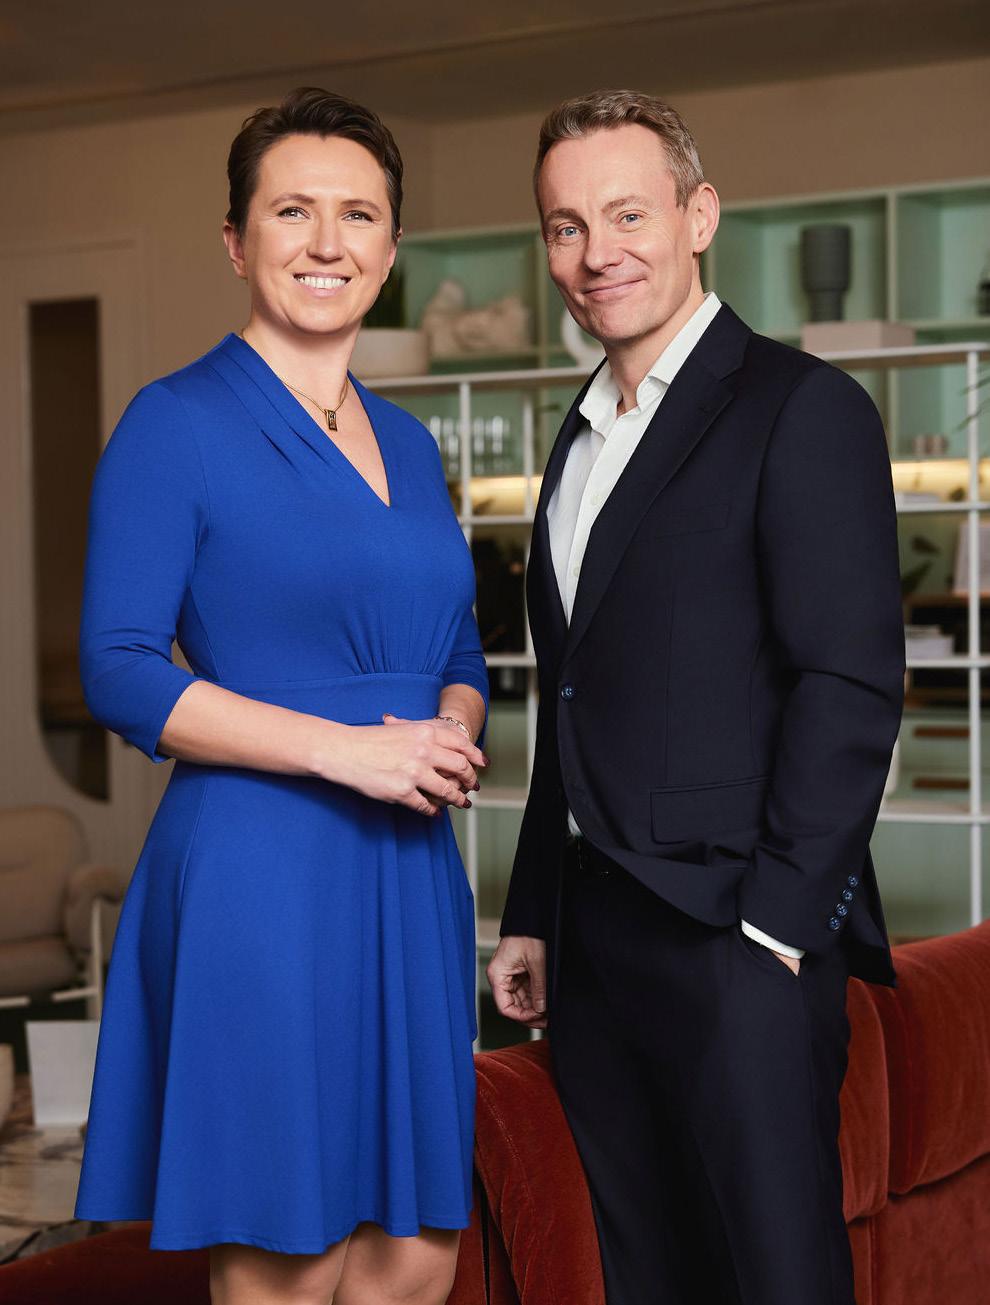
Pallas Capital has opened in the UK with a clear ambition: to raise standards in a market searching for greater professionalism, certainty and consistency. Ben Keenan, executive director, and Uliana Kuzmis, chief credit officer discuss earning trust in a new market, funding lines and autonomy—and how a Roman village can teach empathy
Expanding into a new market is a little like ordering a flat white in a foreign country: you assume it will be familiar, hope it’s done properly and trust your instincts enough to give it a go. For one Australian financier, the UK was the obvious next order.
On a wet Tuesday morning, I set off to meet the latest specialist finance firm to enter the UK market with a vision of delivering a reliable service to brokers to build trust and, ultimately, become a lender brokers continuously turn to. Pallas Capital—a non-bank lender within the Pallas Group—officially launched itself into the UK’s bridging and development finance market in mid-January. Founded in 2016 in Sydney in Australia by three veterans of the property and financial services industry, it now employs over 240 staff in eight offices in Australia, New Zealand and, now, London.
This is no tentative arrival. The Pallas Group holds a hefty £1.8bn loan book, having completed over 1,100 loans since its inception. The group has secured over £1bn of institutional capital from global names like Goldman Sachs, Morgan Stanley, National Australia Bank and Westpac, with additional funding already in place to support its UK expansion.
Leading the UK team is Ben Keenan, executive director, and Uliana Kuzmis, chief credit officer, both bringing over two decades of experience across real estate, credit and structured finance. Ben previously served as a director and general counsel at Multiplex Construction Europe, delivering major projects across multiple regions. At Pallas, he has played a central role in diversifying funding sources, describing the growing weight of institutional capital as “transformational”.
“Institutional capital is typically more stable, less sentiment-driven and materially cheaper” Ben explains. “That has allowed us to reduce pricing for borrowers, with the majority of those cost savings passed directly on,” he says.
Crucially, these banking lines provide what Ben describes as “genuine autonomy” —allowing loans to be written within agreed criteria without requiring funder sign-off on every transaction. “Facilities that provide this level of discretion are relatively common in Australia. In contrast, the UK relies more
heavily on forward flow structures which require loan by loan sign-off,” he says.
He adds that Pallas’s launch into the UK is significant given the firm already has an established business with a proven track record and is not a “start-up lender with an untested proposition”. “We have deeply embedded real estate expertise, disciplined credit processes and long-standing institutional funding relationships that we can now leverage in the UK market,” he notes.
A key question arises: how will this newly arrived lender aim to set itself apart from its competitors in a saturated market? For Ben, the state of the UK’s real estate lending market bears resemblance to that in Australia.
“In the sub-£3m lending space barriers to entry are low, which attracts family offices and private capital. At the other end of the spectrum, once you move beyond £20m, you’re competing with major financial institutions lending bilaterally. The real opportunity sits in the middle, where execution, discipline and reliability matter most” he states.
Access to well-priced, dependable capital is fundamental, but Ben is clear that pricing alone is not the key differentiator. “You don’t win by being the cheapest lender in the room. You win by being consistent, professional and dependable”.
He adds that brokers frequently cite frustrations around poor communication, shifting terms and risk appetite, and lack of clear ownership of deals.
“Those issues don’t reflect a lack of capital—they reflect a lack of process. That’s where we see the biggest opportunity,” he remarks.
Bridging & Commercial understands that the company will
initially target loans up to £20m, with ambitions to scale over time.
“Brokers won’t give you a £30m transaction until they know you can deliver. Trust has to be earned,” emphasises Uliana.
Ben points to the firm’s Australian growth trajectory as a blueprint. “Our first Credit Suisse facility allowed us to write loans of up to £4m without consent. Over time, as our platform matured and credibility grew, these thresholds were lifted. Our recent facility with Morgan Stanley supports loans of up to £17m. That progression takes time and discipline,” he shares.
Uliana, who has held senior roles at Hampshire Trust Bank and Octopus Real Estate, believes a clear professionalism gap exists in the market—particularly in development finance.
“Too many lenders step into development finance without the technical expertise it requires,” she says. “When that happens, it’s ultimately the client who pays the price.”
To avoid this, she shares that Pallas Capital will have discretionary funding or seek funder approval early, ensuring reliability of delivery and no surprises down the transaction timeline. “It requires more upfront work, but it’s the right thing to do and it protects the client,” she emphasises.
“Our underwriting team are trained, and our processes are built, by experienced development finance professionals. That depth of expertise translates into better execution, clearer communication and a far better client journey.”
Ben agrees, stressing the importance of alignment between origination, underwriting and credit. “A lack of certainty is one of the biggest frustrations in this market. Unless something unexpected arises during underwriting, terms should not change between offer and completion,” he says.
Ben’s background as a lawyer, business executive and property developer informs his approach to lending.
“As a lawyer, you’re trained to focus on downside risk and structure,” he says. “But lending is ultimately the business of pricing risk. The challenge is balancing rigorous risk management with commercial pragmatism.”
His experience raising institutional capital has also shaped how deals are structured. “Understanding what funders care about—their red lines and sensitivities—allows us to deploy capital effectively and at scale”.
Uliana highlights the credibility that Ben’s experience brings with borrowers. “Ben has lived the development process—securing sites, obtaining planning, raising finance and delivering projects in London and the Home Counties. He understands the pressures because he’s been there.”
Ben recalls developing through Covid as one of the toughest periods of his career. “Sites were shut down, planning delayed, supply chains disrupted and negotiations with funders and
“You don’t win by being the cheapest lender in the room. You win by being consistent, professional and dependable”
contractors were a daily headache,” he recalls.
He describes how, unexpectedly, a Roman village was discovered beneath one of his sites, which turned it into an archaeological dig overnight. “None of it was easy, but those experiences gave me enormous empathy for developers,” he emphasises. “That perspective is invaluable when assessing loans today.”
He and business partner Uliana share an almost unspoken language. “There’s no need to over-explain concepts—we move quickly, challenge each other and refine ideas collaboratively. That shared mindset, combined with a meticulous approach to detail, creates a very strong foundation for us here,” she expresses.
Culture emerges as a recurring theme throughout the interview.
“Culture is a non-negotiable for us—it’s the North Star for how we recruit, train and operate,” says Ben. “We want people who genuinely buy into creating an exceptional customer experience, because that’s ultimately what defines the brand.”
For Uliana, her “no-brainer” reason for joining the lender struck her at the very first meeting. “What truly sealed it for me was being flown to Australia within a week of that first meeting—before I’d even accepted the role. They wanted me to experience Pallas, not just hear about it. Culture is something you feel, not something you can explain on a slide or a poster,” she expresses.
She shares that after visiting the Sydney and Melbourne offices, her decision was made. “You could see the energy, the pride and the professionalism. In an environment like that, where such high standards are maintained, the possibilities are limitless,” she emphasises.
Uliana has been recognised for creating several products during her career. Her talent for continuously operating on full steam makes her the right candidate to get a project moving. “My mind never really switches off. I constantly question why things are done a certain way, where constraints come from and whether they’re justified, and how friction can be removed,” she explains.
“Too often, lenders replicate processes simply because that’s how they’ve always been done. Few stop and ask whether there’s a better way. Throughout my career, I’ve challenged those norms—creating new products, simplifying processes and removing unnecessary obstacles,” she says.
At Pallas, Uliana highlights that the luxury of starting with a clean slate has meant products are created around current customer needs. “Every product we design starts with the client in mind—what they need, where flexibility matters and how we can balance that with robust risk protection. Agility
“By the middle of the year, I want brokers to see Pallas as a lender of first choice—where their instinct is to come to us first when assessing a transaction”
and flexibility are core to who we are,” she contends.
In the months ahead, Pallas is focused on execution. “You’ll see a strong pipeline of completed loans, published case studies and some exceptional people joining the business. We’ll also be announcing new funding lines—hopefully within Q1,” Ben hints.
For Uliana, Pallas’s debut in the market is “one of the most exciting market entries of 2026”. “By the middle of the year, I want brokers to see Pallas as a lender of first choice—where their instinct is to come to us first when assessing a transaction,” she says.
On the horizon are a series of key hires, who Uliana says are already being finalised. “Even before the market knew who Pallas was, we were approached by exceptional candidates who wanted to be part of what we were building,” she shares.
“We’ve been incredibly disciplined about hiring—not filling roles for the sake of it but selecting people who truly fit the culture and bring the right energy,” she adds.
“When people meet the team, that energy flows directly into how clients experience Pallas.”
nderwriters are key to closing the lending gap
Words by MAHESH VEKARIA Head of underwriting—commercial mortgages at Allica Bank
BURKE
If all underwriters and banks looked beyond spreadsheets and into what makes companies tick, they could match the ambitions of business owners and support the UK economy
Whether it's a family-run firm that's existed for over 100 years or a founder who incorporated their business just a few years ago, every business and every business owner has their own story to tell”
Established businesses are the unsung heroes of the UK economy.
Whether they're looking after your kids at nursery, pouring pints at the local pub, manufacturing car parts to export across the globe or driving the lorries that get them there, these businesses are the lifeblood of the UK.
As an underwriter, getting into what makes these enterprises tick is one of the best parts of my job. Whether it's a family-run firm that's existed for over 100 years or a founder who incorporated their business just a few years ago, every business and every business owner has their own story to tell.
When I started my career in lending 15 years ago, I never realised just how close I was going to come to many of these stories. I assumed my focus would be just on the financial side of things, but that couldn’t have been further from the truth. In reality, underwriting that unlocks investment is just as much about listening as it is about spreadsheets.
Sadly, over the years, many lenders have become less interested in that side of a business, preferring instead to just look at management accounts and balance sheets. This narrow view has squashed lending to established businesses, with research from Allica last year revealing that a lending gap of £65bn has arisen over the past two decades when you compare the current level of SME credit to the long-run trend. It's left the UK with the lowest business investment rate in the G7.
Brokers already play a critical role in unlocking that investment. Banks should up their game to match the ambition of business owners and help them invest, too.
Having helped build Allica's commercial underwriting function from scratch in 2020, I've seen firsthand how a more holistic approach to underwriting can make a difference.
First and foremost, banks and underwriters need to start looking beyond the numbers of a business and really get into that story.
The leadership team, their ambitions and business plan, seasonal swings, advisers and network can paint a whole new picture of a business that their financials just won’t show.
For example, we received an application last year for finance to purchase a hotel. Initially, we were going to decline it because the owner did not have enough experience in the sector, while the financials provided by the existing owners did not hit the affordability levels we needed.
However, we wanted to dig into it a bit more so asked for extra information. It was only at this point that the borrower revealed that her husband, who had extensive sector experience, would be funding the deposit. She also shared a clear business plan that the couple had drawn up and could evidence that they would be able to meet our affordability requirements.
So we agreed to support the application, on condition that the husband be formally listed as director and provide a guarantee.
One of the biggest frustrations brokers share with me is getting access to those making the decisions—the underwriters. Especially when it comes to keeping things moving.
Sometimes, a simple five-minute conversation can save a backand-forth that might take a whole week over email. And, when a client’s waiting to get the deal done, that often isn’t good enough.
One thing I’m proud of at Allica is that our underwriters are always available to chat with a broker. Ultimately, we all want the same thing: to help an established business reach its next stage of growth. And having a quick chat is often the fastest way to do that.
Too many deals don’t get done because people don’t want to pick up the phone.
Technology is also going to be absolutely crucial to boosting access to finance, and underwriters have a responsibility to adapt to that reality.
The fundamentals of underwriting haven’t changed but the way we work has evolved significantly. It’s five years since I joined
Allica, and there’s probably been nowhere better to see the transformation of underwriting in action.
The explosion of AI has seen the pace of that change quicken dramatically. For example, we’re now able to use AI to do first-pass reviews of applications to spot missing information—manual work that would often take up a significant amount of my team’s time that they can now spend on the phone talking to brokers or understanding more about a business.
“Too many deals don’t get done because people don’t want to pick up the phone”
It’s vital, though, that lenders don’t let tech get in the way of those human relationships that are the beating heart of the industry. At Allica, we believe firmly that technology should enhance our customer relationships, not replace them.
In the medium to long term, the sector must not lose sight of the underwriters of tomorrow. We’ve all seen stories about businesses replacing junior roles with AI but, if we don’t invest in the skills of our future underwriters, there won’t be people to make these decisions.
At Allica, I encourage our junior underwriters to get comfortable with difficult conversations and make what often are life-changing decisions.
These skills come with time and, as automation streamlines administrative work, they can use this to their advantage, building interpersonal skills and taking the time to assess each business on its own merit.
If we want to close the lending gap and give established businesses the confidence to invest and grow, we need to get back to underwriting that values judgement as much as data.
That means underwriters who are accessible, curious and empowered to look at the whole picture. It means brokers being able to have proper conversations with the people making decisions. And it means using technology to remove friction, not human insight.
Get that balance right, and we will not just approve more deals but also make better ones—for brokers, for banks and, most importantly, for the established businesses that keep the UK economy moving.
“If we want to close the lending gap and give established businesses the confidence to invest and grow, we need to get back to underwriting that values judgement as much as data”
Mainstream lenders seem to be shutting their doors when it comes to large loans for complex cases—but demand hasn’t gone away. What should brokers do?
Words by DAN NARWAL
Intermediary corporate account director at Together
Securing high-value loans has become increasingly challenging after the economic turbulence of 2025. Rising interest rates, tighter lending criteria and a cautious approach from mainstream lenders have created an environment where clients seeking substantial finance, whether that be for commercial projects or for personal needs, often face roadblocks. For brokers, this shift raises an important question: how can you continue to deliver for clients when the mainstream market seems to be closing its doors?
As we move into 2026, the market is ever evolving. With the right approach, big opportunities are still within reach, and serving clients looking for larger loans remains important. Specialist lenders who invest in dedicated teams and personalised service are helping brokers thrive in a market where flexibility and expertise matter more than ever. That’s why we’ve set up a new service for brokers called Premier for Intermediaries, focused on supporting them with personal and commercial cases of over £1m.
The demand for large loans hasn’t gone away. Businesses still need capital to expand, property developers require funding to complete projects, and individuals continue to invest in high-value homes. What has changed is the route to securing that finance. Traditional lenders are increasingly focused on low-risk, straightforward cases as opposed to complex or time-sensitive deals—leaving a large number of underserved borrowers. This creates an opportunity for brokers who understand the landscape and know where to turn.
Large loans are often complex as clients may have multiple income streams, unconventional assets or ambitious timelines. Mainstream lenders with their automated processes often struggle to accommodate these, which is why specialist lenders have stepped in. They take a more holistic view of a client’s circumstances, assessing cases individually rather than relying on rigid criteria. This flexibility allows brokers to find solutions where mainstream lenders might only see obstacles.
Speed is another critical factor. High-value transactions often come with tight deadlines. Brokers who can access lenders that combine expertise with agility are better positioned to meet these demands. Experience matters here; lenders with a proven track record in complex cases can help brokers navigate challenges and structure deals that work for all parties.
When it comes to large and complex loans, having a dedicated team that focuses on each case can make all the difference. High-value finance often involves multiple moving parts—specialist valuations, legal
“Brokers benefit from working with professionals who understand the nuances of the deal, anticipate potential challenges and respond quickly when timelines are tight”
considerations and bespoke structuring to accommodate unique client circumstances. An automated process rarely provides the depth of attention these cases demand.
A dedicated team ensures continuity and clarity throughout the journey. Brokers benefit from working with professionals who understand the nuances of the deal, anticipate potential challenges and respond quickly when timelines are tight. This collaborative approach creates efficiency, reduces delays and builds confidence for both broker and client. It also means that decisions can be made with a full understanding of the client’s objectives rather than being constrained by rigid frameworks.
Equally important is the ability to offer a truly bespoke service. No two clients are alike and applying rigid criteria can lead to missed opportunities. A tailored approach allows lenders to consider the bigger picture, looking beyond standard tick-box assessments to find solutions that fit the client’s circumstances. For brokers, this means being able to say “yes” more often and deliver outcomes that strengthen relationships. In a market where trust and reliability are paramount, this level of service can set brokers apart.
Large loans are still achievable, but they require a different mindset and the right relationships. Brokers who succeed in this space are those who stay informed about market trends, understand the role of specialist lenders and prioritise flexibility and collaboration. By doing so, they can continue to meet client expectations and grow their business even in a challenging environment.
As we move into 2026, the market will continue to evolve, but big opportunities remain within reach. Clients will always need funding for ambitious projects, and brokers who can deliver tailored solutions will remain in high demand. Specialist lenders such as Together, which invest in dedicated teams and personalised service—such as Premier for Intermediaries—are helping brokers thrive in a landscape where expertise and adaptability matter more than ever.
Brokers: don’t let complexity become a barrier. With the right approach and the right partners, you can unlock opportunities that others overlook and position yourself as a trusted adviser in a market that values knowledge, speed and flexibility.
Turn complexity into completion with personal and commercial loans over £1m.
With bespoke underwriting, our dedicated team can support:
• Diverse income streams
• Foreign nationals
• Complex business structures
Contact our dedicated team on 03330 601 565.


After death, an ordinary estate can easily take a year to go through probate. In the meantime, hefty bills such as inheritance tax can become due. This is how short-term loans can tie families over
Head of growth at Ampla Finance
robate delays can cause real problems for families waiting for an inheritance. Even though the courts have cut the time to grant probate to just over four weeks on average, that is only one part of the process.
From the date of death to final payout, a normal estate can take six to 12 months to go through the process. It can take longer where there are overseas assets or trusts. During that time, property, bank accounts and investments can be tied up. Bills do not stop. Tax does not stop.
Demand on the probate system is high. Government data show there were around 292,000 probate applications in 2022. That figure has been rising by about 3% a year since 2020. The Probate Registry is expected to deal with around 350,000 cases a year. There has also been a rise in long delays. The number of cases
taking more than a year to get granted has risen by 134% in three years. Cases taking close to two years are up by 132%.
Inheritance tax is usually due by the end of the sixth month after death. In many cases, some or all of that tax must be paid before probate is granted. This creates a clear cash gap. Executors may have to cover tax, funeral costs, care fees and mortgage payments while the main assets are still locked. Where the estate is short of cash, the usual answer is a quick sale of the main property.
In a slow or uncertain housing market, that can push families towards discount sales or cash-buyer offers. The tax bill is paid, but the estate can lose a large amount of value.
Used in the right way, probate lending can help prevent forced sales. It can fund the inheritance tax bill so executors can wait for a fair market offer rather than accepting a low price to hit a deadline.
Other common uses include:
• light works before sale: a small budget for basic work can help a tired property sell for more
• buying out other heirs: one beneficiary may want to keep the family home and short-term funds can help them buy out others while the estate is settled
• support while funds are tied up: some families need cash for day-to-day costs while the estate is in probate
The key point is simple. Where an estate has value but not enough ready cash, short-term finance can protect both beneficiaries and executors. Nonetheless, it should sit alongside clear family communication and a careful check that the numbers work.
How finance can help was highlighted in recent case. A Surrey-based broker came to
us looking to assist a client who needed to consolidate some existing debt and raise funds to tide him over the Christmas period until his inheritance could be properly realised.
We had the application in on Wednesday and assessed the same day. After a few clarifications and requests for additional information, the loan was approved just five working days later. The loan was live a week later by the start of December, once all the documents had been signed and approvals come from the executor on the case.
“Used properly, bridging/probate finance can help cover urgent costs, avoid a forced sale and give executors and beneficiaries time to settle the estate in an orderly way”
Points to cover early on
If you are speaking to an executor or beneficiary, a few early questions can save time:
• are all executors happy to agree to the loan?
The result was simple. The client got the funds they needed while the estate process continued and was not forced into making a rushed decision at the worst time of year.
• is the will being disputed?
• was the deceased a resident in the UK at time of death?
• have the assets in the estate already been valued?
In short, probate delays can leave families short of cash at exactly the wrong time, even when there is plenty of value in the estate. Used properly, bridging/ probate finance can help cover urgent costs, avoid a forced sale and give executors and beneficiaries time to settle the estate in an orderly way. For brokers, the focus must be on speed, clear evidence and the right consents so clients can access funds when they need them while the inheritance is being realised.
Short-term and flexible financing for your clients property projects. From Refurbishments to Regulated Bridging we have fast and flexible solutions.
Highlights include:
• Regulated and unregulated
• Dual-representation: one solicitor for both parties saving time and money
• Refurbishment Bridging up to 73% net LTV
• Covering auctions, house-flips and landlord refurbs
• Access to expert support, including Underwriters
• AVMs available up to 65% LTV on regulated bridging, and up to 75% LTV on unregulated bridging.
Simple, for everyone.
Flexible on experience
Solution driven equity structures
Flexible on PGs
Acquisitions and development exits Net Sales proceeds available Lend against market value NOT 180 day value
The past 12 months have tested underwriting in major ways. Shifting market conditions, tighter timeframes and increasingly complex deals have meant that good underwriting is no longer enough—it requires judgement, resilience and the confidence to make difficult decisions well.
This year’s Power List recognises the underwriters who consistently rose to that challenge. These are the individuals brokers turn to when certainty matters and information is imperfect—and when it could make the difference between a deal completing or falling away.
Across bridging, commercial and development finance, each nominee has demonstrated a solutions-led mindset, balancing risk discipline with realworld pragmatism. Their work over the past year hasn’t just delivered individual transactions—it has helped maintain trust, momentum and professionalism across the specialist finance market.
Chief operating officer at Albatross Lending Group
Joshua has been recognised for underwriting excellence, commercial judgement and deal structuring and is a “long-term pillar” of Albatross, according to his team. He consistently rescues complex or previously declined cases by accurately deconstructing risk and designing viable funding solutions without weakening credit standards, directly protecting portfolio performance while driving growth.
He plays a central role in the lender’s expansion, including launching lending divisions and supporting the securing of multiple funding lines. Internally, he has redesigned credit processes, raised underwriting standards across departments and built a high-performing credit team aligned with strong commercial outcomes.
Head of underwriting— growth finance at Allica Bank
Christina joined Allica Bank as its first and sole underwriter, building the underwriting function from inception when the bank held only a licence and strategy. She designed core credit frameworks and policies, underwrote Allica’s first transactions and set the standards that underpin its reputation for disciplined, commercially minded SME lending. Under her leadership, underwriting has been scaled up to support commercial mortgages, asset finance and working capital, with the loan book growing into the billions. Christina has embedded robust risk governance while enabling complex SME lending through bespoke credit structures.
Her work has directly shaped how Allica assesses risk, scales responsibly and serves the UK SME market.
Senior structured finance manager at Octane Capital
Jamie has been commended for delivering exceptional results for Octane Capital by closing complex, high-value transactions. He secured a £10.5m bridging loan for a multi-property student accommodation portfolio, untangling ownership structures to meet tight deadlines. Jamie also completed an £8.2m prime residential bridge within four weeks, balancing speed with rigorous credit judgement.
His expertise revives stalled deals; he restructured and approved a £2.3m finish-and-exit facility for a developer who had been declined elsewhere, completing it in three weeks. Brokers consistently cite his practical, communicative approach and ability to clearly explain decisions.
Louise Young
Louise is responsible for delivering complex transactions while supporting consistency and capability across the underwriting function. She regularly underwrites multi-asset cases to tight deadlines and provides guidance to junior underwriters on structure, risk assessment and broker communication.
A recent £2.5m bridging loan involved security across three titles with planning submitted but not granted and a conditional exit strategy.
Louise conducted early borrower engagement, clarified planning and exit risks upfront and discussed details of the deal closely with the broker, enabling completion within eight days of the legal cost undertaking being received.
In addition to underwriting, Louise contributes to internal process development, including system enhancements and the implementation of dual representation, supporting efficiency and risk control across the business.
Director of bridging at MT Finance
Raphael has been with the lender since 2020 and assumed his role in March 2025. He is responsible for overseeing both regulated and unregulated bridging activity, with accountability for underwriting standards, credit decision-making and delivery across the division.
Over the past 12 months, Raphael has continued to underwrite complex and high-value cases alongside his leadership responsibilities, applying structured risk assessment and clear credit judgement. His oversight of underwriting processes and governance has supported consistent execution at scale and maintained lender and broker confidence across challenging transactions.
His leadership contributed directly to MT Finance securing Regulated Bridging Lender of the Year at the 2024 B&C Awards for a second consecutive year, reflecting the ongoing performance of operations under the frameworks Raphael established and continues to oversee.
Underwriter at Lakeshield
Trudy is known at Lakeshield for being the underwriter brokers trust with their most complex bridging cases. Specialising in highrisk, time-sensitive deals, she cuts through convoluted submissions to focus on two core issues: asset quality and a viable exit. Her skill was critical in completing an auction purchase of a property with an illegible lease and an absent freeholder by the auction deadline. By structuring a solution around title insurance, she navigated a significant title defect that would have stalled most deals. Beyond individual cases, Trudy has reshaped her firm’s entire approach. She introduced mandatory video calls with every borrower—a move that enhances transparency, prevents misunderstandings and has successfully identified regulatory red flags. Her analysis of completed files was instrumental in streamlining internal processes, directly enabling the launch of her company’s flagship seven-day bridging product.
Lending manager at Inspired Lending
Nathan is behind the management of complex bridging transactions involving legal, financial and asset-level risk. He works closely with brokers to identify material issues early, define requirements clearly and maintain momentum through structured communication.
A recent transaction involved a £1.175m net loan to a non-trading, technically insolvent limited company, secured against a vacant, unlettable commercial property in in Brixton, London. Nathan managed a detailed legal review with external solicitors, assessed insolvency risk and undertook a pragmatic evaluation of asset condition and saleability. To support timescales and control borrower costs, he agreed to proceed using an existing valuation.
By managing information flow across multiple parties and resolving issues as they arose, Nathan ensured the transaction progressed toward completion despite significant complexity.
Head of credit and operations at Black & White Bridging
Heather has contributed directly to business growth and underwriting delivery. She has personally underwritten and completed over 150 loans, accounting for more than £120m in drawn funds, and has supported brokers across 300-plus transactions totalling £285m, including non-completions.
Her experience spans auction purchases, refurbishment finance and non-standard cases, including transactions where issues have arisen late in the process, or previous lenders have withdrawn. Her focus on material risk, exit viability and deliverability rather than prescriptive criteria has enabled structured, workable outcomes.
Currently, she manages a live pipeline of 16 loans totalling £26m, balancing speed with robust credit assessment.
Iain enables difficult cases to progress while reinforcing broker confidence. On a £1.65m refinancing and capital-raise involving regulatory considerations and a tight redemption deadline, Iain assumed senior ownership of the case, coordinated with second-line credit and senior management and enabled informed decision-making under pressure. The facility was completed successfully and redeemed as planned. On a separate £1.7m transaction initially declined at second line, he revisited structure and mitigants with the underwriting team and facilitated further review, resulting in approval and completion. Internally, his hands-on mentorship embeds this approach to ownership and clear communication across the entire underwriting team. As noted by colleagues, his willingness to step in and resolve problems under pressure directly builds broker confidence.
Over the past year, Matt has delivered a high volume of non-standard cases while maintaining credit discipline in a cautious lending environment marked by compressed timeframes and valuation volatility. He provides clear, timely credit analysis and proposes alternative structures where initial submissions fall outside criteria, supporting improved completion rates and reduced fall-throughs through early issue identification. He prioritises broker engagement from enquiry to completion, supporting consistency and momentum on challenging transactions.
A recent case involved a heavy refurbishment loan to convert a vacant pub into homes, with no day-one income and a refinance exit dependent on practical completion. Matt structured staged drawdowns linked to verified milestones. Interest retention, conservative LTGDV and monitoring minimised delivery risk while allowing the borrower liquidity to progress works.
Craig Reiselson
Deputy head of BTL and specialist lending underwriting at Market Financial Solutions
Having joined the business in 2017 as one of two underwriters, Craig has played a key role in its scale-up, including oversight of its first £100m funding line.
Key recent achievements include the refinance of an 11-property portfolio where the borrower faced imminent receivership. Navigating borrower health issues and cashflow stress, Craig leveraged long-standing legal relationships to secure the assets and satisfy all stakeholders. He also completed a sizeable commercial mortgage within five weeks from enquiry.
His mentorship continues to develop talent, and he has guided several underwriters into senior roles.
Underwriting director at Together
Ben has been at Together for over 11 years and, in that time, he’s earned a reputation for making the trickiest commercial deals feel doable.
Last year, he launched Together’s commercial underwriting boot camp, helping colleagues to improve their skills while keeping morale high. He thrives on complex transactions, including same-day completions, always staying calm, clear and solution-focused—even when faced with a mountain of paperwork.
Head of underwriting at Avamore Capital
Ed is consistently recognised by brokers as a decisive, transparent underwriter who excels in complex scenarios. His strength is in structuring bespoke facilities where deals sit outside conventional parameters, balancing commercial pragmatism with disciplined risk. A recent example was a multi-million-pound refinancing for a student accommodation scheme with building safety issues. Ed redesigned the facility, aligning drawdowns with remediation milestones and stresstesting exit assumptions against downside scenarios. He worked closely with all parties to ensure compliance and viability, securing completion.
His direct, accessible communication style and proactive collaboration foster strong broker loyalty and repeat business. Ed thrives on creatively mitigating risk and delivering clear, workable solutions under pressure.
Chief credit officer at Pallas Capital UK
Over the past 12 months, Uliana played a central role in establishing Pallas Capital’s UK underwriting and operational framework. She designed an end-to-end credit and delivery process covering indicative terms, approvals in principle, legal structuring and completion, with early risk identification embedded throughout.
Alongside this, Uliana acted as a consultant underwriter on complex transactions for other lenders. One such case involved an airspace development on a leasehold title, structured as a share purchase with overage provisions. She assessed and mitigated layered legal and credit risks, enabling approval and completion within weeks. The scheme has delivered nine homes. Her approach promotes early credit engagement, reduced late-stage fallout and consistent decision-making, supporting delivery certainty and scalable underwriting standards.
Head of APAC at Tenn Capital
Declan is distinguished by his ability to structure complex, high-value bridging and commercial deals where others see obstacles. Over the last 12 months, his commercial judgement and methodical risk assessment have been pivotal in reshaping stalled transactions into successful completions.
He works closely with brokers to reshape deal structures, address credit concerns early and maintain momentum, resulting in successful completions that might otherwise have stalled or been declined. Clear, timely communication supports expectation management when issues arise or circumstances change.
Alongside deal execution, Declan has contributed to the development of underwriting standards and decision-making consistency across the team. His relocation to Australia to lead underwriting activity in the APAC region, reflects confidence in his ability to replicate UK success there.
Structured finance associate at Mera Investment Management
Prabhat takes a holistic approach to underwriting complex development and value-add transactions, assessing construction risk, cashflow resilience, legal exposure and delivery timeframes rather than relying solely on headline LTV or GDV metrics.
On an £11m self-storage development in Mayfair, late-stage risk emerged around insufficient power supply to support full operational capacity. Prabhat reviewed the MEP report, identified viable technical solutions and restructured the facility with increased contingencies and bespoke conditions, enabling completion within tight deadlines while appropriately mitigating risk.
He also underwrote a £16.3m finish-and-exit facility involving offshore trust equity, mezzanine finance and legal complexity, including Duval-related risk. By coordinating technical, legal and stakeholder inputs, responding rapidly to queries and bottoming out build costs, he ensured the transaction progressed to completion within credit parameters.
Senior bridging underwriter at Allica Bank
Following the Tuscan Capital acquisition, Jade maintained delivery continuity while new systems, processes and products were introduced at Allica. In 2025, she underwrote and completed over £62m of bridging transactions, with an average SLA of 42 days from application to completion.
During this period, she delivered several firsts for the bank, including the initial bridge-toterm transaction and the first fully integrated deal combining bridging, term lending, asset finance and a business rewards account. She also completed a complex transaction within five days from start to finish, including valuation and full legal due diligence
Senior mortgage underwriter at LendInvest
Warren has spent nearly 25 years mastering specialist lending and, in 2025, he proved why he’s LendInvest’s go-to underwriter for the trickiest deals. One standout case was a 50-property acquisition from Cala Homes across four sites, totalling nearly £25m—essentially, a four-way jigsaw of loans, special purpose vehicles, deposit subordination and tight completion timeframes. Where others might have hesitated at a 90% loan to purchase price, Warren broke down the true risk, validated the bulk discount and coordinated cross-collateralisation so the borrower could draw funds safely across multiple sites. The deal closed in three months, with curveballs evaded at every turn.
Emma Goodyear Senior corporate underwriter at Together
Emma has built a reputation for getting tough commercial deals across the line with speed, creativity and a people-first approach. Drawing on experience across sales, recoveries and lending, she combines technical expertise with a knack for understanding different perspectives—a skill that keeps brokers confident even when deadlines loom.
In December 2025, she led one of Together’s first Heter Iska-funded transactions: a £7.9m office acquisition in Scotland with partial leases, unusual rent schedules and a four-day completion window after another lender withdrew. Emma coordinated internally across treasury, policy and loan servicing, worked with external lawyers and presented a clear credit case, ensuring the loan closed on time without penalties.
Head of underwriting at Hope Capital Property Finance
Laura has been the heartbeat of Hope Capital for 11 years, rising from part-time assistant underwriter to head of underwriting, leading a 14-person team.
In 2025, Laura drove 61% growth in loan book value, a rise of 46% in facilities funded as well as faster, smoother completions through innovations such as instant valuations and expanded dual representation. Her calm, can-do approach has turned complex deals—including simultaneous refurbishments across 11 flats with tricky titles—into success stories.
Underwriter at Funding 365
Fraser has quietly become a go-to underwriter at Funding 365, balancing calm determination with a can-do attitude across development exits, heavy refurbishments and specialist BTL. Even on Christmas Eve, Fraser completed a tricky £800,000, 73% LTV London refinance, juggling an invalid EWS1 certificate, valuation rechecks and security changes—keeping mince pies on hold. Earlier in the year, he drove a bespoke £4.3m Norfolk development exit to completion, keeping every party aligned despite shifting terms and missing certificates.
Gene Clohessy
Director of underwriting—BTL and bridging at United Trust Bank
Gene has transformed United Trust Bank’s BTL and bridging underwriting since they were merged in 2025, turning complexity into clarity and bottlenecks into speed. She championed end-to-end case ownership, empowered her team with training and accountability, and streamlined processes that were fundamental to improving services. Brokers notice the difference: faster decisions, meaningful feedback and smoother journeys. Under her leadership, underwriters handle cases with confidence and the team has become a powerhouse of efficiency and consistency.
Whether it’s tackling tricky valuations, navigating legal quirks or simplifying multi-stage approvals, she makes it all look easy.
Orla Mooney
Underwriter at Allica Bank
Last year, Orla underwrote and oversaw 182 bridging and commercial deals at Allica Bank totalling £93.5m and taking an average of two to three days from application to completion—proof that speed and precision can coexist.
She is recognised by her peers for her practical, problem-solving approach to underwriting. When a £10m specialist BTL portfolio involved multiple special purpose vehicles, high property costs and tricky interest coverage ratios, she untangled the numbers and reconciled the positions of all structures involved.
Orla engages early with brokers and internal teams, exploring alternative structures and spotting risks before they become headaches.
Nicky Vaughan
Senior underwriter at Market Harborough Building Society
Nicky turned a tricky £2.5m urgent re-bridge into a smooth success for high-net-worth borrowers, a deal many lenders wouldn’t touch. The case involved multiple titles, extensive acreage and a part-charge structure, all under tight timeframes so the borrowers could complete their development before selling. Nicky’s experience and problem-solving made the difference: she secured a quick valuation retype, liaised with solicitors, navigated warranty issues and structured the loan to include a family member. Clear, proactive communication with brokers, clients, surveyors and legal teams kept everyone aligned. From offer to completion over seven working days, Nicky delivered certainty, momentum and a happy client every step of the way.
Jack Ainsworth
Senior underwriter at Roma Finance
In 2025, Jack completed £27m of development loans. Brokers value how clear and responsive he is, particularly on complex cases where assumptions need to be tested and decisions properly explained. He takes time to understand each deal, flags issues early and works with brokers to find practical ways forward without compromising credit standards.
Jack is regularly trusted with the most challenging transactions, including those with tight timeframes or unconventional structures. His calm, methodical approach helps keep deals on track and gives brokers confidence in the process. His contribution is reflected not just in volumes but also in improved turnaround times, stronger broker relationships and consistent delivery across the team.
Head of underwriting at MS Lending Group
Michael is the kind of head of underwriting people rely on when things get complicated. After over a decade in the market, his judgement is steady and well-earned, and he has a good sense of where risk really sits versus where it just looks uncomfortable.
He stays close to the detail, makes himself available to talk through tricky cases and supports underwriters in reaching their own decisions rather than handing down answers. Clear standards are set, but with room for common sense and professional judgement.
His calm, approachable style has built a team that works collaboratively and consistently, and brokers know they’ll get straight answers and fair decisions.
Michael Schofield
Underwriting director at Together
Michael makes underwriting look effortless. He combines speed, clarity and practical solutions, giving brokers options when the answer isn’t a straight “yes”.
Leading Together’s unregulated bridging proposition, he manages hundreds of applications a month while driving initiatives such as the company’s concierge service and its Immediate House Sales scheme, where purchasing at speed is key to a buyer’s business model. From rescuing complex offshore deals to guiding first-time auction buyers, Michael balances speed with sound judgement.
Highlights include Together’s fastest-ever bridging loan— done in 78 minutes—and multiple rapid completions.
Senior underwriter at Alternative Bridging Corporation
Hannah is commended for her collected judgement, clear decisions and getting complex deals moving. She takes early ownership, focuses on the real issues and sets out a practical route to completion without unnecessary noise.
Recent highlights include completing a multi-let commercial transaction across five titles, where she worked hands-on with solicitors to resolve title issues and agree a workable risk position. She also delivered a partially completed regulated development with complex planning, staying closely involved through site visits and calls, and being clear about timeframes.
Brokers value Hannah’s phone-first, straight-talking approach and consistent follow-through. Strong completion rates and repeat business reflect an underwriter trusted to balance risk, pace and practicality—even when deals get messy.
David Milstead
Senior commercial underwriter at Atom Bank
David has been crucial to Atom bank’s most complex transactions, including pioneering its move into biodiversity net gain (BNG) credit financing. He assesses these novel, policy-exceptional deals on their merits, and has successfully structured facilities for two separate BNG habitat banks, which will ultimately enable hundreds of new homes. He also efficiently oversees larger, complicated commercial deals. His work on a £1.7m transaction with an unusual purchase and lease structure led to two further referrals from the same broker, totalling approximately £5m in additional business.
Renowned for clear communication and flexible problem-solving, David holds the highest underwriting mandate at Atom Bank, reflecting the deep trust placed in his expertise and judgement by both the bank and its broker partners.
Metcalfe
Senior underwriter at Roma Finance
Jason is trusted by brokers when a development deal needs careful handling rather than quick assumptions. He’s methodical, approachable and prepared to spend time understanding what’s actually driving a transaction before landing on a structure. That often makes the difference in cases that don’t fit neatly into standard templates.
Last year, Jason completed £31m of development lending, much of it involving layered risk, shifting timeframes or borrower-specific challenges. He’s known for staying close to deals as they evolve, adjusting structures where needed and explaining decisions clearly so everyone understands the reasoning.
As the architects of truly transparent lending, we know speed matters...
Our commercial bridging solutions typically complete within four weeks, helping your client secure the asset and start generating income sooner.
SOME LENDERS ACT LIKE THE MAP ENDS AT THE M25.
ScotLend lends across England, Wales and Scotland, including the Highlands and Islands. If your deal makes other lenders nervous, send it our way.
No postcode excuses. No location panic. No Drama. Just Deals.
Scan to submit a deal
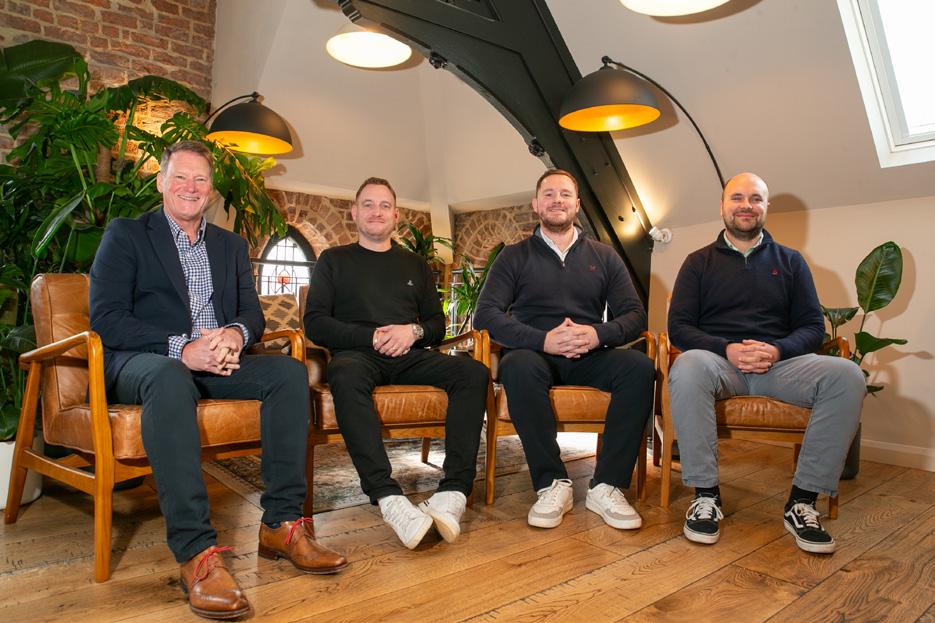
Raised out of frustration, Kozo is a new bridging and development lender with a different mindset. Founders Ky Benjamin, Chris Britto and Joe Eden discuss the Japanese philosophy shaping the business, the reality of running two companies at once, and their mission to give clients what they’ve been missing
Words by DHUHA AL-ZAIDI
Photography by CONNIE BURKE
There’s one place on my bucket list I’m yearning to visit, famous for its raw food, martial arts and a drink I’m fond of that frankly looks like blended grass. I am, indeed, talking about Japan.
I zap out of my trance and deep desire for an adventurous holiday and focus on my journey to Southend—an unlikely setting for a conversation shaped by Japanese philosophy. I greet three specialist finance practitioners, Chris Britto, Joe Eden and Ky Benjamin, to discuss the debut of their company.
A Japanese word meaning structure comes up in our conversation early. Not the rigid kind but one that creates clarity and longevity. It’s a fitting reference not just for the brand but also for the mindset behind it.
I find out it’s born out of exasperation with how many lenders operate. Following shared experiences and frustration, a new name is beginning to emerge in the bridging and development finance market: Kozo.
While others were eating the delicious set menu at the B&C Awards and catching up with industry folk, I’m told the three ended up sitting at the same table and, by the end of the evening, had decided to combine expertise to establish a lender with a difference—plans that came to fruition in a matter of months.
Joe, co-founder of Kozo and brokerage Bridgemore Capital, began in estate agency before moving into the specialist finance world, where he crossed paths with Chris over a hotel deal, which led to the establishment of their brokerage. He says that, over the years, feeling irritated by lenders led to the discussion to form a new lender.
“As we became more embedded in specialist finance, the frustrations became much clearer. Some lenders were great, but others were incredibly difficult to work with. We kept coming back to the same question: “How good would it be if one day we could do this ourselves?” he says.
Joe, who also runs a property development company that works on schemes ranging from single to 25 units, says that the diverse perspectives of the three co-founders—broker, developer and lender—has allowed them to sense the various sides of working in the industry and understand rigid deal structures, tight deadlines and the necessity for persistence to get projects
over the line. “The aim is to build a lender that’s commercially savvy, makes quicker decisions and removes as many recurring frustrations as possible,” he explains.
Chris, whose background stems from sales to selling offplan and completed property investments to UK and overseas investors, says that working closely with developers across the country means he has observed first-hand the pressures they face.
“Selling off-plan is tough—you’re asking people to buy something that doesn’t exist yet. If sales didn’t happen early enough, cashflow became an issue and that directly impacted the build. That experience gave me a strong understanding of the pressure points across the whole process,” he explains.
That experience and knowledge were motivating. “When lenders can’t deliver, I find that incredibly frustrating. Joe and Ky experience frustration in different ways but that’s actually one of our strengths. As a team, we’re irritated by different things and we’re able to shape Kozo in a way that genuinely improves the client experience,” he adds.
For Ky, who has been operating in the other side of the industry as a lender for more than 15 years, explains that working across underwriting, strategy and scaling a company has enhanced his awareness of how he wants his own enterprise to run. “Over time, you naturally start to see what works, what doesn’t and what you’d do differently if it were your own business. That itch doesn’t go away and, eventually, you have to act on it,” he states.
Creating a lender where all parties saw eye to eye was key. “What mattered most to me was doing this with people I trust and enjoy working with. We’re different personalities, but our values and ethics are very aligned, which is rare and incredibly important,” he expresses.
Despite the lender only taking a few months to set up, from planting the idea seed in June to securing funding lines in December, the trio are already looking at scaling up.
“At the moment, it’s just the three of us, and that’s a powerful position to be in. Realistically, toward the end of Q3 into Q4 is when we’ll start growing the team properly. When we do, it’ll be intentional but probably quite aggressive,” Joe states.
Ky explains that assuring the lender’s identity is a priority and not doing this carries risks. “Right now, we are the business identity. It’s important to establish that clearly before scaling. As soon as you bring new people in—even great ones— there’s a risk of dilution,” he suggests.
“We want to deliver consistently, establish exactly what Kozo stands for and then bring people in who can genuinely carry that identity forward.”
WE’RE NOT CLAIMING TO SOLVE THE INDUSTRY PROBLEMS. IT’S ABOUT HAVING MORE CONTROL, A BETTER UNDERSTANDING AND PLUGGING A GAP WHERE THE SAME FRUSTRATIONS KEEP REPEATING”
“We
wear the broker’s shoes and the borrower’s shoes. I’ve been a broker—I know exactly what that pressure feels like and, simply put, communication is everything”
From the broker side, Chris and Joe convey that fellow brokers and borrowers have felt disconnected from lenders and BDMs, who give hope by saying yes to a proposition before the case is passed on internally and ultimately grinds to a half.
Chris reports that lenders can overpromise on speed or terms then change LTV or pricing mid-process. “More importantly, deals aren’t driven. If something needs to complete in three or four weeks, it requires daily momentum. Too often, that urgency just isn’t there,” he says.
“I want to work with a lender where you agree a deal and then drive it together—commercially, collaboratively and with real effort.”
“We’re not trying to reinvent the wheel. The market is saturated and there are a lot of very good lenders out there. We’ll still use them where they’re the right fit,” adds Joe.
“Kozo isn’t a silver bullet. We’re not claiming to solve the industry problems. It’s about having more control, a better understanding and plugging a gap where the same frustrations keep repeating.”
According to Ky, these annoyances open up opportunities: “We want to take the best parts of the industry and remove the elements that consistently cause pain.”
For him, it’s about the concept of kaizen, or continuous improvement: “For us, Kozo is about elevating the good parts of the industry—not trying to reinvent it.”
For Joe and Chris, the experience of co-owning a brokerage has paid off.
“We wear the broker’s shoes and the borrower’s shoes. I’ve been a broker—I know exactly what that pressure feels like and, simply put, communication is everything,” he highlights.
For Joe, seeing deals fall through after clients have paid for valuations and legals made him determined to do something about it. “That’s incredibly irritating for everyone involved. We’re not saying we’ll solve everything but we understand development at a practical level, not just on paper,” he says.
He says that post-completion service matters just as much as pre-completion, especially on development loans. “You’re in bed with that lender and, if they don’t understand the process, that’s worrying,” he adds.
Chris tells me he favours being upfront, and that this has saved them. “I tell the client: ‘Do you want a very quick indicative quote, or do you want terms we’re confident we can actually deliver on?’ Too many lenders chase quote volume
instead of delivery,” he claims.
Throughout our discussion, it is clear that the emphasis is on service. For this reason, the lender has deliberately chosen products that are “right for specific projects and investors”, says Joe.
“We will always put the client and their needs first,” says Chris. “If Kozo isn’t the right lender for them, we simply won’t use it. That integrity is non-negotiable.”
Joe explains that their focus is on bridging, “speed-led products” and “below-market-value lending”, where they recognise demand is strong.
“For our refurb product, it’s not full development—but it’s not just light-touch either. That in-between space comes up far more often than people realise, and it’s where we see a lot of strong deals that don’t quite fit existing categories,” he clarifies.
In terms of lending below market value, Joe explains that these loans aren’t for people with no money trying to get started but are deals where genuine value exists.
“We’ve spoken to lenders who say, ‘There’s no such thing as below market value.’ But we’re seeing it first-hand. There are landlords who are tired of EPC changes, interest rate rises, stamp duty shifts—everything that’s happened over the last five, six, seven years—and now they want out,” he explains.
He is observing a new generation of investors are coming in with a different mindset, providing a new route for business. “Bridging used to be seen as a dirty word, but that’s changed. Younger investors now understand what bridging can do for portfolio building and running a property business properly,” he notes.
If, like me, you’re wondering how Chris and Joe are managing both businesses, it appears that, like the carefully constructed intentions behind the lender, they’ve got it figured out.
“Bridgemore is self-sufficient. We’ve built strong systems, a capable team and clear processes. While Joe and I will still write business, the capacity is being managed carefully,” explains Chris. “As Kozo grows, both businesses will recruit accordingly. It’s a controlled and deliberate transition.”
Despite efforts to improve the reputation behind bridging and development finance—one of speed, instability and complexity—behind every deal is a realisation that shapes the lender’s philosophy.
“Borrowing millions is stressful. We want to support borrowers through problems, not rush to receivership,” says Joe. “We want long-term relationships, not short-term wins. Regardless of how cliché this is, behind every loan is a person, a family and a livelihood, and that matters.”
Interest rates starting from 0.69% at 75% LTV
Dual representation
Below Market Value lending up to & over 100% of pur chase price
Loans from £37,500 to £1m
Lending in England, Scotland & Wales
Smaller developments considered
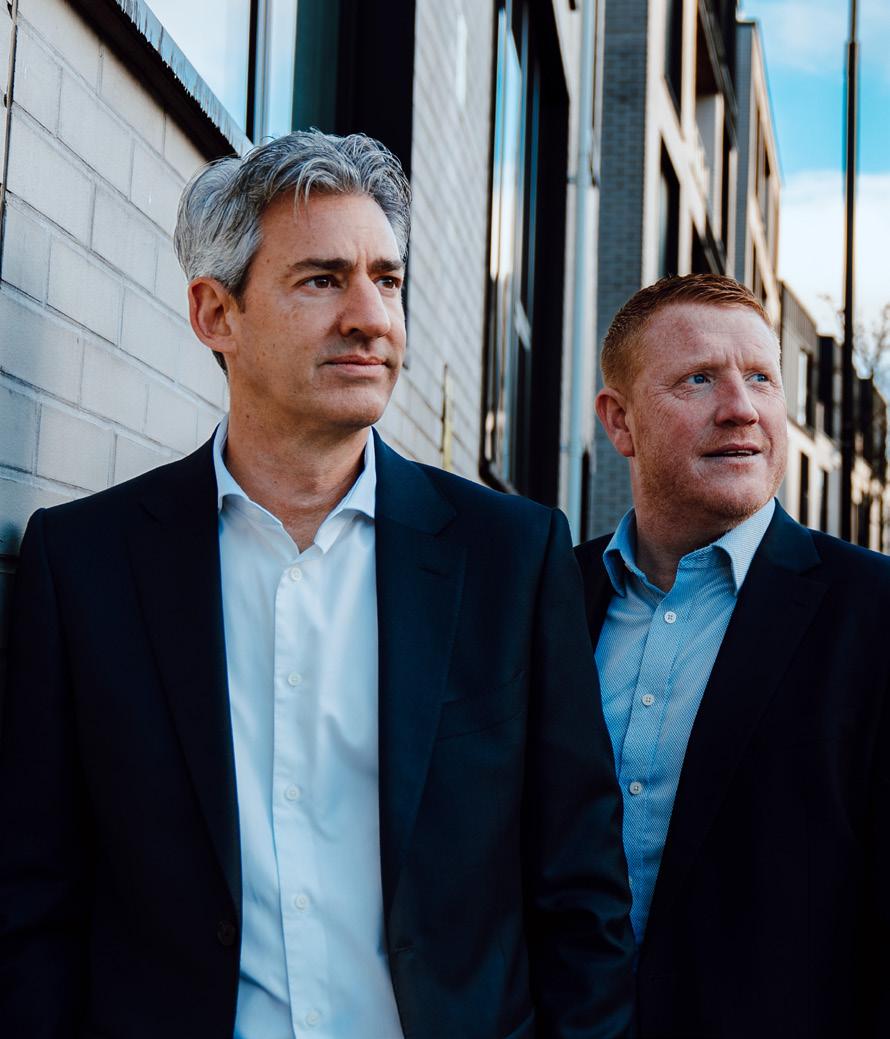
Octane Capital has grown its loan book and won three major awards in the past year. Jonathan Samuels, CEO, and Matt Smith, director of credit and risk, talk to us about access to underwriters, a lean team, keeping questions to a minimum and the power of the phone
Jonathan Samuels: 2025 was an incredible year for us as a business. We have surpassed £2bn of lending since launch in 2017 and, last year, added another £250m to our loan book and made some notable hires.
One of the things we’re most proud of is winning three major industry awards—Service Excellence at the coveted B&C Awards, Best Service from a Bridging Lender at the Business Moneyfacts Awards and Bridging Lender of the Year at the National Association of Commercial Finance Brokers Commercial Lender Awards. For me, I was particularly pleased that the judges repeatedly cited our underwriting function as the reason we were deemed winners.
MS: We consciously haven’t divided our team into multiple departments (for example case management, servicing or redemptions).
Matt Smith: Access. For our brokers, having direct access to our credit managers—the individuals underwriting their application—is paramount. We start every new application with a good old-fashioned phone call. The credit manager will introduce themselves to the broker and provide their direct contact details for future correspondence—no hiding behind emails. When the phone rings, we answer. And the person answering is a decision-maker.
Over the last few years, we’ve seen lenders in our space automating their processes, with broker portals, AVMs and AI integration becoming more commonplace. At Octane, we’re committed to introducing tech wherever we feel it will make us more efficient but, that said, I think it’s this human element that is most well received by our brokers.
It’s a lean structure, and deliberately so. The individual credit manager who underwrites the case will be the broker’s and borrower’s point of contact from cradle to grave. This includes all post-completion functions such as drawdowns (for refurbishment loans) and everything through to redemption. This singular point of contact allows for continuity and seamless communication. Credit managers are much better underwriters of risk when they are also responsible for servicing.
MS: It’s a balance between experience and attitude. We have 10 credit managers within our business. Their average length of experience in specialist lending is 16 years. Again, this was a conscious decision we made when building the team: quality over quantity. We’re a modestly sized company, which is surprising to some considering the volumes that we lend. But this emphasis on experience means our brokers can rest assured that the credit manager assigned to their case has ample experience in the underwriting of loans like their clients’. While experience is important, attitude is arguably more so. We hire people—across all functions in the business—who are kind, hardworking and have a commercial mindset.
“While experience is important, attitude is arguably more so. We hire people—across all functions in the business—who are kind, hardworking and have a commercial mindset”
“We have big, bold plans for this year. Our target is to double our loan book to £1bn, and we envisage increasing the team’s size to achieve it”
JS: In a way, our BDMs are the first line of credit. They need to understand the deal, be transparent with brokers as to what deals fit our lending appetite and structure these structure loans to best fit the client’s needs. The BDMs know the credit policy and lending appetite intimately; I believe that is one of our strengths. Also, our credit managers carry their own turnaround and completion targets, which aligns them with sales. This breeds a commercial culture within the team. When hurdles arise, they feel empowered and motivated to find a solution.
You completed some sizeable loans last year. What do you put that down to?
MS: Appetite and experience. We have strong appetite for loans in the £1m–£15m bracket and have set up the team to ensure we can deliver for our brokers. Within our credit team, we have established a structured finance sub-team, which we bolstered this year with the hire of Andrew Becker from Investec. That team are responsible for underwriting our larger, more complex transactions.
JS: We try to only ask the important questions, not the nice-to-have ones. We have a culture in credit of trying to make the journey to completion as easy as possible while asking what is needed. We are also very well known for our refurbishment product; this is an industry-leading offering because our team are experienced in underwriting loans with works facilities of up to £1m. That means understanding a complex schedule of works and asking the right questions. Borrowers and brokers also appreciate talking directly to the credit manager on those loans.
JS: We have big, bold plans for this year. Our target is to double our loan book to £1bn and we envisage increasing the team’s size to achieve it. Watch this space.
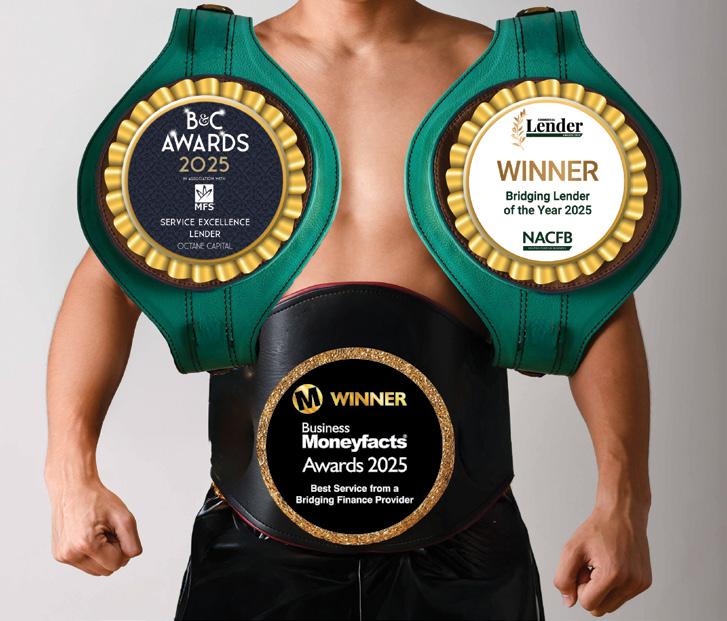
Rate cuts, political and economic shifts, greater surveillance and over-hopeful borrowers will all exert pressure on underwriters in 2026. Infallible underwriting will become non-negotiable
Words by
JEMIMA HAYES
Underwriting at large will be tested across the property market this year—there’s no getting away from the fact. Market shifts as well as regulatory scrutiny will force us all to adapt. Underwriters who are unprepared risk derailing crucial investment strategies. We need to play our part in keeping the property market afloat.
Solid underwriting is the backbone of a successful property investment journey. Our market moves hard and fast. Bridging loans often need to be delivered quickly and under risky circumstances. Without strong underwriting practices, it wouldn’t be possible for property investors to jump on opportunities. Nor would there be much hope for borrowers with less-than-ideal financial backgrounds.
It’s clear that underwriters will need to temper expectations over the coming months. Optimism is emerging and, after all the challenges we’ve experienced since (at least) the 2022 mini-Budget, better times should be welcomed with open arms. The tricky part will be ensuring that we don’t all get carried away about what’s achievable or even possible.
There’s one obvious catalyst here: rates. The wider financial markets expect more base rate cuts this year, with many forecasting it could fall all the way to 3.25%. Mainstream lenders already seem poised to jump on this optimism. A rate war, which kicked off in late 2025, only accelerated in the opening weeks of this year.
This could trigger a wave of refinancing activity over the coming months. This is understandable. If better, cheaper terms are out there, why
wouldn’t a property investor try to take advantage of them? But, as underwriters are well aware, if brokers and borrowers seek exits based on optimism rather than confirmable lender appetite, that adds additional risks to a case.
We need to manage this with our brokers—especially considering that 57% of them expect re-bridging deals to be the biggest opportunity in the bespoke sector in 2026, according to a recent survey.
Then there’s the macroeconomic picture to contend with. Last year, several political and economic shifts made the UK property market especially tempting for global investors. To highlight a notable example: American homebuyers sought UK assets to escape the “Trump effect”. Other challenges pushed global capital to our market from the Middle East and Asia.
Sadly, we were barely able to enjoy any days of peace before more global drama unfolded at the beginning of this year. Our property market could see even more influxes of intrigue from the likes of South America and Eastern Europe.
We all know that foreign nationals and overseas investors struggle to get far with high-street lenders. Bespoke providers are primed to help these investors but the underwriting capabilities need to be there. The focus must remain on identifying foreign assets, ensuring everything is legitimate and that solid exit strategies underscore every deal.
Looking at the broader picture, infallible underwriting is set to be a non-negotiable across the scene over the
coming months and years. This will be the case regardless of whether the borrower is based overseas, a seasoned UK landlord, a first-time buyer or anything in between.
Simply put, there is increasing scrutiny on the non-banking financial sector. A House of Lords financial services regulation committee report warned the UK Treasury has a “limited grasp” of concerns linked to shadow banking and private credit. Furthermore, the Bank of England plans to launch a private credit industry stress test that will map out potential risks linked to the sector.
Exactly how this will hit the unregulated bridging market remains to be seen. Regardless of that, if we are to experience more surveillance, the strength of our underwriting procedures will undoubtedly be among the first things looked at.
So what can we as underwriters do to ensure we’re ready for all of this? What do we need to do to protect both our own interests and those of our clients?
I’d argue that we must embrace the stories behind our deals. Yes, at a minimum, we must make sure the numbers add up. But, beyond this, we need to have a bit of vision.
Ultimately, our products are designed to help property investors reach new
heights. We are not delivering funding to an Excel sheet or a fact-find PDF
That residential loan isn’t just for a prime BTL asset—it’s going to bring more stock to an area in desperate need of options. At the end of its journey, it will allow more renters to access that vital market and contribute to its prosperity.
That refurbishment finance won’t just add a coat of paint to a commercial property. It will help bring an unloved business asset back to life, and allow entrepreneurs to expand and grow.
That first-time buyer isn’t just a case that needs additional due diligence. They are an individual who commendably dares to embrace a market that is facing numerous challenges yet still offers untold potential.
We owe it to our brokers and borrowers to try to find solutions wherever possible. As underwriters, we should be looking for reasons to lend rather than seeking out excuses not to.
To do this, let’s ensure we’re focused on the essentials in 2026. Let’s know the borrower’s details and background inside and out. Let’s get to grips with the exit strategy as soon as possible and make sure it’s realistic and evidenced. Let’s embrace collaboration so that everyone involved—accountants, legal teams, conveyancers, valuers, brokers—are all on the same page.
It’s time to roll up our sleeves. I can’t wait to see what’s on the horizon. Bring it on.

• Residential (incl. high-end single units)
• Hotels & Pubs
• Offices
• Industrial & Warehouses
• Care Homes
• Retail
Fast, flexible lending across both residential and commercial real estate, with loans up to £25m and terms up to 36 months including: w:
Words by DHUHA AL-ZAIDI
Competition in the bridging finance market has risen significantly. How can new brokers venturing into the space succeed, assuming there’s room for them in the first place?
In our first roundtable of the year, three intermediaries give advice for new brokers, looking at honesty, knowing your limits and why it doesn’t end when you get the deal in.
Stephen Burns established Stephen Burns Specialist Property Finance early in January, after 12 years spent in bridging, commercial, BTL and development finance, following his most recent position as a partner at Word on the Street.
Similarly, Craig Smith announced the debut of Carter Smith Property Finance early last December as an AR of brokerage VIBE Finance, the company where he started his career in specialist brokering before joining Shawbrook as a regional development manager.
The pair are joined by Tom Rowlands, managing director at Pure Property Finance, which has been operating since 2013, to discuss why brokers are best placed to help clients in today’s market, changing expectations and how that impacts new firms and to give advice for new brokers from years in the making.
Dhuha Al-Zaidi: What attracted you to start up your own firms or to become a broker in the first place?
Stephen Burns: If we’re talking individually, I was an estate agent for 25 years, sold my estate agency, and as I then had a few quid, I intended to retire. That was in 2004. I spent it all on the wrong things, going travelling the world and everything in between, so I needed to come back to work. I’ve been there, done that in the property world. Been an agent, been a developer, a borrower and a broker.
Borrowing money as a developer made me confident, I thought I knew how to do it, and there was a chance conversation with an old friend of mine who was setting up a brokerage. He was going on holiday for two weeks. I went in and we created Adapt Finance from there and the rest is history. I was in a fringe business, which was estate agency, and progressed into brokering. That’s it.
“Your commitment to the client is, for me, the most important factor. Not being a member of the NACFB or FIBA, albeit positive—just your commitment to the client and your knowledge of products”
Craig Smith: I think, from my perspective, it’s always been at the back of my mind a little bit. And, having been a broker and working on the lending side, it just felt like I had the right experience and, if I didn’t try now, I don’t think I ever would. I think now I’ve seen both sides of the industry. I’ve seen first-hand how credit processors actually review deals and how cases really need to be presented. From the lender side, you see good investors falling over simply because their case wasn’t packaged properly or the story wasn’t clear. Eventually I realised I could either keep watching that happen or do something about it and, hopefully, have some freedom and really make an impact myself, and go and do it myself properly. So that’s really what pushed me to start my own firm.
Tom Rowlands: Myself, I’ve been with Pure for nine years. My background was first accountancy and then into the IFA world. I was looking for a career change and a faster career pace. The property industry gave me that. But it was more, I guess, the founders, who I trusted and who trusted me as well, who convinced me about that career change.
DA: Is there genuinely room for new brokers this year or do you think the market is full?
CS: I hope so.
SB: We don’t sell a widget, we sell a service. I don’t even like “sell”. We provide a service. You can’t touch and feel what you get from us.
Customer expectations are higher than they’ve ever been. For me, all we can do is provide a better service. We’ve all got sourcing systems, relationships, products coming out of our ears, so you need the best team. If it’s Craig and I, it’s the best individuals who we can pull together and the best team. And you just need to offer the best service. Sadly, a lot of brokers are not offering that service and the clients aren’t aware that there’s better available.
Sometimes we get new clients by pure chance. We were talking a little bit earlier about when customers realise there is better out there. There’s loads and loads and loads of room for more brokerages. And, as more brokers come to the market, it will just potentially reduce the volume that the poor ones do. That’s the truth.
TR: There’s quite clearly a consolidation trend, whether at network or regional level. But I absolutely think there is room for new brokerages—for true advisory brokerages that can specialise in certain areas. It’s an overcrowded market of packagers, not true value-add brokers, so there is room, I think.
CS: I absolutely agree, Tom. It is oversaturated, for sure. I think if you’re just pushing transactions, then the market is probably full. But I do think there’s a big gap for truly specialised brokers who understand the niche and want to add real value. But I think investors just don’t want it right now. They want structure, strategy and more certainty. Yes, I think there’s definitely room, just not for the same thing.
TR: Agreed. If you can differentiate yourself, specialise, absolutely.
DA: Just to follow up on that, is there an area of brokering that is still underserved in the market, be it region-wise or certain specialities?
SB: I think brokers use the term specialist— and some lenders that aren’t specialists use the term specialist. Let’s just separate bridging; at the end of the day, it’s predominantly non reg. And we’re in a situation where 80% of the business that is done by lenders is by brokering only, by brokers. It’s a broker-led business, business to business.
If the public could go straight to every single lender, I think we’d do less because nobody likes paying a middleman. As I said, I was an agent for 25 years and we’re the second most hated occupation behind the taxman, we do nothing for it, blah, blah, blah.
At the end of the day, it’s all about having enough knowledge and bringing enough to the table to collaborate and work inside the client’s business so you’re a necessity rather than a forced entity.
And we are a bit forced. I’ve had leads from lenders saying, ‘We can’t do any-
thing for this client, we know you’re a good broker, will you do it?’ Tom’s view may be slightly different because part of his business is from comparison sites and things like that, Tom, isn’t it? Whereas the public are going direct in, looking for a deal, a lender, a broker. I don’t often think they know what they are looking for, do they, Tom, when they come in?
TR: Yes.
SB: And how many times have all three of us had to say: ‘I’m a broker, and this is what a broker does.’
CS: Sure.
SB: Brokers bring such a lot to a client’s army of professionals, but some don’t value that, and they will potentially go directly to lenders, again, using the lender Together’s model. Billions and billions are spent on property loans each year, with a lot of that being from direct clients.
DA: Does coming from outside traditional brokering help or does it hinder success?. Craig, I know you were on the BDM side. What have your experiences taught you?
CS: It’s helped because I can come in understanding how credit managers think and how they review papers. One big lesson I’ve learnt, and this is from both being a broker and from being on the lending side, is you can never hang your hat on a deal.
Deals consistently, naturally, take a different path once they’re under review. I think the real skill is trying to pre-empt matters as much as possible and communicating properly with the lender to find a solution when things change. But I do think collaboration between both parties is everything.
TR: From my perspective, a BDM swapping into a brokerage is great from a risk perspective and for understanding lenders, credit appetite and things like that.
Coming from outside the industry on the whole brings fresh perspectives, always challenging old habits. This is particularly so if you’ve got professional industries coming into the broker world who are often able to structure and understand a deal and how to present deals as well. I think that just adds something.
DA: Which skills do you think are overvalued in brokering and which are underestimated? Stephen, do you want to go first?
SB: It’s always me, isn’t it?
DA: I know, sorry. You just give great answers.
SB: I do witter on a bit, don’t I? I think the best broker I’ve ever worked with had worked for a lender. I think it’s a great grounding, whether it’s the credit processors, Craig or Paul, because they’re all different. And are some as honest as they should be, lending my own funds, our own funds, etc? We hear it so often but is it an actual fact? Is somebody further up the chain going to say no later on?
But, talking about skills, it’s wanting to be a part of the team. I’m not great at the phrases I come out with, but they’re not just a subcontractor, they have an accountant, they have a lawyer. We want them to have a broker. You can’t just have one lender because every deal is different. A vacant commercial in Glasgow and a beautiful residential scheme in Hampshire need different lenders and the broker needs to keep up to date.
I think the broker has got to be known, recognised and respected, and spent a lot of time with. My week since I launched has just been all BDM, BDM, BDM. And, obviously, I’ve had to refuse some because I’m never going to work with all of them. From the get-go, from 5th January, the guys are just driven to hit the targets, make the calls, make the visits, bring me lemon drizzle cake etc, etc.
“It’s great to have the options out there, but you need to navigate that with the lender, and that’s where the complexity comes”
Your commitment to the client is, for me, the most important factor. Not being a member of the NACFB or FIBA—just your commitment to the client and your knowledge of products.
TR: Yes. Not to repeat Steve and just to look at something else, we really, really focus on presenting a deal, assessing risk and liquidity in any transaction. Really just truly understanding credit appetite and being able to pre-empt some credit decisions as well. And that will really help you present and manage the risk of any deal. For me, a key skill is pre-empting credit appetite.
CS: Absolutely. I think speed is actually overrated and overvalued. Some lenders will dress it up as having a certain relationship, whether it be strategic partner status or some kind of service, when actually the processes are pretty much the same, no matter which way they come in. I think that speed is overvalued and should be a given.
CS: I think what is underestimated, like you said, Stephen, is a relationship with the BDM, because product guides can state that a lender will consider something at maybe 75%.
But, in reality, and from being on the inside, it can be restricted, depending on the level of lending on that particular security type. I think knowing your lenders inside out and being in contact with your BDM and having an honest conversation is far more valuable than firing out quotes.
SB: I’m the oldest among us, and that doesn’t mean I’m the most experienced, but I’m also always learning. A client may call and say, I’m buying a property for £1m, what can you do? And we go back and say, oh, we can get
you £750,000.
And you spent a day on it, you’ve chatted through a couple of lenders and the client says, I’ve only got 42 grand. It’s a skill to ascertain whether that client is able to do the project that they’ve presented to you and one I’ve only recently adopted.
And it might sound crazy, but I see brokers who are classed as very good with first-timers, people who have never bought before, first projects etc. And some brokers don’t want to hold that hand so they will only work with people who understand what Japanese knotweed is or what a local search is, because not everybody does.
Brokers, even in the specialist market, can specialise within a speciality. As I say, I’m bridging, refurb, dev, BTL, the commercials and everything else are very much secondary to me. My absolute ideal deal is a bridge, a refurb or a residential development.
DA: What do clients expect more of now than they did a few years ago? And, in turn, how are your firms preparing to advance this year?
SB: This is one for Tom, because I think the answer to that is tech, ID verifications, CRMs integrating. I’m the old fart, so I would say Tom’s probably more in tune with this than Craig or I. Excuse me, Craig, I might be wrong about that.
CS: I agree. I agree. No offence taken.
TR: We spent 2025 and prior to then as well, working on our CRM, looking into tech. And I think that really lends itself to streamlining a client’s experience, client interaction for consumer-led and regulated products that are looking for the light touch; for example, you can apply for an unsecured loan without any interaction whatsoever. People are looking for that real light-touch approach. On the other hand, we’ve got our dev, bridging and refurb sides which are the opposite. It’s still slightly more old fashioned and borrowers are more educated. I think that’s the key. Over the past five years, borrowers and consumers alike are more
educated, so they’re looking around. What we’re offering is scenario testing. And that’s dressed up a little bit, but it’s presenting numerous lender options. This is perhaps your quickest. This is the most deliverable. This will get you the most loan. Scenario testing, giving developers options. But yes, tech is a big one also.
CS: I don’t know about you, Stephen, but I’ve spent the last few weeks really trying hard to embrace technology and get ahead of as much as possible, because it’s going to really help businesses like ours. It is so important for us to embrace it as much as we can do.
SB: Oh, I think it is.
CS: Because I’ve seen firsthand that lenders are doing the same thing on their side, so should we.
SB: Yes. And honestly, being younger helps because you’ve been brought up on it, so to speak, but I do think tech is important, and I haven’t been behind that door for too long. I agree, Craig, you’re starting out, I’m starting out, but I’ve only changed the place I sit. At the end of the day, I’m still doing the same job I was doing before Christmas.
As you grow and potentially more brokers join you—case managers and others in the team—that tech, it rolls out, as Tom says, and it can be a different tech in a different department for a different requirement. I never want a computer to tell me what to do.
I think what I’m trying to say is that sourcing systems in the reg world are really, really important. There can be a rate change at nine o’clock, and it can be live at one minute past, and the guys can miss out.
But in our job, it’s more relationships. Keeping in touch. BDM calls you and says, we’ve just pushed our LTV to 77.5%, and understanding that, and recording it, and mix and matching. I’m not a BrickFlow kind of guy, but should I be? And I’ve got to
“Brokers, from the day we start to wherever in their careers, we are evolutionary”
open myself up to things like that because do I not offer the client the perfect service because I’m unaware of a product? That’s a concern for those who fail to embrace tech. Then again, if I consider the products that I’ve sourced that I know will fit the triangle—Tom mentioned cost, deliverability and speed—even though you can’t ever seem to get every point of the triangle, if you want something to complete for Friday, you might not get the cheapest cost. Lender panels, whole of market and various regulated terms don’t really apply in specialist lending, but you should be as whole as you can. Agree, guys?
CS: Agreed.
TR: A part of the tech rollout was giving clients the option to say how they want to communicate as well. We’re offering WhatsApp, SMS and telephone and video calls. I think that’s really important. And that lends itself to a multidisciplinary brokerage like Pure. Different products have different behaviours. Different customers within those products have different behaviours and want to interact differently as well.
DA: Is it fair to then say or ask that new brokerages that are coming out will only succeed if they actually have that technical advantage? Is traditional brokering still appreciated in today’s market or do you have to be quite technical and advanced?
TR: I think it’s a balance. I think traditional relationships are always going to be there, and they are what set us apart. But there are certain elements of tech we can definitely embrace to help us out with our day-to-day activities. It’s relationships that a computer can’t control or manage that are absolutely vital.
SB: I see age as a negative sometimes. If I send a fact-find to a client, that may be, say, four pages, a lot of my clients will, first of all, not be able to print it off to fill it out, so they go to the Post Office. They get to the Post Office to print it, go back home, lose a page, fill it out. Take a photograph of it showing their feet wearing flip-flops and send it back to me on WhatsApp. Wow.
It’s taken four months. They’ve lost the auction purchase and none of us have earned a bloody pound.
Tech is good on things like that. Tom just invested tens of thousands of pounds. What brokers know is the lender that they’ll eventually choose will have some form of ID verification. If they don’t have it, they can utilise the services of others, so you can do tech by proxy.
I don’t think it will take over but I think, if you’re not using it at all, it’ll come to get you very soon. But, as Craig said, we’re relationship driven. I seen the use of WhatsApp over the last two years go through the roof. They can send documents through it, photographs through it, dah, dah, dah. And I’m not saying it’s just become
secondary to email but it’s certainly equal to it at the end of the day. I think you have to embrace it but I don’t think you’ll fail without it.
DA: What’s harder about running a brokerage than most people realise?
CS: I feel like a little bit a cheat answering this question, really, because my business is relatively new. There’s definitely been a hell of a lot more to setting up than I initially thought there would be. I wouldn’t say I was naive coming into it, but I’ve really enjoyed creating a brand and embracing that.
I don’t know about you guys but, now I’ve seen it on both sides, I think chasing is a very delicate subject. You’re chasing wherever you can, whether it be solicitors, lenders or clients, but you do have to allow certain parties a bit of time and space to do their bit—in fact, if you push too hard, relationships can suffer. And I’ve seen reputation can suffer in the long run as well. If you don’t push enough, the deal stalls. So finding that balance on both sides for me, initially, was tough.
SB: Just ring them every hour. No, you’re right. Craig, I think there’s a really good word—I love certain words—and I think that word is meaningful. If you’re calling to get meaningful information, to give a meaningful update to your client. As an example, to me, a chase would be: “Hi, we’re waiting for searches.”
We put the phone down. We could ring them every day for the next six weeks but, instead, we just say, ‘Absolutely no problem, when are they expected back?’ and they say, ‘Oh, they’re due back on the 15th,’ so we can call them on the 16th or the 17th, not every day in between.
I think if you’re calling for a meaningful update and the person you calling gets that, it works really well. But I agree with Craig; especially when you’re chasing your early business, you want to impress the client and you want to get some stuff in your pipeline, don’t you?
CS: Yes, absolutely.
SB: But I have worked with an individual who was an over-chaser, and it just drives you up the wall.
TR: It’s perhaps the most enjoyable bit, managing existing relationships, continually keeping in touch. And Stephen touched on it then—it’s just filling that pipeline through relationships.
SB: Yes. I think of my little favourite sayings and, again, I’ll link with Craig on this; it can be lonely. I’ve chosen to take an office and not work from home. The office is 40 minutes away. It’s been minus eight all week and it’s an hour and a half away, but I’d rather get in the car and come.
But you’re sat in an office. It’s empty, bar from you. When you’re used to being in a very busy environment, and you might sit here for eight hours because you want
to feel like you’re doing it and putting the effort in and it can feel happy.
I think you’ve just got to set yourself some goals—realistic goals. I have a target. It’s an annual target, which you can divide by 12 and get a monthly target. But you might not do that in the first month, in the first two, three or four. You’ve just got to be patient and keep grinding, I think. Craig, don’t you?
CS: Yes, absolutely, patience is definitely the word, for sure. It takes time.
SB: You’ve got three different set-ups here. You’ve got me who is me. You’ve got Tom, who’s verging on packager, with quite a large organisation with multiple disciplines. And Craig, who’s AR. Regarding loneliness, you could argue you can speak to the team at VIBE, Craig?
“You’re seeing lenders that were quite vanilla back when I was brokering that have gone into semi-commercial and commercial markets. It’s a great thing—there’s a lot more choice out there for investors”
CS: Yes, I can lean on them for a bit more support, for sure.
SB: I would more ring Craig or Tom for support, just as a fellow broker, whereas they internally can potentially get that support.
TR: That’s a fair point.
SB: It’s good to have guys so that I’m not just going to ring Craig, and say, “Craig, you’ve worked at Shawbrook, but what’s the process?” or “Craig, I’m stuck. I’ve got a case. It’s not just all about work. Help.” Sometimes I might just want to ring him. I might just want to ring him and say, “How are you finding things?”
I don’t want him to lie to me, ‘Oh, yes, I’ve done £27bn.’ I want him to be honest. And we do fluff our feathers sometimes to each other, don’t we, at these corporate dos and stuff like that. Potentially, there’s some anxiety in there. And it’s good that the world has become a better place; you’ve got three men here to be able to openly talk about anxieties and worries and highs and lows.
CS: Yes, that’s well put, Stephen. Absolutely.
DA: When you guys look at where brokering is heading this year, what makes you optimistic and what still worries you?
TR: I think I touched on it earlier. We’re finding borrowers and sponsors more sophisticated, which is a real positive. That is going to drive the standard of advice, and the better brokers will thrive because of it. That was my optimism.
CS: I think my optimism would be about the level of options there are out there for investors now. You’re seeing lenders that were quite vanilla back when I was brokering that have gone into semi-commercial and commercial markets. It’s a great thing—there’s a lot more choice out there for investors. But it does worry me slightly that there are going to be more choices and more complexity. That’s where the really good brokers are going to earn their keep, really helping the clients navigate through that journey properly, especially where some
lenders may be new to certain markets. I think it’s great to have the options out there, but you need to navigate that with the lender, and that’s where the complexity comes.
SB: The opportunities I see: I had lemon drizzle cake yesterday and I’ve had flapjacks today, so there’s a massive opportunity to eat for free. No, on a serious note, my only tip to new, young brokers who have never done it before that completion is about the start, the real start, of the relationship.
If it’s a bridge, it has to be repaid. If it’s a refurb, it has drawdowns. If it’s a development, the same. And if you stick with that client, if you help them through the whole process, then they become a repeat borrower.
You can complete, get your fee and move on, which some do, seriously, some do. I was talking to a lender yesterday who, up until middle of last year, inspected everything he lent on. Up until about COVID, we stood on the ground of everything that we ever did a case on. And that took some miles, some hours, some overnight stays, some scabby hotels, some truck stops. Can’t talk about truck stops.
At the end of the day, it’s trying to balance that and, going back to a previous question, tech helps that. We’ve got Google Earth, we’ve got AVMs for valuations and things like that. We don’t have to be as mobile as we used to but, as brokers, we’ll go Aberdeen down to Cornwall—it’s a big geographical area us guys cover. We don’t go into Wales, obviously, because it’s a bit rough LOL!
Tech has helped but being with the customer on all his journey is harder when you’re a new broker because you’ll earn your money at the front end and you want to give all your concentration to the front end, but you’ve got to give a proportion to the term. And you’ve got to have the ability to be able to do that if you want that customer back. Tip of the week.
DA: Given your experiences from different sides, what advice would you give someone considering entering the industry right now?
CS: I think when I first started, I was getting just volume, anything I could get hold of, really, picking up some pretty low deals. Looking back, I would say don’t be too scared to go after the larger and more complex deals, because they are out there. Without a doubt, learning at VIBE under Kim [McGinley], director and specialist broker, learning involved throwing myself into deep end into those deep conversations early on. And do you know what? If you don’t know something, just be completely honest and say you’ll come back on it.
I think when I look back now, I’d probably agree to things that maybe I didn’t 100% believe, back then, but it’s different now. Of course, you have to be competent but it’s far, far better to be honest and dou-
ble-check than overpromise because, if you overpromise, I absolutely assure you, it will come back to bite you further down the line, and it will come out.
I think overpromising might win you the conversation and maybe get you the deal in, but it may cost you that trust and that relationship. And this industry is all about trust: you break that and your client will go elsewhere.
SB: Yes, spot on. Brokers, from the day we start to wherever in their careers, we are evolutionary. We’ve all been put in a pigeonhole of do a bridge first, then there’ll be a refurb, then a develop, so what Craig said was spot on. If a complex deal lands on your desk, don’t think, ‘I’m not ready for it,’ just sit back and see what you can do.
If you can’t do it but your relationship with the client is strong, collaborate with somebody who can. If I want, I can ring Craig or ring Tom. And there are only three of us on the call, but there are hundreds and hundreds of brokers, and I think I probably have a good relationship with a couple of dozen.
Collaborate and help that client because that’s what you’re employed to do. That client isn’t bothered whether Tom Rowlands, Craig Smith or I source that lender, they just want that LTV in that timeframe at the best cost we can find it.
TR: Yes. I think with any profession, you can be perceived as interchangeable. And, if you’re giving the same service as the next, you’re not truly demonstrating your value in understanding risk or how to present a deal. You can be perceived as interchangeable, so be confident in what you’re doing and really understand the deal and you’ll get it done.
Brokers will compete for the annual Colenko Cup at Flight Club in Shoreditch, London. This is an actioned fun packed afternoon with drinks and food buffet provided. Meet the Colenko Team and compete for prizes on the day!
Sisters In Property (SIP) has launched a new book club to bring together the property industry’s hidden bookworms. Scan the QR code to join the WhatsApp group and start connecting to let your imaginations run wild.
2pm-5pm 1:30pm–9:30pm 7:30pm
Shazad Ahmed invites you to The Elan Social presents Good Vibes Only evening on Thursday 5th March at The Broadcaster in White City, London. Real investors, developers and landlords all looking to elevate their personal brands, raise finance, and grow their portfolios. Tickets to be purchased online.
The B&C Awards will be hosted with a glamorous 1950s drive thru theme on Thursday 4th June at The Willows, Ilford. The daytime event runs from 1:30pm–9:30pm, with easy access via parking, taxi drop-off, overground, and the Elizabeth line. Voting opens 2 February and closes 17th March, with limited online voting available via the awards website. Polish those dancing shoes—it’s all hip shakes, smooth spins, and vintage grooves all afternoon!
TAB has booked the Electric Cinema on Portobello Road, London for an invite-only screening of the 2026 World Cup opener match: England vs Croatia, starting at 7.30pm, with food and drink flowing.
The Medianett Gala marks our rebrand of the year. With a Midas Touch theme—because everything we touch turns to gold—guests are invited to dress in black tie with a hint of gold. As our flagship news websites rebrand in April, this exclusive reveal offers a first look at our bold new vision. Date and venue released in coming weeks, keep an eye out on Bridging & Commercial.
Medianett Publishing will host its first ever invitation-only Directors’ Retreat at a luxury abbey in Paris on 6th May—exclusive to select Premium Partners. Guests will be treated to a three-course dinner, industry roundtables and educational talks, and a game of Traitors...
The annual MT Finance Football Festival is back at the iconic Tottenham Hotspur Stadium. Expect high-stakes matches, incredible energy, and industry networking. Stay tuned for details and follow MT Finance socials for the latest updates.
Brokers will enjoy the evening’s racing, including the Colenko Fast Track Maiden Stakes, from the comfort of a trackside box. The event will include a full three course dinner, followed by trackside entertainment. 4pm-10pm
Colenko will be hosting a golf day at the prestigious Moor Hall Golf Club, bringing together brokers and colleagues for a day of competition, networking, and hospitality. Guests will enjoy excellent playing conditions on the championship course, followed by a three-course lunch in the clubhouse.
Medianett Publishing’s annual FP Show returns on 6th November at Olympia London in Kensington for another year of industry networking. Following last year’s record-breaking turnout, this year’s event promises to be just as impactful, only slightly more iconic.
January brought a fresh start for Mia House, who joins Maslow Capital as originations director, having worked at Century Capital and Hampshire Trust Bank. She delves into what she’ll bring to her role, making deals work and “Mia House energy”
How will you apply your experience in your new role?
I like to keep it simple. I always put the client first, which involves being reliable, consistent, trustworthy and efficient. Over the past decade, I’ve worked across multiple market conditions, lender models and deal types, so I understand what brokers and borrowers actually need to get term and bridging transactions over the line. At Maslow Capital, I’ll be applying that experience by focusing on clarity, speed and certainty of execution, particularly on complex deals. I’ve learned that strong relationships and honest conversations are just as important as competitive pricing..
What will your role entail, and how will you prepare for client and broker liaison?
My role is centred on building and strengthening relationships with brokers and clients, identifying opportunities and ensuring deals are structured efficiently from the outset—Maslow gives clients more than one option and a lot of flexibility. Preparation involves understanding a broker’s business model, a borrower’s end goal and the pressure points in a transaction before they become issues. I’m very hands-on and proactive, and I see myself as an extension of a broker’s team rather than just a funding source.
How is Maslow Capital’s approach to lending different?
Maslow Capital is pragmatic, with an emphasis on understanding the asset, the story behind the deal and the borrower’s strategy rather than relying on criteria. The credit process is robust but commercial, which allows the team to move quickly without compromising on risk discipline. We understand
Have you ever made an impulse purchase you regretted?
Too many to count, to be honest! An Apple watch could be the next.
the opportunities bridging creates and want to collaborate with clients more than other lenders. Maslow doesn’t have the restrictions of a bank. It has a strong base with regards to funding, opportunities beyond the UK and an experienced, driven, approachable team.
Why do lenders lose deals—and how can your team win more?
Deals are most often lost through slow responses, unclear communication or a lack of flexibility when circumstances change, which they almost always do. Maslow wins deals by being decisive, transparent and consistent. Bridging is incredibly competitive, and you need attractive pricing, flexible criteria, approachable and experienced underwriters and quick decisions.
What trends are you seeing in borrower behaviour?
Borrowers are far more cost aware and strategic than they were a few years ago. We’re seeing increased demand for shorter-term, flexible solutions while borrowers wait for market conditions to stabilise.
How do you see the bridging market evolving?
I expect the market to remain highly competitive, but with a greater focus on quality over volume. Experienced lenders who can move quickly and handle complexity will stand out. Bridging will increasingly be seen as a strategic tool rather than a last resort, particularly for professional investors and developers—lenders need to keep up with this and be more creative.
What is “Mia House energy” and how will you channel it?
“Mia House energy” is high energy, relationship driven and relentlessly solutions focused. I bring drive, positivity and accountability to everything I do. This year, I’m challenging myself to push beyond my comfort zone, taking on more complex transactions, building deeper broker partnerships and contributing to Maslow’s growth. The Mia House energy hates losing more than she loves winning; if I can get a deal to work, I will.
What books have you read that you think everyone should read?
Principles by Ray Dalio, Atomic Habits by James Clear, Happy, Sexy, Millionaire by Steven Bartlett, Stolen Focus by Johann Hari and The 50th Law by 50 Cent and Robert Greene. I love my books so recommendations are welcome.
What’s a tradition from your childhood you cherish?
My father has his own small business. He installed in me that, no matter where I go, how big or small a company is, you treat it as if it’s your own business. I cherish this massively as it’s got me where I am today.
I highly value that slow, blissful, relaxed Sunday vibe with a roast dinner as a tradition. Summer, spring, winter or autumn, if it’s Sunday, I’m having a roast.
What changes are you most excited about?
I’m excited to work for a big-scale lender that hasn’t got the restrictions a bank has. I’m excited to help refine and expand Maslow’s bridging business, streamlining processes, enhancing broker engagement and continuing to build a reputation for certainty and delivery. As the business grows, there’s opportunity to scale without losing the personal, commercial approach— it’s that Mia House energy again.
Low rates. Dedicated team. Keep the ball rolling.
To find out more, call 0800 116 4385.
Intermediaries only.