Financing the future of connectivity
A strategic playbook to compete with China and close the digital divide
By Kenton Thibaut and Jochai Ben-Avie
The Digital Forensic Research Lab (DFRLab) at the Atlantic Council is a first of its kind organization with technical and policy expertise on disinformation, connective technologies, democracy, and the future of digital rights. Incubated at the Atlantic Council in 2016, the DFRLab is a field-builder, studying, defining, and informing approaches to the global information ecosystem and the technology that underpins it.
The Democracy + Tech Initiative creates policy practices that align global stakeholders toward tech and governance that reinforces, rather than undermines, open societies. It builds on the DFRLab’s established track record and leadership in the open-source field, empowering global communities to promote transparency and accountability online and around the world.
Cover photo credit: Kamran Abdullayev
ISBN: 978-1-61977-606-7
Edited by Layla Mashkoor.
© 2026 The Atlantic Council of the United States and Wisteria Strategies. All rights reserved. No part of this publication may be reproduced or transmitted in any form or by any means without permission in writing from the Atlantic Council, except in the case of brief quotations in news articles, critical articles, or reviews.
Please direct inquiries to:
Atlantic Council
1400 L Street NW, 11th Floor Washington, DC 20005
June 2026
Author
Kenton Thibaut is senior resident China fellow at the Atlantic Council’s Digital Forensic Research Lab (DFRLab), where she leads China programming for the Democracy + Tech Initiative; she is also a Senior Fellow at the Scowcroft Center’s Indo-Pacific Security initiative.
Jochai Ben-Avie is an international leader in tech policy, an award-winning impact investor, and a strategic advisor to foundation and executive leaders. He is the Founder of Wisteria Strategies, a Non-Resident Fellow at the Atlantic Council, and was previously the Co-Founder and CEO of Connect Humanity, the Head of International Policy at Mozilla, and the first Policy Director at Access Now.
Executive summary
Billions of people live without access to the internet. Far from simply a development issue, connecting the unconnected has become a central arena of geopolitical competition, with longterm implications for national security, economic growth, policy, and control over digital infrastructure.
The People’s Republic of China (PRC) has recognized this reality and has placed digital infrastructure investment at the core of its global strategy. Through state-directed financing, bundled technology offerings, and sustained engagement, China has positioned itself as the dominant provider of telecommunications infrastructure in large swathes of the Global South. This approach simultaneously advances China’s commercial interests, enhances its surveillance capabilities, and supports its broader ambitions for technological strategic advantage. By contrast, the United States and its democratic allies have approached connectivity investment in a fragmented and under-resourced manner. Existing efforts have tended to focus on large-scale, upstream assets such as submarine cables and big tower deployments, or narrow technology interventions, while leaving the challenge of last mile connectivity largely unaddressed. Despite possessing powerful tools—particularly development finance institutions (DFIs) armed with blended finance mechanisms—democratic governments have yet to deploy these capabilities in a way that can credibly compete with China’s model.
This report argues that connectivity represents a decisive and still underutilized entry point for countering China’s digital influence while advancing economic and strategic US objectives. It outlines why markets alone have failed to close the digital divide, why replicating China’s state-led approach is neither feasible nor desirable, and why blended finance offers a comparative advantage. Ultimately, we argue that success will depend on democratic governments rethinking what connectivity itself means. Building digital infrastructure is not an act of charity or a narrow effort to expand access. It is a strategic effort to shape the future architecture of the global internet, including who governs it, how data flows across it, and which political and technical values are embedded within it.
Drawing on four targeted Chatham House roundtables, two public panel events, policy research, and dozens of expert interviews from October 2024 to May 2026, the report presents a practical playbook organized around five pillars: reforming the US International Development Finance Corporation, building enabling environments, building markets, catalyzing capital, and working with allies. Together, these recommendations offer a road map for mobilizing public and private resources at scale to expand connectivity while reinforcing an open, interoperable, and rights-respecting internet.
Core points are summarized below by pillar:
DFC reform and financing strategy
y Enshrine closing the digital divide and mobilizing private capital explicitly in DFC’s mandate, priorities, and incentives.
y Increase DFC’s risk appetite and willingness to provide concessionary capital and credit enhancements including providing lower-cost capital, first-loss positions, guarantees, and political risk insurance.
y Encourage and incentivize DFC staff to take a more active role in facilitating deals across the investment life cycle.
y Build dedicated connectivity finance expertise and leverage private-sector knowledge through federal details (i.e., assignments for detailees).
y Expand early-stage technical assistance to improve investment readiness and support pipeline development.
y Shift investment toward community-focused internet service providers and specialized intermediaries.
Enabling environment
y Provide grant funding to expand and maintain open telecom data mapping, and advocate for public disclosure of telecom infrastructure data and adoption of common standards.
y Require reporting of infrastructure data from publicly financed projects.
y Use domestic policy tools to promote open telecom data standards globally.
y Fund regulator capacity building to support more conducive policy.
y Use diplomatic engagement to support pro-competitive regulatory reforms.
Market building
y Support three to five specialized intermediaries to source, structure, conduct due diligence, and manage investments while providing technical support, aggregating capital, and making appropriately scaled investments.
y Pool capital through intermediaries to reduce fragmentation and lower transaction costs.
y Provide grant funding for pipeline development and pre-investment technical assistance
y Deploy demonstration capital to validate models and inform larger-scale investment.
Capital mobilization
y Adopt a blended finance approach to catalyze private-sector investment.
y Use concessional capital to shift risk-return profiles and crowd in private investors.
y Expand use of guarantees and political risk insurance to reduce the cost of capital.
y Pursue coordinated structures to provide holistic capital support.
y Prioritize fiber deployment for durability, capacity, and long-term cost efficiency.
y Explore innovative financing structures for infrastructure, particularly revenue-based financing.
Allies and international coordination
y Encourage allies to contribute capital and pool resources through global or regional funds.
y Coordinate with partners and DFIs to align financing tools and investment strategies and leverage existing coinvestment partnerships where possible.
y Treat allied coordination as a central component of connectivity strategy and engage allies to share lessons learned, coordinate approaches, expand intelligence sharing, and address capacity gaps.
Diplomacy and strategy
y Elevate connectivity as a diplomatic priority in bilateral and multilateral engagement.
y Embed information and communications technology (ICT) financing within broader diplomatic and regional initiatives.
y Empower the State Department’s Bureau of Cyberspace and Digital Policy with a mandate and resources.
y Train diplomats to identify and advance connectivity opportunities.
y Adopt a whole-of-government approach and align diplomatic, financial, regulatory, and intelligence tools.
Multilateral and convening mechanisms
y Support multilateral efforts to develop global connectivity financing mechanisms.
y Support the World Summit on the Information Society (WSIS+20) working group to design financing systems.
y Launch a global connectivity finance conference to mobilize capital and coordinate stakeholders.
Connectivity as a strategic domain
Digital connectivity has become a foundational input to modern economic, social, and political life. Reliable internet access enables participation in global markets, delivery of public services, innovation, education, and civic engagement. Yet nearly half of the world’s population remains unconnected or poorly connected, with gaps concentrated overwhelmingly in low-income and rural communities across the Global South.
At the same time, those who will build, operate, and control internet connectivity gain an unparalleled window into the data flowing over those networks, often with the technical ability to manipulate those information flows, operational control over the lifeblood of the digital economy, and a competitive advantage for associated companies. The flipside of these tremendous economic, political, and strategic opportunities is profound national security risk if an adversary gains control over vital internet infrastructure.
China’s leaders believe the country can gain a strategic advantage by dominating the financing, building, and ultimate control over digital infrastructure abroad. Closing this divide presents major economic and strategic opportunities for the United States, opening new markets for US firms, generating returns for American investors, and ensuring that American technological leadership, rather than China’s, shapes the future digital economy.
The scale of these opportunities is substantial. Global demand for internet infrastructure represents hundreds of billions—and potentially more than trillions—of dollars in contracts and investment opportunities. The International Telecommunication Union (ITU) estimates that $2.6 trillion to $2.8 trillion will be needed to connect everyone by 2030. Boston Consulting Group similarly calculates more than $2 trillion in investment capital would be needed to connect two billion people. While financing this buildout could generate billions in investment returns, the macroeconomic returns may be greater. The World Bank finds that a ten-percentage-point increase in broadband penetration boosts growth in gross domestic product (GDP) per capita by 1–1.5 percent. Add to this figure billions more in annual service revenues from newly connected populations, and a vast expansion of the global customer base for US technology and online service providers.
Beyond these economic gains, however, control over the global buildout of internet infrastructure carries profound strategic significance. The Chinese government clearly recognizes this reality, which is why digital infrastructure investment has become a centerpiece of its Digital Silk Road (DSR) initiative. On the African continent alone, China now spends more on internet infrastructure than African governments, Group of Seven (G7) countries, and multilateral institutions combined. While the priorities of the DSR have evolved over time, connectivity infrastructure has seen sustained, consistent investment growth. PRC policy banks have provided billions of dollars in financing
to Chinese-owned, state-backed, or affiliated firms to build digital networks abroad.
China’s involvement in digital connectivity also serves its goals to facilitate flows of telecommunications data abroad for security purposes. For example, a Strauss Center report by Sheena Chestnut Greitens, Rana Siu Inboden, and Adam I. Klein outlines the spread of Huawei “Safe City Solutions” in countries along the Digital Silk Road. The Safe City program often builds on China-provided infrastructure and serves as a data integration platform that “collects, integrates, and analyzes data from a wide range of sources, from existing government records to facial-recognition-enabled or license-plate-recognition-enabled cameras.” This data can be leveraged by the PRC for dual-use purposes—including, for example, supporting signals intelligence and surveillance capabilities abroad via the telemetry, tracking, and communications data gathered on these systems. This has been supported by real-world cases: for example, a Le Monde report from 2018 found that the China-built IT network at the African Union headquarters was sending confidential data daily to the PRC for five years, from 2012 to 2017.
In recent years, the PRC has taken significant steps to improve the integration of telecommunications data from abroad with domestic PRC sources. These include building international data processing hubs in existing free trade zones to facilitate the circulation of data from international markets, supporting PRC telecommunication companies to establish “international telecommunications gateways” specifically for the purpose of integrating telecommunications data from abroad with domestic datasets, and actively partnering with countries along the Digital Silk Road on mutual recognition of standards to promote “data infrastructure interconnectivity” between the PRC and recipient countries.
Despite the significant benefits to the United States, investment in connectivity remains an underutilized avenue for economic and strategic gain. The current state of the debate has focused largely on communicating risks of relying on China-financed, state-linked telecommunications technologies, such as 5G technologies provided by Chinese firms Huawei and ZTE, or efforts to promote open-source alternatives like OpenRAN. While both lines of effort may be worthwhile, they do not provide a scalable, credible alternative for the vast majority of China’s telecommunications customers in the Global South. Finally, while many have long believed that market forces alone would connect everyone, the persistence of the global digital divide reflects a structural market failure. Extending high-quality connectivity to low-income, sparsely populated, or geographically challenging areas is capital-intensive and often generates returns below the thresholds required by commercial investors. The cost per user rises sharply in rural and remote areas due to low population density, difficult terrain, and limited existing internet infrastructure assets. The perception
of the lack of limited commercial viability has been driven by the cost models and profitability hurdles of the largest telecom providers and not the smaller, more community-focused ISPs that roundtable participants repeatedly highlighted as offering better service and being substantially more capital efficient while being less understood by capital markets and development finance institutions. As a result, private capital has proven insufficient to meet global connectivity needs, even as demand for digital services continues to grow.
This convergence of market failure and strategic competition has elevated connectivity from a development challenge to a core national security concern. Decisions about who builds and finances digital infrastructure today will shape the future information environment, technological capabilities, and geopolitical alignments for decades to come.
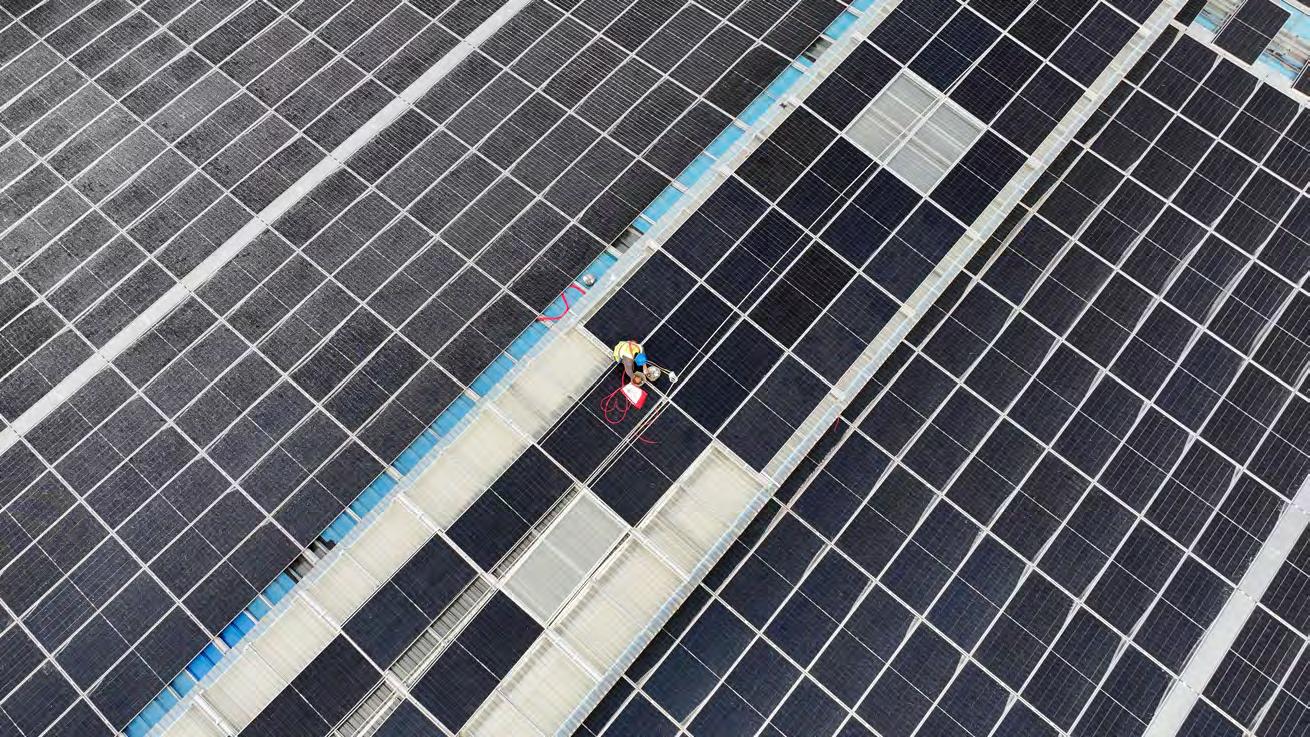
Construction workers install photovoltaic modules on the roof of the factory building of Jiangsu Beijiali Machinery Technology Co., Ltd. in Hai’an Industrial Park, Jiangsu Province, China, on April 1, 2026.
China’s approach to financing global digital infrastructure
China’s approach to financing global digital infrastructure rests on a model that is deliberately integrated, politically purposeful, and tolerant of inefficiency in service of long-term strategic goals. At its core, this financing structure is supported by two parallel mechanisms: internal and external subsidies.
The PRC’s strategy toward international connectivity begins at home. The PRC government has developed an expansive strategy and set of capabilities to facilitate Chinese companies like Huawei and ZTE to build networks abroad. Chinese policy banks—most prominently the Export-Import Bank of China and the China Development Bank—play a key role in subsidizing and facilitating Chinese companies to build abroad. Likewise, local governments in China have strong incentives to support the overseas expansion of state-owned enterprises (SOEs) and digital firms due to fiscal pressures and structural imbalances in the domestic economy. China’s growth model has long relied on investment-heavy industrial policy, which has generated persistent overcapacity across multiple sectors, prompting firms to seek external markets to absorb excess production.
In terms of external subsidies, policy banks also play a key role. In addition to helping source and broker deals, state banks provide a wide range of financing tools to foreign government partners including concessional loans, guarantees, and debt restructuring. This financing lowers production and operating costs, allowing firms such as Huawei and ZTE to offer equipment at prices significantly below competitors, with a European Commission investigation finding instances of underbidding by up to 70 percent. This combination of internal and external subsidies and substantial support throughout the deal life cycle allows Chinese-backed entities to provide financing at lower rates, allowing them to win more digital infrastructure deals in the price-sensitive markets where these types of projects are most in demand.
While PRC-originating loans are typically offered at much lower rates, from a purely financial perspective, the majority of PRC-funded projects are capital inefficient. Significant shares of capital are absorbed by multiple intermediary actors (e.g., state ministries, mobile operators). Access to Beijing’s financing is often tied to using Chinese contractors, procurement chains, or cofinancing arrangements with Chinese firms. One workshop participant who works in connectivity finance stated that for PRC-originated loans, only about “70 cents on the dollar makes it to actual infrastructure.”
Perhaps more concerning for the long-term economic health of recipient countries, a large share of PRC-financed projects—“around 80 percent of those over $10 million in Africa in recent years,” according to a workshop participant who works in connectivity finance—are not generating enough revenue to repay their loans or meet expectations. This assertion is
supported by a 2021 AidData report examining thousands of PRC-financed Belt and Road Initiative projects, which found that many of them faced repayment stress, and/or required restructuring or renegotiation. In short, cheaper financing helps win projects upfront, but many of those projects face serious financial challenges once they are built.
Despite longer-term financial consequences, this strategy has allowed PRC firms to dominate the market. The US DFC lends money at a rate “about 2.5 percentage points above its own borrowing cost,” one workshop participant flagged, which makes its financing more expensive than PRC loans. When passed along to the borrower, 2.5 percentage points over the life of an internet communications technology (ICT) loan can mean millions in extra costs that price-sensitive customers cannot shoulder. In short, competition over strategic and economically vital infrastructure is being decided on price at the margin. This finding is supported by data from the Organisation for Economic Co-operation and Development (OECD) that shows export credit competition can shift outcomes based on financing terms rather than underlying quality. As one roundtable participant put it, “China is eating our lunch for 250 basis points.”
Workshop participants also emphasized that US and Western lenders often approach deals differently than Chinese lenders. As one participant put it, “[Western] development finance institutions have focused more on financial institution requirements, not development. PRC-based lenders focus on development, not financial institution requirements.” In practice, this means US-based lenders typically require borrowers to meet stricter financial, regulatory, and governance standards, including formal compliance and reporting systems, while PRC lenders place fewer upfront requirements on these dimensions. Institutions like the DFC tend to operate as risk-conscious lenders, carefully pricing in country-level risks such as inflation, currency volatility, and contract enforcement challenges.
By contrast, participants noted that PRC-based lenders are often more willing to extend financing without fully pricing in these risks. These macro-level risks can significantly reduce returns over time: “About half the spread between gross and net returns for emerging market fund managers is eaten by macros,” a workshop participant observed. Many African markets are viewed as high risk by global financial standards, with Botswana standing out as one of the few countries on the continent with an investment-grade credit rating. As a result, local firms in these markets often struggle to meet the requirements for US-backed financing and may be excluded from consideration.
As seems evident by the investment approach outlined above, the PRC’s ICT financing strategy often is not primarily motivated by financial returns. A consistent theme from experts
Financing
throughout our research period (October 2024 through May 2026) was that for China, political leverage and long-term market positioning is the primary objective and value that the PRC sees in its connectivity dealmaking. PRC financing institutions are often more willing to absorb losses or tolerate defaults when projects are seen to secure diplomatic, security, or political advantages. Recipient country governments are often very aware that Beijing is willing to shoulder more financial risk for these gains. As one participant who had worked closely with an East African government on technology procurement practices stated, “African stakeholders say if they owed China a million dollars, they’d worry, but because they owe billions, it’s China’s problem. As China’s economy slows, the debt becomes more China’s problem. African stakeholders aren’t dissuaded from borrowing more—they’re figuring out where Beijing will draw the line.”
The PRC’s emphasis on the diplomatic aspect of connectivity financing is reflected in the way financial dealmaking itself functions as an instrument of statecraft. ICT projects are offered alongside a suite of other offerings and often include direct face-to-face attention to consumers and extensive relationship-building efforts. One such offering often includes training programs. Chinese companies routinely work with small- and medium-sized internet service providers, offering customized solutions, on-site technical support, and flexible financing. As one connectivity finance expert observed, “Western vendors will never send a team to a 10,000-subscriber ISP. Huawei will not only send them, they’ll fly the engineers to Shenzhen for three weeks of training.”
Another expert who tracks PRC-originated ICT loans highlighted the prevalence and popularity of Huawei’s “Seeds of the Future” technical training program as part of these package deals. This program facilitates students, engineers, and officials being trained on Chinese systems and using Chinese devices and apps, building both technical dependence and personal familiarity. As this expert said, “There’s real intimacy of experience when your handhelds and social media are from Chinese companies.”
A notable aspect of China’s approach is that its diplomatic and commercial arms are deeply linked. PRC embassies and ministries routinely broker arrangements between local governments and Chinese firms. “When Kenyans wanted drone and AI technology for agriculture,” a discussant noted, “they reached out to Kenya’s ICT Ministry, got connected to Beijing’s equivalent, [and] Beijing brought companies and facilitated the deal. When Kenyans expressed cost anxiety, they were connected to Exim Bank. The state platforms its companies when entering African markets.” In these settings, the Chinese state acts simultaneously as facilitator, financier, and guarantor, ensuring that commercial activity advances broader political objectives.
In addition, the PRC works closely with local partners to tailor its offerings to existing host country realities, including linking deals to progress in national-level initiatives, and adapting technical specifications to local technical capacity. In Egypt, for
example, the PRC explicitly aligned several infrastructure projects with the country’s “Vision 2030” priorities, allowing Beijing to frame its engagement as support for national modernization and for the Egyptian government to further its progress toward its goals. This linking with national-level priorities is a known tactic Beijing employs in its engagement with Global South countries, aimed at reinforcing both the legitimacy and durability of its investments.
On local capacity, firms like Huawei have responded to demand for high-bandwidth, low-latency ICT networks in many of its partner countries by providing “AI-in-a-box” solutions, which operate on top of its existing ICT infrastructure. This is in contrast to US equipment manufacturers, who are generally making equipment for higher bandwidth and higher cost environments. This lack of local tailoring in the US model is evident in the example of the US-brokered deal between Microsoft and G42, the UAE-based AI firm, to build a billion-dollar data center in Kenya. Progress on the project has stalled since the deal’s announcement in 2024, reportedly due to the inability of Microsoft and the Kenyan government to “[identify] the business rationale and a sustainable financial model.” As one expert noted of the deal, “It was geopolitically supply-driven, but Microsoft doesn’t see a way to monetize it. The specs are misaligned with actual demand signals.”
China’s success also stems from shaping markets and actively creating the demand for its products. In its diplomatic engagements, the PRC engages in active promotion of Chinese visions of digital development that embrace sovereignty and self-sufficiency narratives, which are highly resonant in many Global South countries. Firms such as Huawei and ZTE proffer their solutions in the form of “smart cities,” “safe cities,” and “digital governance,” reshaping local expectations about what modernization should look like.
In addition, when Chinese companies like Huawei build endto-end solutions, they can build capabilities for censorship and surveillance into the infrastructure itself. “The structural issue is that standards for global internet have efficiency costs associated with privacy and security that liberal democracies require,” a participant noted. “China sees ability to censor and surveil as a feature, not a bug.” These offerings are often attractive to governments seeking rapid technological upgrades and enhanced control, even when feasibility assessments are thin or long-term sustainability is uncertain. They are appealing in countries where US vendors will not invest because of the degree of perceived financial risk. For example, Angola signed a quarter-billion-dollar contract with China for facial recognition systems, and many of Rwanda’s integrated security centers have been built by Chinese companies.
Taken together, these dynamics give China’s model several clear strengths. Its diplomatic, financial, and industrial tools are tightly integrated; subsidies and concessional lending make projects viable in low-revenue markets; products are adapted to low-bandwidth and low-income environments; sustained engagement builds long-term relationships; and projects move quickly with fewer procedural bottlenecks than alternatives.
countries exposed to long-term debt risks and opaque financing terms. In some markets, growing awareness of both debt burdens and surveillance concerns has sparked political backlash. Yet overexposed debt may pose a bigger problem in the longer term for China than the recipient. At present, the
the capital return. But the model’s effectiveness over time depends on continued state support; a domestic economic slowdown or fiscal tightening could constrain China’s ability to sustain its current pace of overseas investment.
The current democratic response: Gaps and constraints
Democratic governments have recognized aspects of the challenge posed by China’s expansion in digital infrastructure, but their responses to date have been fragmented and insufficient. The US government has spent significant effort in seeking to curb Chinese telecom giant Huawei’s attempts to wire the world with little to show, and Chinese telecom equipment vendors have more than a 40 percent market share. In addition, over the past several years, the United States and democratic countries have rolled out various initiatives and funding mechanisms to compete with the PRC in digital infrastructure. This includes a recent executive order outlining actions to export the US AI stack, including related infrastructure; a $600 billion fund launched by the G7 known as the Partnership for Global Infrastructure and Investment (PGII); and a $350 billion fund as part of the European Union’s Global Gateway strategy that is committed to global infrastructure.
However, several challenges persist in implementing these programs effectively at scale. Taking PGII as a case study, the initiative relies heavily on mobilizing private capital, but efforts to scale investment have often fallen short due to difficulties in aligning public- and private-actor interests. Blended finance efforts under PGII have in the past struggled to move beyond pilot-scale investments, with public institutions unable to sufficiently derisk projects to meet private investors’ return expectations, resulting in mobilization outcomes measured in the tens of billions rather than the trillions originally envisioned.
Coordination across various institutions with different mandates, standards, and financing models can also stall progress on multistakeholder models for connectivity financing. For example, US international infrastructure efforts require coordination across multiple agencies, including the International Development Finance Corporation (DFC), Export-Import Bank of the United States, the US Trade and Development Association, and (in the past) the now dismantled US Agency for International Development (USAID), each having had different mandates and approval processes, leading to delays and inconsistent project pipelines.
As mentioned above, high levels of sovereign and financial risk in markets where many of these investment projects would occur limit the pipeline of bankable projects available for funding at the outset. Western development finance institutions tend to prioritize large transactions with established operators, leaving smaller and regional providers underserved. In addition, these lenders generally provide no or limited technical assistance and early-stage project preparation for connectivity infrastructure. According to research from the World Bank and the OECD, gaps in project preparation capacity and upstream support remain key barriers to scaling infrastructure finance, particularly for last-mile connectivity in rural and underserved areas. As a result, even when financing is available, a shortage of investment-ready projects limits deployment.
For example, an analysis of the PGII-aligned initiative called Just Energy Transition Partnerships found that limited pipelines of investment-ready projects delayed the disbursement of committed funds. As a result, US and partner-led initiatives have historically struggled to scale and reach high-need communities. As one expert interviewee noted, connectivity value-chain gaps exist especially in access to finance for middleand last-mile connectivity. As she put it, “DFIs play a critical role in financing large-scale infrastructure. But there is a gap in the ‘missing middle,’ particularly for last-mile connectivity, where financing must be more tailored and affordable.” This has significant consequences for participation in the global economy. As the same expert noted, “connectivity is foundational. Without it, nothing else, including AI, is possible.”
To summarize, several structural barriers continue to prevent the United States and its partners from mounting an effective response to the PRC’s dominance in connectivity financing:
1. Fragmentation of tools: US development finance (DFC), diplomacy (State Department), commerce (US Commerce Department) and technology policy operate largely in silos, without a unified strategic framework.
2. Risk aversion and compliance culture: Western DFIs emphasize fiduciary integrity, requiring audited financials and formal governance structures, and have a deep aversion to risking taxpayer dollars, all of which exclude many otherwise viable partners.
3. High cost of capital: Western financing typically imposes higher interest rates than Chinese alternatives.
4. Limited political coherence: US digital infrastructure projects are rarely paired with sustained, high-level diplomatic engagement.
5. Narrative deficit: Policymakers frequently frame digital investment as development assistance rather than as a matter of national security and economic competitiveness.
6. Reactive vs. proactive approach to dealmaking: China approaches partners with an integrated offering and a willingness to facilitate access to the key players needed for a deal; it offers preinvestment technical assistance, and PRC counterparts actively guide the deal to completion. In contrast, Western DFIs usually require borrowers to submit a proposal with all the details worked out—and only at the point in the process where the DFI’s money is needed.
Closing this gap will require both leveraging tools, processes, and pipelines that have been effective in the past, while embracing a creative approach that can overcome some of the more significant hurdles to effective deployment of capital and funding. In addition, this approach requires greater strategic coherence, integrating finance, technical assistance, and di-
Financing the future of connectivity: A strategic playbook to compete with China and close the
plomatic engagement around a shared vision of open and secure digital connectivity.
A credible alternative to China’s approach must build on democratic strengths rather than attempting to replicate China’s state-directed industrial policy. The United States and its allies have a strong track record of leveraging blended finance. Blended finance offers several comparative advantages to China’s model, including using government resources to catalyze substantial investment from private-sector sources and bringing more expertise to these capital-intensive projects, while also ensuring infrastructure is built in a way that aligns with US values and strategic interests.
Blended finance structures can materially shift the risk calculus for private investors when public or philanthropic actors take on disproportionate risk. A recent example is the SDG loan fund, where the Dutch development bank FMO partnered with the MacArthur Foundation under the Catalytic Capital Consortium to attract roughly $1 billion from institutional investors led by Allianz. The structure relied on layered risk protection, with
FMO committing to a $111 million first-loss tranche and MacArthur providing a $25 million guarantee. By absorbing downside risk and offering credit enhancement, these concessional contributions improved the fund’s risk-return profile and enabled participation from investors that would likely not otherwise have invested in this fund.
While the United States and partner countries likely cannot match China’s subsidy levels, it can compete on trust, transparency, interoperability, and the ability to catalyze far greater sums of private and philanthropic capital. Emphasizing open standards, privacy protections, and rights-respecting governance offers a clear point of differentiation from China’s opaque and state-centric model. However, these principles must be paired with tangible technical assistance and affordable financing. Without credible delivery on cost and implementation, democratic alternatives will struggle to gain traction in the Global South. As one participant noted: “China’s model succeeds because it treats digital infrastructure as statecraft. The question for us is whether we can learn to do the same—without losing what makes our model different.”
Recommendations
1. Reforming the DFC
The US International Development Finance Corporation is a critical pillar of any US-led strategy to expand global connectivity. Yet, historically, its authorities, incentives, and operating model have limited its ability to deliver impact in connectivity at scale. To play a genuinely catalytic role, DFC must be equipped to deploy capital more flexibly, tolerate higher levels of risk, and prioritize investments that advance strategic connectivity objectives rather than purely commercial returns.
Recent legislative changes have provided a foundation for progress. The DFC reauthorization in December 2025 provided the organization with expanded authorities, capabilities, and incentives that make it more fit for the challenge. First, the reauthorization raised the DFC’s maximum contingent liability from $60 billion to $205 billion, a critical step in enabling investment in capital intensive, strategically valuable connectivity projects. Second, the reauthorization authorizes the DFC to operate in an expanded set of geographies including middle-income countries, with ICT-related investments highlighted as a priority. Third, the reauthorization encourages “catalytic” investments and measures that would allow DFC to shift toward the more concessionary, patient capital that many connectivity projects require. While these reforms are largely helpful and the DFC’s newly expanded tool kit contains many improvements, it’s not clear that the agency is yet fit for the purpose of financing the end of the digital divide.
While ICT has been identified as a priority investment area for DFC for many years now, and the recent reauthorization provides useful exemptions from certain rules for ICT related investments, the practical reality is that DFC is insufficiently active in driving these deals. As one interviewee put it, “DFC wants you to come to them when you’ve basically already done all the work, have all the other capital, have everything tied up in bow and all you need is their money. They then kick the tires on your financial model and do the deal.” If the United States desires to play a leading role in closing the digital divide, it should enshrine that ambition explicitly in DFC’s mandate, priorities, and incentives. Such a mission, whether articulated via an executive order, DFC board directive, and/or other mechanism, should provide guidance and political cover to increase the DFC’s:
y Risk appetite and willingness to provide concessionary capital.
y Leadership in driving deals across the investment life cycle.
y Focus on catalyzing private-sector capital and generating capital additionality (i.e., situations where development finance provides “terms and conditions that private investors are unwilling or unable to offer”).
y Willingness to partner with aligned actors.
y Innovation in deal structures and deployment of its many tools.
While the US government alone will likely struggle to match dollar for Chinese yuan in this sector, it can marshal far more capital than the PRC is capable of by using the tools in the DFC’s kit to incentivize private and philanthropic capital to invest in deals it leads. Yet, simply put, the DFC is not sufficiently incentivized to play this kind of role or use its tools in this way. Indeed, in some ways, the recent DFC reauthorization pushes the agency to chase higher return projects. Great progress could be made in this area by tying DFC staff bonuses to targets around catalytic effect and capital additionality of DFC investments as well as board-level reporting on impacts in the global connectivity market.
Another obstacle to DFC being fit for purpose is institutional capacity. DFC does not possess sufficient expertise related to the financing of digital infrastructure. As one interviewee put it, “there are maybe three people in the building who know how to do a connectivity deal.” Unless DFC has teams that are specifically focused on connectivity finance and the ability to utilize expertise from the private sector, the agency will continue to be challenged in originating, structuring, and managing connectivity investments. One opportunity to quickly augment DFC staff expertise, would be to create a private-sector detailee program for connectivity-focused investment managers.
Another powerful tool in DFC’s toolbox is political risk insurance which provides coverage against losses due to currency inconvertibility, government interference, and political violence. When deployed, DFC’s political risk insurance not only protects the American taxpayer but also protects all follow-on investors. By reducing the risk that these other capital partners face, using this tool can powerfully drive down the cost of capital. While political risk insurance should be a very cost-effective way to catalyze additional investment, it is a seldom used tool in the connectivity space because the Department of Justice’s Office of Legal Counsel currently requires the DFC to comply with onerous Federal Credit Reform Act requirements for political risk insurance. In practice, this requires DFC to set aside significant upfront capital (assuming the insurance will have to be paid out) rather than treat it as a contingent liability, thereby reducing the total volume of insurance and investment the DFC can offer.
The biggest question marks in the DFC reauthorization are around the new equity investment revolving fund. Congress has authorized a $5 billion equity revolving fund at the Department of the Treasury to provide a dedicated capital stream for equity investments and will now allow DFC to consider and keep the returns of those investments to fund investments in the future, technically closing the “equity loophole.”
On one hand, equity investments can be a useful tool for the DFC to have in its toolbox, even if the cashflows of many
connectivity projects can support reasonably priced debt financing. On the other hand, Congress did not actually provide an appropriation for this new equity revolving fund. Moreover, because returns from equity investments will be returned to the DFC to be redeployed in future investments, there’s a risk that the agency will be incentivized to chase high-return investments rather than using equity as a truly catalytic tool. Nevertheless, if Congress actually provides funding for the use of equity investments, this will be helpful in enabling the DFC to demonstrate that it knows how to craft an investment approach that doesn’t lose money and will hopefully build a track record of appropriately assessing risk-return potential that it can score against in the future.
Capacity expansion alone will be insufficient to achieve impact. The DFC must also change who it is willing to invest in. While the DFC has historically invested in deals to expand large-scale fiber optic networks in Africa, construct a network of data centers, build thousands of towers in Myanmar, or finance submarine cables, in order for the DFC to succeed in this mission, it must be willing to provide concessionary financing to the entities best positioned to end the digital divide, namely, community focused ISPs and specialized intermediaries. Without a significant change in risk tolerance and investment focus, new authorities will likely not result in significantly different outcomes.
This stands in stark contrast to the PRC, which plays a very active role in bringing financing to the table and supporting the entire life cycle of a deal. While DFC does have authorization and some funding available to provide technical assistance, this tool is underutilized in connectivity investments and is most frequently deployed for deals that are nearly ready for DFC investment or via postinvestment support after an investment has closed. It would be incredibly impactful for the DFC to deploy technical assistance grant funding, either directly or via specialized intermediaries, much earlier in the investment process to increase the investment readiness of ISPs as well as to provide demonstration capital in the form of grants to showcase what investments in this sector could look like. Deployment of these tools in this way would powerfully help to develop the pipeline of connectivity investment opportunities.
If the DFC is reformed along these lines, it will be a strong candidate for providing a viable alternative to PRC digital infrastructure financing. Progress should be measured by specific, outcome-oriented metrics including:
y Increased investment in last-mile and middle-mile connectivity infrastructure
y The creation of purpose-built connectivity investment vehicles or specialized intermediaries.
y Growth in DFC staff with dedicated connectivity finance expertise.
y Development of a robust pipeline of investable connectivity projects.
y Demonstrated evidence of capital additionality and the catalysis of private capital investment.
Meaningful progress on these fronts would position DFC to create sustained, strategic impact in wiring the world on US and partner country terms.
2. Building the enabling environment
Beyond investing in expanding connectivity itself and catalyzing others to do so, there is much the US government and its allies can do to create a more conducive environment for building internet networks. While the following recommendations would necessarily need to be grant funded, creating conditions that will make it easier to start and build new networks will have a positive impact on DFC’s investments in this area by reducing costs, time to build, and the risk of these investments.
Open telecom data
While global submarine fiber cables and landing stations are relatively well-documented (e.g., Submarine Cable Map), there is shockingly little information available publicly about where the physical infrastructure of the terrestrial internet is located. Securing access to backhaul is one of the most difficult and expensive parts of building a new network, in no small part because it is very difficult to find where a network can connect into existing internet infrastructure.
One of the most cost-effective opportunities to create a better enabling environment would be to invest in building out an open database of where terrestrial fiber is available. This would dramatically accelerate network planning and construction by helping ISPs see where they could interconnect. Moreover, by combining fiber data with additional datasets like roadway data, railway data, terrain, population density, and NASA’s Black Marble project (which is a decent proxy for electricity access), it is also possible to see where new builds would be most cost effective.
The leading effort in this area, the Open Fibre Data Standard established in 2022 under Steve Song’s leadership, in collaboration with the World Bank, International Telecommunication Union, the Internet Society, Mozilla Corporation, Liquid Intelligent Technologies, CSquared, and Digital Council Africa—provides a common framework for collecting and reporting open telecom data. Already, more than twelve countries including France and Canada publish open telecom data.
There are several opportunities for the US government to contribute to efforts in this area:
y Providing grant funding to expand and regularly update open telecom data-mapping efforts.
y Engaging diplomatically with partner country regulators and telecoms to advocate for public disclosure of telecom data and adoption of the Open Fibre Data Standard.
y Reporting on or requiring its investees to report on any internet infrastructure investing, which would aid broader open telecom data efforts while also demonstrating tangible progress to US domestic political stakeholders and the American public.
Financing the future of connectivity: A strategic playbook to compete with China and close the digital divide
y Requiring US participation in open telecom data reporting according to a shared standard through entities that regulate and/or finance broadband domestically (e.g., Federal Communications Commission, Department of Commerce), which would send a powerful signal to other countries while also helping to connect millions of unconnected Americans.
Regulator training
There are numerous low-effort ways that regulators can accelerate the rate at which the unconnected are coming online. Consider, for example, regulation on spectrum: the electromagnetic waves through which all communication is transmitted. Most countries are using a fifty-to-one-hundred-yearold spectrum policy framework, while spectral efficiency (the rate of how much data can be transmitted through a given slice of spectrum) has doubled roughly every thirty months since Marconi created the wireless telegraph. Mozilla and the African Telecommunications Union signed a memorandum of understanding to train regulators on the continent in innovative spectrum policies. While this partnership is no longer active, it does highlight how capacity-building partnerships with regional regulators offer an efficient opportunity to equip many regulators with the tools they need to rapidly connect their nations.
While regulatory conditions vary by country, in addition to reforms of spectrum policy, grant funding could usefully be directed to educating and supporting regulators in the work of easing restrictions on operating licenses and construction permits, reducing or removing capital reserves, removing restrictions on the import of telecommunications equipment, allowing use of interconnection with government-owned fiber, and making changes to government procurement policy. Leveraging a whole-of-government approach, the State Department would be well positioned to both administer a new grant program on regulatory capacity building and reform as well as engage foreign partners on these topics through diplomatic engagement.
This focus on building up the capacity of foreign partners to build an open, competitive, and efficient market would stand in contrast to the PRC’s approach, which tends to directly or indirectly force local governments to modify regulations it finds onerous as a condition of receiving its financing.
3. Building markets
Every private roundtable and public panel conducted as part of this research identified the same challenge: a clear missing middle in the connectivity finance market. The deals most likely to bridge the digital divide generally fall between $200,000 and $10 million. While networks can be bootstrapped with local resources, often supported by philanthropic contributions from a limited set of nongovernmental organizations (e.g., the Association for Progressive Communication; Internet Society), foundations, aligned companies (e.g., Microsoft, Mozilla), and select government actors (notably the United Kingdom’s Fo-
reign, Commonwealth & Development Office and the Swedish International Development Cooperation Agency), these efforts rarely raise more than low six-figure sums at a time. Local small business financing, when available, is typically limited to more mature firms and involves millions.
At the same time, DFI financing and international aid projects are generally not available until a project requires eight figures of capital. As one connectivity finance expert explained, “below $20 million, and especially below $10 million, it becomes extremely difficult.” One officer from a regional development bank noted, “we don’t really get on the phone for less than $50 million.” As a result, ISPs best positioned to close the digital divide are too large for philanthropy and microfinance, yet too small or too risky for DFIs and international aid.
While there is also a need to increase investment in the $20 million-plus range, the deals at or below $10 million are most likely to bridge the digital divide. These smaller transactions pose challenges for DFIs, as a $2 million deal often requires similar effort to a $200 million deal. Addressing this segment of the market presents a significant strategic opportunity for a US-led approach to connectivity finance.
Specialized intermediaries
As discussed at a recent panel during the Spring 2026 Meetings of the World Bank and International Monetary Fund (IMF), specialized intermediaries can be instrumental in bridging the gap between the capital needs of ISPs and the deployment constraints of DFIs. While the vast majority of smaller, more community-focused ISPs who are best positioned to end the digital divide do not have the absorbative capacity to take on more than a $20 million investment, a specialized intermediary could assemble a portfolio of these deals, aggregating this capital demand, take in eight-plus-figure investments from DFIs, private investors, and philanthropies, and then deploy that capital in smaller, more manageable chunks across their portfolios. Operating closer to the ground and with dedicated in-house expertise, we envision these specialized intermediaries being responsible for sourcing, structuring, conducting due diligence, and servicing investments, providing pre- and post-investment technical support, and providing reporting to investors and donors.
These specialized intermediaries would also enable DFIs and other investors to more easily pool resources into regional or global funds, a historically painful process for governments, private investors, and philanthropies alike. As was remarked during that same IMF-World Bank Week panel, “everyone loves blended finance, but no one wants to do the blending.” Specialized intermediaries could and should play this role. By pooling capital from a variety of investors across the risk/return spectrum, specialized intermediaries can lower the cost of capital to ISPs. Not only will lower cost of capital reduce the costs that ISPs pass on to their customers making the internet more affordable for the communities that they serve, by pooling and blending capital at the fund level with a specialized intermediary, DFIs and other investors can reduce transaction
Financing the future of connectivity: A strategic playbook to compete with China and close the digital divide
costs for ISPs (who otherwise have to pool and blend capital themselves at the individual transaction level) putting further downward pressure on prices and increasing affordability. As one connectivity finance expert put it, “A more coordinated and blended approach is needed. Right now, companies face fragmented funding from multiple sources with different requirements.”
The US Government has successfully used this approach in the agricultural sector. For example, support from the now-defunct Overseas Private Investment Corporation and its replacement, the DFC, has been essential to the success of Root Capital, which provides low-interest loans and technical support to rural farmers. Since its founding in 1999, Root Capital has distributed $1.5 billion to improve the lives of over ten million people in farming families and generated $4.6 billion in economic activity. The DFC enabled this endeavor through credit facilities, credit enhancements, and political risk insurance.
Specialized intermediaries in the connectivity space include:
y The Connect One Billion Fund: With initial support from USAID, it is a blended-finance platform led by the Vernonburg Group, designed to unlock last-mile connectivity by providing local ISPs with financial tools, technical support, and strategic partnerships to enable growth. The model combines technical assistance, concessional capital, and equity for smaller ISPs.
y Connect Humanity1: This organization provides debt financing to community-focused ISPs, alongside pre- and post-investment support, and planning grants to help communities unlock the partnerships that will get the internet built in their communities.
y Connectivity Capital: Through its Connect The World Fund, it provides debt financing of $200,000 to $2,000,000 to ISPs and digital infrastructure companies operating in frontier markets. Additionally, Connectivity Capital’s Insights platform works with investors, operators, and partners to provide project advisory, market assessment, and operational assistance.
Whether involving these or other organizations, any playbook for financing capacity to end the digital divide should include dedicated support to a series of specialized intermediaries. To avoid a single point of failure and to maximize geographic coverage, we recommend providing support to three to five specialized intermediaries. While initial support would likely include grant funding to help stand up or expand operations, in time, like Root Capital, these specialized intermediaries should be supported with a range of financial products including investment capital, finance facilities, guarantees, and political risk insurance.
Pipeline development
While there are at least tens of thousands of small, community-focused ISPs in the world already playing leading roles in expanding internet access, many of these ISPs will need additional preinvestment technical assistance before taking on financing. Indeed, every telecom investor we spoke to said that every connectivity deal requires technical assistance.
For example, thanks to an improved regulatory framework for small- and medium-sized ISPs and increased funding dedicated to ensuring sustainable economic development in Brazil, the country now boasts an extensive network of more than 10,000 to 19,000 small ISPs, which have played a pivotal role in advancing internet access and affordability among the nation’s underprivileged populations in urban, rural, and remote parts of the country. Currently, these small ISPs have a 57 percent market share, mostly fiber. In this context, Connect Humanity has partnered with the Brazilian Network Information Center (NIC.br) to provide investment readiness training to small Brazilian ISPs. In addition to helping these ISPs to improve their operations, the training sessions are building a pipeline of investable opportunities.
Similarly, in research published in Self-sustaining Financing Solutions for Community Connectivity—created in a collaboration of the United Nations Internet Governance Forum’s Dynamic Coalition on Community Connectivity and the Center for Technology and Society at the Getulio Vargas Foundation—Connect Humanity analyzed nine community-centered connectivity initiatives across Asia, Africa, and Latin America. Its summary findings showed that community networks are meeting clear demand in underserved areas, with adoption rates often reaching 30 to 50 percent. Many small ISPs are operationally sustainable and cover day-to-day costs, but face barriers accessing modest upfront capital, typically $50,000 to $300,000, due to limited collateral and exclusion from traditional financing channels. While investment risk varies, most networks fall into a moderate risk category comparable to other small-scale investments. Financing approaches need to align with these conditions, with tools such as recoverable grants, revenue-based financing, and blended capital better suited than conventional loans.
Not only does investment readiness training and other forms of preinvestment technical support help to build a pipeline of investment opportunities and reduce risk, but these trainings also help to build trust and familiarity between investors and ISPs, increasing deal speed when it comes time to invest. Impact investors in other sectors have similarly deployed investment readiness training sessions to effectively build their own derisked deal pipelines, notably Acumen through its Acumen Academy. Yet DFC has not historically used its limited technical assistance grant funds for pipeline development. As one
1. Disclosure: Jochai Ben-Avie, one of the authors of this paper, is the co-founder and former CEO of Connect Humanity. He has no operational role with the organization today.
Financing the future of connectivity: A strategic playbook to compete with China and close the digital divide
interviewee said, “DFC basically only does preinvestment TA for deals it knows it already wants to do. It’s a wildly underused tool in the toolbox.”
Whether through an expansion and reorientation of the DFC’s technical assistance budget, a new State Department grant program, and/or support to the specialized intermediaries described above, dedicated grant funding should be provided for pipeline development and preinvestment technical assistance as a necessary complement to investment capital.
Demonstration capital
The recent DFC reauthorization does not include explicit authority for pilot or demonstration capital. This represents a missed opportunity to validate new connectivity models, lay the groundwork for a scalable investment approach, and effectively build a pipeline of deals that DFC and other investors can later invest in. While Congress will likely be reticent to touch anything around the DFC so soon after passing the reauthorization, congressional appropriators could and should include more funding and authority for the State Department to provide this kind of demonstration capital and technical assistance funding through a targeted increase in the Function 150 Account, the US federal budget category for international affairs, which includes discretionary spending on foreign policy and foreign assistance.
4. Catalyzing capital
To mount a credible alternative to Chinese connectivity financing, the United States will need to focus efforts on catalyzing private-sector capital in a true blended finance approach. As one roundtable participant said, “Connecting the unconnected isn’t a technical problem, it’s a math problem.” The DFC can help to bring more capital to bear on this challenge at an acceptable cost of capital through the following ways.
Concessionary capital
When DFIs like the DFC are willing to take a first loss or more junior position in a capital stack, they can powerfully shift the risk/reward profile of an investment for other investors higher up in the capital stack. Consider the SDG Loan referenced earlier: For Allianz and the other private-sector partners invested in the senior tranche of that deal to lose even a dollar, the losses of the MacArthur Foundation and FMO would have to be $25 million and $111 million, respectively. That makes what could be seen as a risky investment far less risky. At the same time, for both the MacArthur Foundation and the Dutch government/FMO, mobilizing $1 billion of private-sector capital toward one of their priority investment areas is a significant strategic victory.
DFC’s goals, incentives, and operational culture will need to change for its dealmaking to begin to look like this example. As noted above, an executive order, act of Congress, or DFC board directive to focus on generating capital additionality would be helpful in this regard, but the reality is that offering
concessionary capital inherently involves greater risk. One roundtable participant said:
While it’s a broader issue, risk tolerance should be at the top of the list. . . . What really matters is how talent is incentivized. If you polled DFC investment officers right now, 95 percent would say, “my job is not to lose money.” That needs to shift. They need clear guidance that their job may, in fact, include losing money strategically. [Take] British International Investment [the United Kingdom’s development finance organization] . . . they’ve made progress overcoming some of DFC’s hurdles. They’re smaller and don’t face the same “push money out the door” pressures. But there’s a lot to learn, especially on private capital mobilization. They’ve updated their measurement frameworks to reward risk-taking when it aligns with impact, and they’re well ahead of DFC on that front.
While many small ISPs are profitable and highly capital efficient—one workshop participant said fiber businesses often generate 80 to 90 percent earnings before interest, taxes, depreciation, and amortization margins after a few years—the actual risk to taxpayers may be limited, likely lower than it initially appears.
Concessionary capital can come in the form of either taking a more junior position in a capital stack, as FMO did in the deal above, providing financing at below-market rates, or both. We recommend that DFC pursue a strategy of providing the vast majority of its investments in connectivity at a lower cost of capital and also be willing to take first-loss positions in capital stacks.
Credit enhancements
In addition to providing concessionary capital, DFC has many other existing tools that can meaningfully help to mobilize private-sector capital including:
y Guarantees: This kind of facility creates a contractual obligation to pay out if certain specified loss conditions occur. By being the first party to absorb any losses that may occur, the risk to other investors higher in the stack is fundamentally reduced making it easier to invest and potentially reducing the cost of that more senior capital. Because guarantees only pay out as losses meeting certain predetermined conditions occur, it’s possible that a guarantee pool will only be partially used if at all, and some funds will be returned/remain available at the end of the fund life. Moreover, guarantees need not necessarily be funded (effectively held in escrow), they can be unfunded relying on the strength of the guarantor’s balance sheet to satisfy the guarantor’s contractual obligation to pay out. Meanwhile, funds allocated for the guarantee can be invested in other vehicles and generate some returns in the meantime. However, some investors may apply a discount on the value of an unfunded guarantee versus a funded guarantee.
y Political risk insurance: The DFC has an existing ability to issue political risk insurance up to $1 billion, which protects not only the US taxpayer but also follow-on investors from risks like currency inconvertibility, government interference, and political violence including terrorism. Most investments in developing countries involve a risk premium, which is a major contributing factor to the cost of capital. With political risks covered, the cost of capital from DFC and other investors can be lower as a result, helping to make financing more affordable. Moreover, given the scale at which DFC operates and purchases political risk insurance, the premiums on individual deals are substantially cheaper than if a private investor or ISP were to seek to buy equivalent insurance coverage.
We recommend that the DFC board allocate funding specifically for using these tools for connectivity finance and support DFC staff to leverage all the tools in its toolbox.
In interviews, two experts suggest two other credit enhancement tools that we do not believe are in DFC’s existing toolbox and authorizations, but could be useful in terms of mobilizing private-sector capital:
y Capped upside equity investments: While equity investments are an underutilized DFC tool due to previous accounting restrictions (which forced DFC to treat equity investments as a total and immediate loss), this issue has been addressed in the recent DFC reauthorization. When DFC provides equity, it can structure the investment to define a cap on the returns DFC will receive (e.g., return of principal plus a certain percent). If the investment is profitable enough that DFC hits the cap, it would then be out of the deal, and any additional upside would accrue to the other investors. By providing private-sector investors with more upside potential, DFC can incentivize these investors to participate in higher risk deals.
y Tax credits for origination: Governments could offer tax credits when a private investor makes a connectivity investment meeting certain qualifying conditions, as suggested in an interview. To avoid perverse incentives to make small investments in bad companies just to earn the tax credit or to sell investments too early, the conditions of the tax credit could specify a minimum investment size and require investors to hold the investment for a certain amount of time. These types of tax credits are very common and successful in the affordable housing world. They are also advantageous in that they require no immediate cash outlay by the government, only foregone tax revenue if their impact goals are met.
We recommend that the DFC create a working group to assess the feasibility, optimal strategy, and demand for adding these credit enhancement tools to its toolbox. Once that is accompli-
shed, and assuming there is market demand, DFC would likely need to work through the interagency process; in addition, the DFC should work with congressional partners to establish new authorities to provide these credit enhancements.
A note on fiber and deal structuring
We recommend that any effort to finance the end of the digital divide should focus primarily on investing in fiber build-out. Fiber offers many advantages:
y Fastest and most reliable technology today
y Proven durability over more than fifty years and greater longevity than wireless technologies that are often cheaper in upfront capital expenditures, but typically need to be replaced every seven to ten years, which negates the initial cost savings.
y Seemingly future proof: By transforming data into light and then transmitting light through glass fiber strands, fiber is a rare data transmission technology that is near the speed of light. While improvements can and are being made in transmitter and receiver technology that sit at the ends of those fiber cables, those are relatively easy and cost effective to replace
y More capacity—by orders of magnitude—than previous technologies.
The longevity of fiber is particularly salient. While longer term, patient capital is almost always harder to raise, bringing more alignment between deal length and the usable lifetime of the underlying asset being financed can be powerful in terms of making the math work on connectivity deals. Put another way, while ISPs operating in many low-income communities would struggle to pay back an investment in five years, twenty-five years would be much more reasonable and still less than half of the usable lifetime of a fiber network. While the debt service on a traditional term loan with a twenty-five-year term would likely be prohibitively expensive, a revenue-based financing structure, where an ISP pays a portion of its revenue every quarter up to a predefined cap or a certain number of years (whichever comes first), would likely be financially viable.
We strongly recommend prioritizing investments in fiber and encourage DFC to explore revenue-based financing and other innovative financing structures in its connectivity investments (whether through direct investments or via specialized intermediaries).
5. Working with allies and partners
While we believe the United States is well-positioned to lead a global effort to counter Chinese financing of connectivity, it need not do this alone. Nearly every democratic country has interests threatened by PRC control of digital infrastructure. Moreover, working with allies will strengthen any effort to mount a credible alternative to China-backed financing, both in terms of the capital and the expertise these partners can bring to bear. Below we outline a few opportunities to collaborate with aligned countries in this effort.
Pooling funds
Most directly, the United States could encourage allies to join in providing investment capital as part of pooled global or regional funds. While the Biden administration attempted a similar effort, first with the Build Back Better World Initiative and then later the Partnership for Global Infrastructure and Investment, these initiatives suffered from a lack of substantial commitment of new capital from the administration for the purposes of expanding internet connectivity. Moreover, we have not been able to find evidence that the Biden administration ever sought to pool funds in a specialized intermediary, like those described above, which would be an ideal mechanism for aggregating and effectively deploying capital.
In terms of potential partners, the lowest hanging fruit is likely the EU’s existing Global Gateway Fund. Since its launch in 2021, this fund reportedly has mobilized more than €306 billion ($358.4 billion) for infrastructure projects in the connectivity, health, transportation, education, and climate sectors. In line with the recommendations of this paper, Global Gateway has sought to deploy a wide range of tools to help solve these challenges holistically including grants, favorable loans, budgetary guarantees to derisk investments and improve debt sustainability, technical assistance, and export credit financing.
The Global Gateway Fund drew on new financial tools and financial resources made available under the 2021–2007 EU Multi-annual Financial Framework (MFF). With the next MFF currently under discussion, now is an opportune time to approach European partners to discuss partnering in a global connectivity effort leveraging the lessons European leaders have learned in their past five years of investing. While pooling funds in a single global facility would offer the greatest strategic flexibility, we could also imagine a coordinated approach in line with the “Donroe Doctrine,” with the US government focusing investment efforts in the Western Hemisphere and European allies pursuing a similar approach in Europe, the Middle East, and Africa.
Leveraging existing partnerships
Roundtable participants were also quick to point out that the DFC has several existing bilateral and multilateral relationships with other DFIs that could be leveraged to pursue a coordinated response to connectivity financing. One roundtable participant pointed to existing coinvestment agreements with the Export-Import Bank of Korea and the Japan Bank for International Cooperation (JBIC). Similarly, the DFC has an existing agreement with Masdar, formally known as Abu Dhabi Future Energy Company, a UAE state-backed renewable energy firm originally established as a subsidiary of Mubadala Investment Company. Given the inherent connection between internet and electricity infrastructure, it isn’t a stretch to expand this partnership to coinvestment in internet infrastructure deals. Likewise, given that connectivity is a prerequisite to being able to use AI, it would not be far-fetched for the United States to expand its many existing investment partnerships around AI infrastructure further upstream to connectivity infrastructure.
One government roundtable participant pointed out that DFIs could also collaborate to bring their respective financial tools to bear on a connectivity deal (e.g., with one government providing investment capital, while another provides a guarantee, a third provides political risk insurance, and so on). Another roundtable participant provided an example of this, a 2023 financing package to support Telstra’s acquisition of Digicel Pacific. At the time, Digicel Pacific was the leading telecommunications service provider in the South Pacific region, holding more than 60 percent market share with over 2.5 million subscribers in Papua New Guinea, Fiji, Vanuatu, Samoa, Tonga and Nauru. In this deal, Export Finance Australia provided a $1.33 billion financing package, with JBIC providing a $50 million guarantee, and DFC providing an additional $50 million guarantee plus a political risk insurance wrapper. In announcing this deal, the countries pointed to their strong history of cooperation under the Trilateral Infrastructure Partnership, signed in 2018 during the first Trump administration.
Elevating connectivity as a diplomatic priority
We strongly recommend that a focus on expanding internet access be elevated as a topic in bilateral engagements between the United States and other governments. Not only will this be responsive to one of the top concerns of developing country partners and benefit US companies, but this focus also will enable the United States to more effectively combat China’s strategic efforts to expand its influence, operational capabilities, and control over digital infrastructure. However, as one roundtable participant noted:
First, across the US interagency [landscape], there are fantastic technical experts who understand the issues. But senior principals—especially diplomats at the State Department—often don’t. That creates a real knowledge gap. Educating the foreign service workforce about why this matters is a major part of the challenge. Second, much of US diplomacy is reactive to what key allies and partners—especially in the China competition context— ask of us. So, aligning our priorities with what emerging markets and allies are demanding can help galvanize action within the US government. That’s how you build the political capital needed for concessional lending and budget allocations on this issue. At State, it’s worth noting there’s been bipartisan recognition that tech access and digital issues matter. That’s partly why the department created the new Bureau of Cyberspace and Digital Policy. That bureau is still evolving but getting it right—ensuring it has the right mandate and priority level—will be crucial.
As China’s Digital Silk Road demonstrates, connectivity finance is most effective when paired with sustained diplomatic engagement. The United States should similarly embed ICT financing within broader diplomatic and regional initiatives. We would recommend that a focus on expanding internet access become one of the top priorities of the Bureau of Cyberspace and Digital Policy and that the bureau also be given a man-
Financing
date and the resources to help educate America’s diplomats around the world on this issue set, enabling them to be more effective at spotting and facilitating strategic opportunities to partner with other countries on connecting the unconnected. More broadly, the United States should treat allied coordination on connectivity as a central component of its broader strategy to shape the global digital environment. G7 and OECD frameworks emphasize aligning investment priorities, financing tools, and governance standards around a shared commitment to open, secure, and interoperable networks. Conversations currently taking place in various policy contexts on the need for an “allied stack” reflect this growing understanding that partnering on digital connectivity can enable the United States and partner countries to present a credible alternative to PRC-provided infrastructure, applications, and services.
WSIS+20 outcomes
There are additional opportunities for collaboration through various UN processes. For example, the outcome document of the high-level meeting of the General Assembly on the overall review of the implementation of the outcomes of the World Summit on the Information Society (the WSIS+20 Outcome Document), adopted in December 2025, calls for stronger international cooperation to close digital divides. It emphasizes the need for blended finance, innovative funding mechanisms such as universal service funds and community networks, and continued investment in public access infrastructure. The document also aligns with the Sevilla Commitment on financing digital infrastructure and urges the development of coordinated financing plans and investment frameworks. To advance these goals, it mandates the creation of a task force led by the ITU to assess financing gaps, develop recommendations, and report progress on strengthening digital development financing by 2027.
The Atlantic Council hosted a panel on the sidelines of the IMF-World Bank Fall Meetings in October 2025 when the proposal for this task force in the WSIS+20 outcome document was still being negotiated. The panel also suggested that an international, multistakeholder working group could help to consolidate and document political support for building connectivity financing mechanisms capable of meeting the scale of the problem and working out the practical details of how such funding mechanisms would work. Panelists proposed an “ABC” framework to guide a connectivity finance working group. First, advancing an enabling environment by identifying policy reforms that lower deployment costs and expanding open telecom data mapping to improve visibility into existing infrastructure. Second, building markets through the creation of specialized intermediaries to bridge DFIs and community ISPs, scaling technical assistance to improve in-
vestment readiness, and developing a pipeline of investable opportunities. Third, catalyzing capital by identifying funding sources and structuring blended finance models that combine public, private, and philanthropic resources. The group should initially focus on designing these mechanisms before shifting to capitalization, operate as a multistakeholder body with strong DFI participation, and be supported by targeted grant funding for research, convenings, data infrastructure, and demonstration investments over a one-to-two-year mandate.
Global connectivity finance conference
While useful conversations can happen on the sidelines of other strategic convenings, we recommend the creation of a conference dedicated to advancing connectivity finance partnerships and investments. Reflecting the diversity of actors involved in designing, financing, building, and operating connectivity networks, the conference should be multistakeholder in nature. The conference should have a focus on developing financing solutions and deploying capital, striving to avoid simply admiring the problem of connecting the unconnected. The conference should also make special efforts to include ISPs of all sizes, especially smaller, more community-focused ISPs that are best positioned to bridge the digital divide in the least-served communities, and not just the world’s largest multinational telecoms.
We see such a conference as building on the foundation of Global Connect, a conference convened by US Secretary of State John Kerry and then-President of the World Bank Jim Kim, which occurred on the sidelines of the World Bank-IMF Meetings and usefully brought stakeholders together around a shared goal of connecting 1.5 billion people by 2020. While the conference lost momentum without US leadership when the Obama administration ended and the convening was transferred to the Institute of Electrical and Electronics Engineers, the focus on bringing finance ministers, DFIs, and other stakeholders who traditionally attend the World BankIMF Meetings was especially welcome and helped to mobilize capital toward connecting the unconnected. Notably, DFC announced at a Global Connect conference that it would be doubling its investments in ICT infrastructure.
Such a conference would also provide a venue for those involved in the EU’s Global Gateway Fund and the WSIS working group to share their progress on connectivity finance and seek new partners.
While we imagine such a conference could likely attract sponsorship from numerous companies and philanthropic organizations, government grant funding could help to get this convening off the ground and help signal government buy-in and commitment.
Conclusion
Connectivity is no longer a peripheral development concern; it is a foundational layer of economic power, political influence, and national security in the twenty-first century. Decisions about who builds, finances, and governs digital infrastructure will shape not only access to the internet, but the structure of global data flows, the evolution of artificial intelligence, and the norms that govern the digital environment. As this report has shown, connectivity sits at the intersection of market failure and strategic competition, and it is precisely this convergence that makes inaction so costly.
China has recognized connectivity as an instrument of statecraft and has deployed a coordinated model that integrates finance, technology, diplomacy, and industrial policy. Through sustained investment in digital infrastructure across the Global South, Beijing has embedded itself deeply into the physical and institutional foundations of the global internet. These investments generate commercial returns and political leverage, create long-term dependencies, and provide access to data critical for China’s technological ambitions. While this model is capital-intensive and often inefficient, it has proven strategically effective, and it continues to expand.
Democratic governments, by contrast, have approached connectivity in a fragmented and reactive manner. Existing efforts have too often focused on vendor restrictions or narrow technology alternatives without addressing the underlying financing gap that makes Chinese-backed solutions attractive in the first place. Development finance institutions remain constrained by risk aversion, high costs of capital, and limited sector-specific expertise, while diplomatic engagement has rarely been integrated systematically with infrastructure investment. The result is a persistent mismatch between democratic intent and delivery.
Yet the United States and its allies are not without advantages. This report has argued that a credible alternative to China’s model does not require replicating state-directed industrial policy. Instead, it requires mobilizing democratic strengths: deep capital markets, trusted institutions, open standards, and the ability to align public purpose with private investment. Blended
finance—when paired with specialized intermediaries, technical assistance, and sustained diplomatic engagement—offers a powerful mechanism for closing the connectivity gap at scale while preserving openness, interoperability, and rights-respecting governance.
Reforming and fully leveraging the DFC is central to this effort. Recent reauthorization has expanded DFC’s capacity and introduced new tools that, if used effectively, could materially improve the United States’ ability to finance connectivity in challenging markets. But capacity alone is not enough. The impact will depend on whether the DFC and its partners can deploy capital with greater risk tolerance, support specialized intermediaries, build robust pipelines of investable projects, and integrate financing with broader diplomatic and strategic objectives. Connectivity will not be won deal by deal; it will be won by building ecosystems.
More broadly, success will require a shift in how democratic governments conceptualize connectivity itself. Wiring the world is not charity, and it is not merely about closing access gaps. It is about shaping the architecture of the future global internet—who controls it, how data moves through it, and which values it encodes. Treating connectivity as strategic infrastructure demands sustained political attention, interagency coordination, and a willingness to invest for long-term influence rather than short-term returns.
The stakes are high. Failure to act will not preserve neutrality or market efficiency; it will accelerate the consolidation of digital infrastructure under models that privilege state control, opacity, and coercive leverage. By contrast, a coordinated democratic approach, grounded in blended finance, institutional reform, and partnership with local actors, can expand access to the internet while reinforcing democratic resilience and shared prosperity.
The choice is not whether the world will be connected, but on whose terms. The window to shape that outcome remains open, but it will not stay open indefinitely.
Atlantic Council Board of Directors
CHAIRMAN
*John F.W. Rogers
EXECUTIVE CHAIRMAN
EMERITUS
*James L. Jones
PRESIDENT AND CEO
*Frederick Kempe
EXECUTIVE VICE CHAIRS
*Adrienne Arsht
*Stephen J. Hadley
VICE CHAIRS
*Robert J. Abernethy
*Alexander V. Mirtchev
TREASURER
*George Lund
DIRECTORS
Stephen Achilles
Elliot Ackerman
*Gina F. Adams
Timothy D. Adams
*Michael Andersson
Alain Bejjani
Colleen Bell
Sarah E. Beshar
Karan Bhatia
Stephen Biegun
John Bonsell
Linden P. Blue
Brad Bondi
Philip M. Breedlove
David L. Caplan
Samantha A. Carl-Yoder
*Teresa Carlson
*James E. Cartwright
John E. Chapoton
Ahmed Charai
Melanie Chen
Michael Chertoff
*George Chopivsky
Wesley K. Clark
*Helima Croft
Ankit N. Desai
Dario Deste
*Lawrence Di Rita
*Paula J. Dobriansky
Joseph F. Dunford, Jr.
Richard Edelman
Stuart E. Eizenstat
Tara Engel
Mark T. Esper
Christopher W.K. Fetzer
*Michael Fisch
Alan H. Fleischmann
Jendayi E. Frazer
*Meg Gentle
Thomas Glocer
John B. Goodman
Sherri W. Goodman
Marcel Grisnigt
Jarosław Grzesiak
Murathan Günal
Michael V. Hayden
Robin Hayes
Tim Holt
*Karl Hopkins
Kay Bailey Hutchison
Ian Ihnatowycz
Wolfgang Ischinger
Deborah Lee James
*Joia M. Johnson
*Safi Kalo
Andre Kelleners
Brian Kelly
John E. Klein
Ratko Knežević
*C. Jeffrey Knittel
Joseph Konzelmann
Keith J. Krach
Franklin D. Kramer
Laura Lane
Almar Latour
Yann Le Pallec
Jan M. Lodal
Douglas Lute
Jane Holl Lute
William J. Lynn
Mark Machin
Marco Margheri
Michael A. Margolis
Chris Marlin
William Marron
Roger Martella
Gerardo Mato
Erin L. McGrain
John M. McHugh
*Judith A. Miller
Dariusz Mioduski
*Richard L. Morningstar
Georgette Mosbacher
Majida Mourad
Virginia A. Mulberger
Mary Claire Murphy
Julia Nesheiwat
Edward J. Newberry
Franco Nuschese
*Ahmet Ören
Ana Palacio
*Kostas Pantazopoulos
Alan Pellegrini
David H. Petraeus
Elizabeth Frost Pierson
*Lisa Pollina
Daniel B. Poneman
Robert Portman
*Dina H. Powell McCormick
Michael Punke
Ashraf Qazi
Thomas J. Ridge
Gary Rieschel
Charles O. Rossotti
Harry Sachinis
Curtis Michael Scaparrotti
Ivan A. Schlager
Rajiv Shah
Wendy R. Sherman
Gregg Sherrill
Jeff Shockey
Kris Singh
Varun Sivaram
Walter Slocombe
Christopher Smith
Clifford Sobel
Michael S. Steele
Richard J.A. Steele
Mary Streett
Nader Tavakoli
*Gil Tenzer
*Frances F. Townsend
Clyde C. Tuggle
Francesco G. Valente
Melanne Verveer
Tyson Voelkel
Kemba Walden
Michael F. Walsh
Ronald Weiser
*Al Williams
Ben Wilson
Maciej Witucki
Neal S. Wolin
Tod D. Wolters
*Jenny Wood
Alan Yang
Guang Yang
Mary C. Yates
Dov S. Zakheim
HONORARY DIRECTORS
James A. Baker, III
Robert M. Gates
James N. Mattis
Michael G. Mullen
Leon E. Panetta
William J. Perry
Condoleezza Rice
Horst Teltschik
William H. Webster
*Executive Committee
Members
List as of July 2025