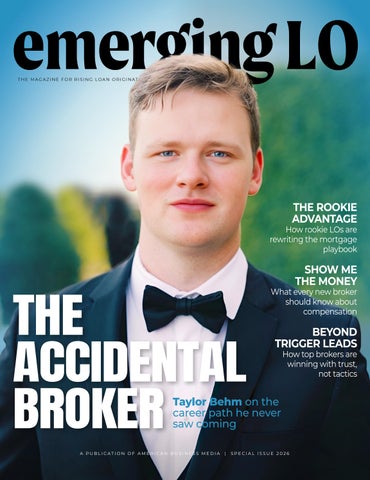
THE ROOKIE ADVANTAGE
How rookie LOs are rewriting the mortgage playbook
THE ACCIDENTAL BROKER
SHOW ME THE MONEY
What every new broker should know about compensation
BEYOND TRIGGER LEADS How top brokers are winning with trust, not tactics
Taylor Behm on the career path he never saw coming
A PUBLICATION OF AMERICAN BUSINESS MEDIA
|
SPECIAL ISSUE 2026
06
41
How rookie originators are reshaping the mortgage business
How brokers are becoming trusted advisors, not lead chasers
10
47
Eight career lessons from a FedEx worker turned broker
Why AI helps new loan originators compete with industry veterans
The New Playbook
Lessons From Logistics
14
The Trust Factor Why credibility remains the ultimate competitive advantage
20
Beyond Trigger Leads
Leveling the Field
48
Builder Battle Plan Recognize common builder tactics and negotiate with confidence
The Referral Formula (Sponsored) The proven system for sustainable business growth
22
The Accidental Broker (Cover Story) Why brokering remains one of the industry’s best-kept secrets
26
Compensation Uncomplicated Understanding broker pay, profitability, and sustainable growth
34
Your First 90 Days (Sponsored) A roadmap for launching a successful mortgage career
36
Pre-Approval Power Why financing certainty matters before home shopping begins
ISSUE ONE 2026
|
3
WELCOME 4
|
Find Your People. Build Your Systems.
T
aylor Behm closed 13 loans in his first month as a licensed originator. A year earlier, he was pointed toward sports, not mortgages, until the math on that path stopped adding up and a friend showed him what this one could look like. What he did next is the reason he’s on our cover, and it’s the reason this issue exists. He didn’t try to know everything. He found people who did, and he built a way of working that produced. That is the whole job in the early years. Not talent you’re born with. Not the perfect market. Two things you can actually control: who you learn from, and the system you run every day. Learn From People Who Have Done It
The fastest risers in these pages did not figure it out alone, and they’ll be the first to tell you so. One of our originators went from working logistics at FedEx to closing loans, and he started as an assistant, watching how deals come apart before he was ever responsible for holding one together. Another built a top-1% operation while working full time as a police officer, and he says plainly that at every level of this business you need a coach in your corner. The rookies rewriting the playbook treat every closed loan as a lesson and every experienced originator as someone to learn from. Before you chase production, chase proximity. Get close to the people already doing what you want to do. Build The System Before You Chase The Split
New originators get recruited on one number: the payout. It’s the wrong thing to optimize first. In the beginning, the goal is not the biggest split. It’s a repeatable system that produces the volume you’re aiming for. The market will not grow your business. Your system will. Build that engine first. The money will follow.
more leads and start finding more answers for the borrowers already in front of you. Activity comes first. Mastery comes from the reps. The Plays Are In Here
The rest of the issue is execution you can use this week. How a new generation is winning on trust instead of pressure. How to see what your compensation will really net before you sign anywhere. How to win the deal when a builder waves an incentive at your borrower. Different plays, one foundation underneath all of them: the right people around you, and a system beneath your feet. You can build this. Plenty of people in these pages started exactly where you are now. Find your people. Build your systems. The rest is work, and the work is worth it. Welcome to Emerging LO.
Move On Day One
You don’t need to master the business before you start. Our first-90-days roadmap lays out how strong originators build early momentum: learn just enough to take action, then go. Once the conversations are flowing, stop hunting for
EMERGING LO 2026
ANDREW BERMAN CEO, National Mortgage Professional andrew@ambizmedia.com
STAFF Vincent M. Valvo CEO, PUBLISHER, EDITOR-IN-CHIEF Alison Valvo PRESIDENT & CHIEF OPERATING OFFICER Andrew Berman CEO, NATIONAL MORTGAGE PROFESSIONAL Emma Walsh MEDIA DIRECTOR Czarinna Andres MANAGING EDITOR Nick Bonadies SENIOR VICE PRESIDENT OF SALES Beverly Bolnick ASSOCIATE PUBLISHER / VP OF SALES Jennifer Ridgeway ACCOUNTING MANAGER Katie Jensen ASSOCIATE EDITOR Tim Burt MARKETING DIRECTOR Meghan Golden MARKETING SUPERVISOR Stacy Murray, Christopher Wallace GRAPHIC DESIGN MANAGERS Navindra Persaud DIRECTOR OF EVENTS Melissa Pianin VP OF ORIGINATOR CONNECT NETWORK Katherine Sala MARKETING MANAGER Matthew Mullins MULTIMEDIA SPECIALIST Courtney Valvo EVENTS COORDINATOR Julie Carmichael PROJECT MANAGER
NOT ALL NEWS IS CREATED EQUAL. NMP Newsletters built to help you stay ahead.
Kristie Woods-Lindig MEDIA & EVENT SPECIALIST
Submit your news to editors@ambizmedia.com If you would like additional copies of Emerging LO, call (860) 719-1991 or email subscriptions@ambizmedia.com www.ambizmedia.com © 2026 American Business Media LLC. All rights reserved. Emerging LO magazine is a trademark of American Business Media LLC. No part of this publication may be reproduced in any form or by any means, electronic or mechanical, including photocopying, recording, or by any information storage and retrieval system, without written permission from the publisher. Advertising, editorial and production inquiries should be directed to: American Business Media LLC 88 Hopmeadow St., Simsbury, CT 06089 Phone: (860) 719-1991, info@ambizmedia.com
Find them at nationalmortgageprofessional.com
EMERGING LO 2026
|
5
Rookie Loan Originators Are Rewriting The Mortgage Playbook
BY CZARINNA ANDRES MANAGING EDITOR, EMERGING LO
6
|
EMERGING LO
I
Three young loan originators are scaling fast by specializing in niche lending, building referral networks, and using AI tools to uncover loan options and streamline workflow
n an industry where nearly half of new mortgage loan originators fail to make it past their first few years, a small but aggressive group of rookies is rewriting the playbook — doing it with niche specialization, relentless relationship-building, and an early embrace of artificial intelligence. According to data from the Nationwide Multistate Licensing System (NMLS), tens of thousands of individuals hold mortgage loan originator licenses nationwide, yet production remains heavily concentrated among a relatively small group of top performers. Data from Modex, a mortgage industry data platform, analyzing rookie originators shows many of the fastest-rising newcomers closing roughly 100 to 150 loans annually, with an average of about 113 units among the top cohort. Among the standouts are three young originators who have scaled their businesses rapidly: Cody Glaiser, who closed roughly 122 units in his first year as a licensed originator; William Duran, licensed two years with about 100 units closed annually or $29 million in loan volume; and Jorge R. Vasquez, who’s been licensed about two years with roughly 112 units closed annually. For Glaiser, an originator for Texas-based The Mortgage Inc., dba The Mortgage Maniac, survival and scale came from differentiation. “I think I did zero business my first month,” Glaiser said. “First of all, you have to learn how to talk to people. You have to learn how to sell a mortgage, because it’s not like traditionally selling a product. You’re selling a service.”
Cody Glaiser
William Duran
Rather than compete head-tohead on conventional Federal Housing Administration (FHA) and Department of Veterans Affairs (VA) loans, Glaiser targeted investmentproperty lending, a segment he believed was underserved. “The biggest thing was picking a kind of niche,” he said. “I got into the investment space because there’s not a lot of people that just do a lot of investments.” By focusing on guideline expertise for Non-QM loan products, he positioned himself as a specialist rather than a generalist. “How do you separate yourself from the pack?” he said. “How do you be different?” That strategy paid off. Although investor lending now represents a smaller portion of his pipeline as primary homebuyers re-enter the market amid stabilizing rates, it remains central to his brand. Over the past six months, he said, declining mortgage rates have brought sidelined buyers back into the market. “All these homebuyers are now reentering the markets,” Glaiser said. “They’re willing to give up their 4% rate. We’re writing loans in the 6% range, or even better than that.” RELATIONSHIPS OVER SCRIPTS Both Glaiser and William Duran of AML Funding LLC, dba Absolute Mortgage & Lending, in Parsippany, New Jersey, credit early relationshipbuilding, not cold-calling scripts, for building momentum. Duran said his entry into the business began unexpectedly. Shortly after high school, while
FIND A NICHE EARLY Jorge R. Vasquez
>>> EMERGING LO 2026
|
7
“I don’t know the last time I’ve ‘sold.’ It’s building relationships. If you have a really good reputation, why do you have to sell things? People want your service.” — Cody Glaiser
8
|
EMERGING LO 2026
working retail, he helped a customer purchase thousands of dollars in merchandise. “I asked him what he did for a living,” Duran said. The customer replied he was a mortgage professional. “That sparked everything,” Duran said. He does not remember the man’s name, but said he remains grateful for the encounter. In his first year, Duran focused on both the technical side of lending and what he calls the human side of the business. “It’s not just about helping people get mortgages,” Duran said. “It’s helping them achieve their dream of owning a home.” He credits the first few borrowers who “took a chance” on him, as well as mentors who helped him understand the industry’s nuances. Glaiser said one activity remains non-negotiable as he builds his business. “It’s a failure of a day if you don’t find somebody new to talk to,” he said. Cold calling, he said, is not his preferred growth strategy. Instead, he acquires new leads “organically” he said. “Those referral partners now form the backbone of this business.” Rookies often get it wrong by trying too hard to sell, he added. “I don’t know the last time I’ve ‘sold.’ It’s building relationships,” Glaiser said. “If you have a really good reputation, why do you have to sell things? People want your service.” Another rising producer, Jorge R. Vasquez of CTR Brokers in Raleigh, N.C., built his business through a different channel: community outreach and social media. Before entering mortgage lending, he spent roughly eight years as a radio DJ hosting a prime-time show, a role that helped him build a sizable Facebook following that would later become a steady source of borrowers. He began investing in distressed trailer homes, renovating them, and selling them for profit.
“I realized a lot of the people who were really doing well also owned real estate,” Vasquez said. As he researched the market, he said he began noticing widespread misinformation within the Hispanic community about homebuying and financing options. “There’s a lot of misinformation,” he said. “People don’t know what programs exist or what they actually qualify for.” That realization pushed him toward mortgage lending. “I wanted to help educate people in my community,” Vasquez said. EARLY LESSONS IN LENDING Vasquez’s first experience in the industry came as a loan officer assistant working in the Raleigh market. Early on, he saw how important it was to handle approvals carefully. “I saw situations where people could lose money when approvals weren’t handled correctly,” he said. The experience shaped his view of the responsibility loan originators have to their clients. When he realized the impact mistakes could have on borrowers, he decided to move on and look for an opportunity to learn the business the right way. He later connected with a veteran loan officer and joined him as a loan officer assistant while continuing to attract borrowers through social media. “I was scared at first,” he said. “But I studied, got my license, and decided to go all in.” Today, his clients are primarily Hispanic borrowers, including those using tax identification numbers, self-employed borrowers qualifying through bank statements or profitand-loss documentation, and buyers who need credit coaching before qualifying. WORD OF MOUTH AND SOCIAL MEDIA Social media remains central to his growth strategy. “Facebook is where the money is,” Vasquez said. “Most of my audience is older and ready to buy.” Rather than relying heavily on
“Before telling someone no, I want to know for sure there isn’t a program that fits.” — Jorge R. Vasquez on using AI to find lending solutions
paid advertising, he posts closing photos and borrower success stories, which often generate new inquiries. “Realtors don’t want to babysit loans,” Vasquez said. “If the process runs smoothly, they send you more business.” LEADERSHIP AND SCALE Duran’s role has evolved as his business has grown. He now oversees eight staff members and focuses increasingly on leadership development. “I’ve been focusing on becoming a better leader,” he said. “Now it’s about connecting not just with clients, but with my team.” Vasquez is navigating a similar transition. About two months ago, he opened his own branch in Raleigh and hired his first loan officer, who recently completed his first closing. “I shadow him on everything,” Vasquez said. “I want to make sure things are done the right way.” ARTIFICIAL INTELLIGENCE ENTERS THE MORTGAGE WORKFLOW Artificial intelligence is becoming part of that system. As a broker working with roughly 14 lenders offering multiple programs, Vasquez said keeping track of guidelines had become overwhelming. About six months ago, he began utilizing AI by feeding it
lender guidelines and program descriptions. “It helps me find options I might have missed,” Vasquez said. “Before telling someone no, I want to know for sure there isn’t a program that fits.” Glaiser and Duran are also investing in technology. Glaiser is developing internal systems to automate workflow, including document review. “If I’m able to cut my time down by using AI, I have more time to get more business,” he said. Duran said he now operates with a proprietary customer relationship management (CRM) platform and is exploring additional AI tools to improve document processing and client communication. Still, both stressed that technology will supplement, and not replace, loan officers. “I don’t think the industry will ever go 100% AI,” Glaiser said. “There are too many variable factors and unique scenarios that you need a human set of eyes.” For rookies entering the business amid regulatory complexity and rapidly evolving technology, the formula is becoming clearer: pick a niche, build relationships relentlessly, and embrace tools that create efficiency. Adaptability — not experience alone — is increasingly defining who succeeds.
We Saved You A Seat The Mortgage Women Leadership Council (MWLC) is more than a professional network — it's a community where you can build meaningful relationships, grow your career, and find people who genuinely want to see you succeed. Whether you're new to the industry or a seasoned leader, you'll gain connections, support, and opportunities that remind you that you don't have to navigate your career alone. Join us and find your people.
Melissa Pianin Melissa Pianin Executive Director
Exclusive Originator Connect Offer For this event only, you can receive your first year of MWLC membership for just $50 using promo code OC26 at mortgagewomen.com/join.
8 Things To Learn From This Former FedEx Worker Turned Mortgage Broker BY ANDREW BERMAN | CEO, NATIONAL MORTGAGE PROFESSIONAL
B
efore he ever took on a loan application, Arthur Miguez of the Lending Spot worked at FedEx, not as a delivery driver but in logistics, ensuring packages moved through the system correctly and reached the right destination. He wasn’t stuck — he was progressing. But like many in corporate roles, he hit a ceiling. The structure limited his income and upside, prompting him to seek a role where effort and results were more directly linked. At FedEx, he learned that if the information is wrong, the outcome is wrong. That same mindset carried into mortgages. To Arthur, a loan is a logistics exercise, collecting information, structuring it correctly, and moving it through the process without disruption. As he puts it, his job is to take data and make it pretty, ensuring it reaches the closing table cleanly and on time.
LEARNING THE BUSINESS BEFORE PRODUCING Arthur didn’t begin as a producing loan officer. He started as an assistant, working on files and supporting an experienced originator. That experience gave him something most new originators don’t have — exposure to real transactions before being responsible for creating them. He learned how loans are structured, where they break down, and what matters in execution. By the time he transitioned into production, he already understood the process. 8 EARLY HABITS THAT BUILT HIS PIPELINE His early growth wasn’t driven by marketing systems or aggressive outreach. It came from consistent, practical actions that most originators either overlook or abandon too quickly. CONTINUED ON PAGE 12
10
|
EMERGING LO 2026
>>>
YOUR FUTURE LOOKS GOOD WITH CANOPY BETTER COMP
MORE CONTROL
PREMIUM SUPPORT
Competitive compensation. Lower corporate margins. Keep more of what you earn.
Proprietary platform. Smarter workflows. Build your brand.
Operations. Marketing. Recruiting. Training. A team behind every step.
READY TO UNLOCK YOUR POTENTIAL?
We’re recruiting the next generation of top mortgage producers. Join us for slim corporate margins, transparency, better comp, better tech & unrivaled autonomy. Scan the QR code below to learn more & enter for a chance to win:
WIN ME!
*Prize is one new pair of Ray-Ban Wayfarer Meta Glasses Retail Value of $225 - Winner drawn September 4th 2026 -CANOPY MORTGAGE, LLC • 360 TECHNOLOGY COURT, STE 200 • LINDON UT 84042 • 877.426.5500 Office www.nmlsconsumeraccess.org NMLS Consumer Access #: 1359687. Equal Housing Lender. EMERGING LO 2026
|
11
CONTINUED FROM PAGE 10
“... If the information is wrong, the outcome is wrong.” Those actions included: 1. Going directly to open houses instead of asking for meetings, putting himself in front of agents where business was already happening 2. Creating open house flyers and delivering them without being asked, providing immediate, tangible value 3. Using time as a competitive advantage by being present, available, and engaged with both borrowers and agents 4. Sharing information freely, including insights on listings and property values, without tying it to a specific transaction 5. Treating every deal as an opportunity to build relationships with listing agents, title companies, and others involved in the process 6. Maintaining accessibility by answering calls and responding quickly rather than relying on delayed communication 7. Learning guidelines early to build confidence and communicate clearly around loan scenarios 8. Keeping communication personal by prioritizing direct interaction over automated systems and generic follow-up Individually, none of these actions are complex. Together, they create a level of consistency and trust that is difficult to replicate. TRANSLATING ACTIVITY INTO PRODUCTION Those habits translated into meaningful production over time. At his peak as a producing originator, Arthur generated approximately $25–$27 million in personal volume. When including referrals and internal opportunities tied to his efforts, that number approached over $40 million. More recently, he continues to produce at a high level, generating roughly $26 million annually with a predominantly purchase-focused business.
12
|
EMERGING LO 2026
As his production grew, so did his role within the business. He became a resource for other originators, helping them structure deals, interpret guidelines, and navigate challenges within active transactions. That naturally evolved into a leadership position and ultimately into a partnership role. The company itself has scaled quickly, producing over $350 million in its first year and tracking toward $400–$450 million in year two. A SHIFT IN FOCUS Today, his focus is less on prospecting and more on supporting production. His time is spent helping originators structure deals, solve problems, and move transactions forward efficiently. Rather than focusing solely on his own pipeline, he is contributing to the organization’s broader output. A consistent theme in his approach is the role of effort, particularly at the beginning of a career. Many of the actions that helped him grow — showing up in person, spending time on calls, creating value without being asked — do not scale efficiently. They require time and attention. That is precisely why they work. Before systems and automation become relevant, those behaviors build the relationships and credibility on which everything else depends. THE FOUNDATION BEFORE SCALE There is a tendency in the mortgage industry to prioritize efficiency through scripts, automation, and lead-generation systems. While those have their place, they are often introduced too early. Arthur’s experience points to a different starting point. Be present. Be helpful. Be consistent. Over time, those fundamentals compound, forming the foundation of a durable business.
Win More Business Serve More Clients Close More Deals Entering the mortgage industry can feel like a challenge, but AngelAi ® takes the anxiety of the unknown away, giving you the confidence to win. New loan officers rarely survive because back-office and underwriting resources are locked behind top producers who get all of the attention, priority, and special treatment. With AngelAi's 24/7 Warranted Intelligence you get instant and warranted resolutions to the industry's most complex deals. With AngelAi YOU are the top producer and our only priority. AngelAi ® completely levels the playing field, bypassing corporate gatekeepers to give you instant access to institutional-grade, Warranted Intelligence. Every answer and automated scenario validation from AngelAi is backed by an ironclad company warranty, granting you the institutional power and transaction certainty that rookies traditionally lack. We handle the complexity and make the complex simple, providing on-the-spot training to crush objections and shifting guidelines. Stop fighting the hierarchy; let the power of the warranty handle the heavy lifting so you can spend your time selling, building referral relationships, and growing your business. Lock in your competitive edge at www.angelai.com
AngelAi is a technology solution built by Celligence LLC and has a licensing agreement with Sun West Mortgage Company, Inc. NMLS 3277 to deliver superior quality financial services to you. Mortgage and other financial services are provided by Sun West Mortgage Company, Inc. NMLS 3277. For licensed professionals only; not for consumers. EMERGING LO 2026
|
13
BUILDING TRUST WITH BORROWERS:
STREETFIGHTER VS. DIGITAL DREAMMAKER
> 14
|
Jonathan Fry, Loan Officer, My Community Mortgage
EMERGING LO 2026
The next generation of LOs strive to ‘reset the tone’ of the industry BY KATIE JENSEN | ASSOCIATE EDITOR, EMERGING LO
I
t’s a Thursday afternoon in New Orleans, and Jonathan Fry is suited up like he’s running for mayor. He’s not — he’s out to sell mortgages. In his local market, where handshakes still matter and happy hours double as networking events, Fry’s reputation precedes him. At 22 years old, the My Community Mortgage loan officer has a simple philosophy: “If all these older folks are bitching and complaining about why the real estate market’s tough,” he says, “I’m going to reset the tone.” He did it by going everywhere — rooftop mixers, open houses, lunch-and-learns — in a full suit and tie, making himself omnipresent and unmistakably professional. “For one entire year, I wore a suit and tie to every event. My business skyrocketed.” Meanwhile, 500 miles away and in 35 states at once, Daryl Lionnet, vice president of West Capital Lending, sits in front of a CRM, headset on, running a very different game. He’s built a national pipeline with digital ads, call center efficiency, and finely tuned scripts. His leads come cold and fast. His follow-up is relentless. “We’re basically doing what the big direct-to-consumer shops are doing,” Lionnet explains, “but with less layers and more hustle.” Fry and Lionnet represent the two dominant avatars of the modern mortgage originator: one built on boots and suits, the other on systems and scale. Yet, both have managed to close about 100 loans annually, proving there’s more than one way to build a thriving business in today’s market. Moreover, they’re resetting the tone of an industry that’s been defined by burnout, ego, and old-school hierarchies, moving it toward a model that rewards authenticity, accountability, and modern hustle. One does it through face-to-face connection; the other, through digital precision. Together, they signal what the next generation of loan officers looks like: confident, adaptive, and unapologetically self-made.
THE GENERATIONAL DIVIDE They’ve seen rate cycles come and go. They’ve weathered Dodd-Frank and danced through refinance booms. But once the average age of loan originators began to push 50, the industry’s most trusted faces became its most seasoned. According to MGIC’s October 2024 Loan Originators Survey, nearly two-thirds of loan officers (64%) were aged 50 or older with at least two decades of experience under their belt. The share of age 50+ originators ticked down from 66% in 2023. However, that’s likely due to older originators leaving the industry rather than younger originators entering, since the 2024 NMLS Mortgage Call Report shows how the
overall MLO workforce has been shrinking every year since 2022. More recently, the 2025 Top Producers Survey from National Mortgage News found that nearly 80% of respondents were over age 40, while only 18% were between the ages 31 and 40, and only 2% were under the age of 30. At the same time, homebuyer and seller demographics are gradually shifting toward younger generations. The National Association of Realtors 2025 Homebuyers and Sellers Generational Trends report shows that millennials between ages 26 and 44 make up the largest share of homebuyers, followed by younger baby boomers (ages 60 to 69) and Gen Xers (ages 49 to 59). The data indicates a stark generational gap in an industry grappling with both talent attrition and changing borrower demographics. As more seasoned professionals near retirement, questions remain about how effectively the next generation of originators will be recruited and trained — especially in a business long dependent on mentorship, relationship-building, and deep institutional knowledge.
NEW KID ON THE BLOCK Fry’s path started not with a CRM or national lead platform, but with a T-shirt his aunt made with a Cricut machine. “I was 21, wearing three gold chains,
EMERGING LO 2026
|
15
slacks that didn’t make sense, and teaching a lunch-and-learn,’” he laughs. “But I got business.” It wasn’t long before mentors — like industry veteran Jordan Gerard — told him he needed to dress the part. “You’re 22 years old. You’ve got to act more professional. People need to believe you’re the guy who can handle their half-million-dollar loan.” Fry took it seriously. He made a New Year’s resolution: every event, every outing — suit and tie. After that one simple change he says his business finally started to take off. What also took off was his visibility. “I went to every event I could find for three or four years,” he says. “My entire goal was to be omnipresent.” It worked. Nearly 100% of his business now comes from Realtor referrals. He immediately loops agents into group chats with clients after the first call, reinforcing the idea that they’re all on the same team. His job, he says, is to prove to the Realtor “why I’m the person they need to trust.” But it’s not just appearances. Fry closes loans by creating real relationships — with agents, with title reps, with insurance providers, and even with other loan officers. “One of my biggest referral sources is my title reps,” he says. “Their whole job is to market to Realtors. Why wouldn’t I want to be their best friend?”
THE DIGITAL DEAL-MAKER
Lionnet’s strategy is a world apart. Where Fry shakes hands, Lionnet builds funnels. His phone only rings when the CRM warms up the lead. His clients rarely know his face, but they do know his process — and it works. “I can say with 100% confidence that nobody can work that lead like I can,” Lionnet says. “When I get a client on the phone, they’re ready to talk. We go straight into the application.” Lionnet’s team runs on automation, texting, and filtering leads before he ever picks up the phone. Every three to four calls, he’s submitting a 1003. It’s all high-efficiency, high-volume, and high-conviction. From the jump, he bought in. “Month one, I wrote a $30,000 check for leads,” he says. “That’s what it took. And I believed in it.” That belief came from mentors, from data, and from results. Lionnet now manages a team, tracks metrics obsessively, and closes deals nationwide. “I market in
16
|
EMERGING LO 2026
“Month one, I wrote a $30,000 check for leads. That’s what it took. And I believed in it.” – Daryl Lionnet, Vice President, West Capital Lending
35 states,” he says. “If I don’t know the market, I just make the extra phone calls. Call the title company. Ask the questions. You figure it out.” His secret weapons aren’t suits — they’re systems: CRMs, dashboards, Excel spreadsheets, and call scripts honed to the millisecond. He even charges clients for hard credit pulls — after he’s already built enough rapport to make it a no-brainer. But even for Lionnet, it still comes down to connection. “In the beginning and end of the deal, they need to love you,” he says. “In the middle, your processor handles the grind. But you’ve got to sell the hell out of it on the way in — and show up again before the close.”
‘RESET THE TONE’ Fry’s rapid rise in the mortgage industry is fueled not just by his social savvy, but by his ability to tap into often-overlooked referral sources — especially title reps and insurance agents — to build a self-sustaining pipeline. “I don’t know anything better than a hard market,” Fry said. “So I was like, alright, I’m going to go hustle, I’m going to grind.” While many loan officers focus solely on chasing real estate agents, Fry recognized early on that title marketing reps are some of the most underutilized allies in the industry. “Their entire job is literally just to market to Realtors,” he explained. “They don’t have to worry about closing deals. They’re just out there building relationships — the same relationships we need.” By forging genuine friendships with title reps, Fry expanded his reach into networks he wouldn’t have accessed on his own. One of his closest connections, a title rep named Carmen, not only referred business to him — she invited him to events, co-sponsored open houses, and even coordinated introductions with new agents. “I can’t even explain how many people my title reps have introduced me to,” Fry said. “They’re meeting people that are outside of my sphere. They’re vouching for me when I’m not there.” Fry applies the same mindset to
insurance agents and even other loan officers, many of whom send him deals that fall outside their guidelines. These secondary channels became essential to his business model — especially in the early years, when building a Realtor network from scratch felt like an uphill climb. His other key strategy? Be everywhere, all the time. From hosting lunch-andlearns to attending every local industry event, Fry spent years saturating the New Orleans real estate scene. That visibility paid off — not just in recognition, but in trust. “People started realizing, ‘You’re everywhere,’” he said. “Well, I spent four years doing that nonstop.”
74% > percentage of the global
workforce by 2030, ranked mental health as one of their top societal concerns.
Perhaps his most creative strategy came from an unplanned brunch that snowballed into a movement. After one networking event, Fry and a group of industry peers went out for mimosas — and “The Brunch Munch” was born. What began as a social outing evolved into a 60-person monthly meetup that blended fun with professional connection. “We actually did a once-amonth event with the Brunch Munch,” Fry said. “And that group introduced me to so many new people. It wasn’t just marketing — it was building real relationships.” By leaning into authenticity, leveraging overlooked partnerships, and staying relentlessly visible, Fry built a
business that thrives on community. His advice to other originators is simple but powerful: don’t just chase the obvious leads — build a tribe of allies who will sell your name when you’re not in the room.
REJECTING UNNECESSARY GRIND Despite the fact that Lionnet conducts most of his business over the phone, he doesn’t consider himself a “call center LO” — at least not in the traditional sense. Nor would he describe West Capital Lending, the direct-to-consumer brokerage where he works, as anything like the high-pressure call center environment of his former employer, loanDepot. The workplace environment at West Capital Lending is uniquely aligned with the expectations and values of the younger generation of MLOs. A 2025 Deloitte generational survey found that Gen Zers, who are projected to make up 74% of the global workforce by 2030, ranked mental health as one of their top societal concerns, second only to cost of living. Millennials reported similarly, placing mental health higher on their list of priorities than any previous generation. In that context, Lionnet’s approach feels like a generational shift. Younger MLOs aren’t looking to grind through 400 calls a day for a 2% conversion rate and Lionnet’s model proves they don’t have to. By leveraging a CRM system and automated tools, he filters out unqualified leads and focuses his time and energy on high-value conversations that are more likely to convert. “The CRM does a lot of that for me,” he said. “I’m not being told, ‘Bob, screw you,’ which happens a lot if you’ve ever worked in a call center.” Previously, Nick Grobnagger, coowner of Green Home Loans, shed some light on the call center environment during his nine years working for Quicken Loans, now known as Rocket Mortgage, where “95% of the time you’re either not going to get someone or, if you do get someone on the phone,
EMERGING LO 2026
|
17
“One of my biggest referral sources is my title reps. Their whole job is to market to Realtors. Why wouldn’t I want to be their best friend?” – Jonathan Fry, Loan Officer, My Community Mortgage
Jonathon Fry (right) attendeds a professional networking event with this peers – dressed in his typical uniform, a suit and tie.
they’re going to be upset,” he said. Many call center originators refer to it as their “Boiler Room” experience, which might have been a great movie in the 1990s, but it’s not an experience that younger generations are looking to replicate. While West Capital Lending may source leads from the same digital publishers that power Rocket Mortgage, the key difference is how those leads are handled. Lionnet’s leads are filtered and nurtured through a CRM before they ever reach his desk, creating a warmer pipeline and cutting down on wasted calls. Instead of making his sales pitch to hundreds of people per day, some who aren’t even ready to pull the trigger, Lionnet devotes his time to productive
18
|
EMERGING LO 2026
conversations with borrowers who are already primed to talk. He further streamlines his workload by relying on his assistant and processor to handle most tasks once the loan is in motion. “I sell them really well,” he said. “Because I want to make sure in the beginning they love me, and at the end they remember why they love me.” He’s also taken steps to reduce overhead on the backend — including the rising cost of pulling credit. Lionnet used to absorb that expense himself, but as prices climbed to a total of $3,000 per month, he changed tactics. Now, he positions the credit pull as part of the borrower’s investment in the loan process. “I’m coming in to save the day, change someone’s life by turning their bills from
$6,000 to $3,000 on a mortgage,” he said. “So we run it … and we’ll say, ‘Hey, look, you don’t have anything to do annually,’ or, ‘Hey, we’ve got a 50% chance there and have to run the approval. Gonna be 80 bucks. What’s the card you want to use?’ And I charge the line. But at that point they’re already invested.”
TWO MODELS, ONE MESSAGE Fry and Lionnet couldn’t operate more differently, but they agree on one thing: this business is about relationships, whether you build them on rooftops or RingCentral. “There are a hundred ways to get rich in mortgages,” Fry says. “I want to know all of them.” For the new generation of LOs, the lesson is clear: pick your playbook, play to your strengths, and don’t be afraid to pivot. Whether you’re wearing a suit to brunch or a headset to a Zoom call, the deal goes to the one who shows up ready. And shows up relentlessly.
More Connections. More Opportunities. Nationwide. Premier events for mortgage originators and brokers to LEARN, CONNECT, & GROW
THE NEW ENGLAND MORTGAGE
UNCASVILLE, CT JAN. 13–15, 2027
YOUR SUCCESS. OUR MISSION. BAY AREA, CA SEPT. 15, 2026
TEXAS
MORTGAGE ROUNDUP
DALLAS, TX SEP. 1, 2026 MEET THE RIGHT PEOPLE:
Whether you’re looking to grow your pipeline, discover new lending solutions, build referral relationships, or stay ahead of industry change, Originator Connect Network gives you the education, connections, and opportunities to move your business forward.
THOUSANDS OF MORTGAGE PROFESSIONALS
Find your next event …
LEARN WHAT WORKS TODAY:
ARIZONA CALIFORNIA COLORADO FLORIDA GEORGIA
TOP EDUCATION FROM INDUSTRY LEADERS
GROW YOUR BUSINESS FASTER:
POWERFUL CONNECTIONS THAT GROW YOUR BUSINESS
ILLINOIS LOUISIANA MINNESOTA NEVADA NEW ENGLAND
NORTH CAROLINA PENNSYLVANIA TEXAS UTAH WASHINGTON
OriginatorConnectNetwork.com
EMERGING LO 2026
|
19
S P O N S O R E D
E D I T O R I A L
STOP CHASING LEADS — START WORKING YOUR CIRCLE
T
he mortgage market is tough right now. Rates are elevated, inventory is tight, and competition for every deal is fierce. But here’s what top producers know that average loan officers don’t: the market doesn’t grow your business — your system does. After 27 years in this industry and coaching loan officers to an average of 42% growth per year, I can tell you with certainty that the loan officers winning right now aren’t doing anything magical. They’re executing a simple, repeatable system while everyone else is waiting for the phone to ring. Let’s break down what’s working. FIRST, KNOW YOUR NUMBERS You can’t grow what you don’t measure. Before you do anything else, answer these questions honestly: • How many leads did you generate in the last 12 months? • How many turned into applications? • How many closed? The national average application-to-close rate is 33%. That means if you take 20 applications per month, you should close 6–7 loans. If you’re not hitting that, your problem isn’t the market — it’s your conversion system. Here’s the math that changes everything: the average real estate agent funds only one loan per year per loan officer. Read that again. So if you want to close 100 purchase loans this year, you need to be actively marketing to at least 100 agents every single month. Most loan officers are marketing to 8–10 and wondering why they’re inconsistent. THE CIRCLE OF REFERRALS: YOUR BUSINESS IN THREE MOVES Top producers don’t have complicated strategies. Every month, without fail, they do three things with their referral partners: 1. Educate Position yourself as the expert. Host a lunch and learn. Post educational videos. Send market updates. When you teach, you build influence. Keep your classes to 30 minutes, make them entertaining, and always end with an ask. 2. Appreciate “Pop by” your top agents with a branded gift and a personal note. Non-perishable items with your logo sit on desks and bookshelves for months. Every time an agent glances at
that baseball or coffee mug, you’re top of mind. Handwritten notes and personal video messages also go a long way. 3. Ask This is where most loan officers leave money on the table. Education and appreciation prime the pump, but unless you ask, you’re just a friendly face. Here’s a script that works: “I really love working with you and your clients. Are you working with a buyer or seller right now that I could call and give a quick mortgage quote? If so, would you give me their number and I’ll call them today?” Clean, direct, respectful. The loan officers who do this consistently are the ones closing consistently. FIVE REFERRALS FROM EVERY SINGLE LOAN Every loan you originate contains at least five referral opportunities. On every purchase transaction, you have access to: • The buyer’s agent — Always ask if they have other active buyers. • The listing agent — Call them the same day you receive the contract. Introduce yourself, explain your process, and ask to meet. Every listing they hold is a potential future buyer. • The client’s financial planner — Ask your client to rate their planner 1–10. If they score an 8 or above, call that planner. Financial planners are an almost completely untapped referral source. • The client’s CPA — Same system. Highrating CPAs are worth a meeting and a follow-up book. • The client themselves — They’re excited, they’re telling everyone they know. Send a gift to their office. Call weekly with updates. Remind them your business runs on referrals. Bonus: Don’t overlook insurance agents and title companies. Insurance agents have renters who may be ready to buy, and title reps know agents you haven’t met yet. WORK YOUR DATABASE LIKE IT’S A GOLD MINE — BECAUSE IT IS Your past clients are your lowest-cost, highestconversion lead source, and most loan officers ignore them after the closing gift arrives. The system that works is simple: • 12 emails — one per month, automated through a CRM • Four cards or newsletters — one per quarter,
mailed to their home • Two phone calls — one on their birthday, one for their annual mortgage planning review • One client appreciation event — rent a movie theater, host a cookout, give away turkeys at Thanksgiving If your database has 500 past clients and just 25% refer you to one lead this year, that’s 125 leads. At a 33% close rate, that’s 41 additional loans — without spending a dollar on paid leads. THE WEEKLY PLAN THAT MAKES IT ALL REAL Strategy means nothing without execution. Break your annual goal into quarterly targets, then into weekly non-negotiables. A sample week for a loan officer targeting $35M in volume looks like this: • Hold three lunches or meetings with referral partners • Have enough conversations with a direct ask for referrals • Post five social media videos and call everyone who comments • Conduct 10 past client review calls • Host or attend one educational or networking event Measure your results every Friday. If something isn’t working, adjust it like a coach adjusts the game plan at halftime. If you’re struggling with accountability, get a coach or an accountability partner. THE BOTTOM LINE The loan officers thriving in this market aren’t waiting for conditions to improve. They’re educating their referral partners, appreciating them consistently, asking boldly, and working every loan for five more opportunities. They know their numbers, they have a written weekly plan, and they execute it with focused intentionality. The circle never stops. Your competition is calling your agents right now. The question is whether your name is top of mind when that agent has a buyer who needs a lender. Make it your name. Work the circle. ABOUT THE AUTHOR Tim Davis is a 27-year veteran of the mortgage industry and founder of The Originators Guide. He has coached loan officers to an average of 42% annual growth using the Circle of Referrals system. Follow him at TheOriginatorsGuide.com.
Want more resources? Visit OGBizPlan.com to get started. 20
|
EMERGING LO 2026
EMERGING LO 2026
|
21
COVER STORY
‘When I Grow Up, I Want To Be A Mortgage Broker’ — Said No One How Taylor Behm found the industry by accident and closed 13 loans in his first month by mastering lead conversion and Non-QM borrowers BY ANDREW BERMAN | CEO, NATIONAL MORTGAGE PROFESSONAL
T
aylor Behm didn’t grow up thinking about mortgage guidelines or structuring deals. Like most kids, he was focused on sports and the idea of building a career around something he enjoyed. As he got closer to that path, the reality began to set in. Outside of being a professional athlete, the business side of sports can be demanding, time-consuming, and often doesn’t provide the level of control or financial upside many expect. Long hours, limited flexibility, and a ceiling that was difficult to break through forced him to reassess what he actually wanted from a career. That reassessment led him in a different direction. Behm credits James Dauglash with introducing him to the mortgage industry. The two met while working at a company that wholesaled real estate deals for investors. Dauglash had already been in the mortgage business for some time and is now at West Capital Lending. “James left the wholesale company before I did, but we stayed in touch. After I lost my job there, he reached out while we were already
22
|
EMERGING LO 2026
working on a financing deal together,” Behm said. “He explained the opportunity, the ability to build a personal brand and a real book of business beyond what I had in wholesale. Hearing about others making six figures a year — and even monthly — convinced me it was worth a shot. The rest is history.” STARTING AT THE TOP OF THE FUNNEL
B
efore he ever became licensed, Behm was already working inside West Cap, operating at the very top of the funnel. His job was to make initial contact with leads and determine who was actually serious about moving forward. That meant working through a high volume of calls, many of which went nowhere. Some borrowers were just exploring options, others were shopping rates, and many simply didn’t answer. Others made it clear they weren’t interested. He learned quickly that not every lead is an opportunity.
Rather than trying to pitch or force a conversation, Behm focused on asking direct questions. What are you trying to accomplish? Why now? What has prevented
>
Taylor Behm, West Capital Lending
EMERGING LO 2026
|
23
you from moving forward so far? His
approach was laid back, but intentional. If a borrower demonstrated real intent, he would get them to agree to spend five minutes reviewing their options with a licensed MLO and then pass the opportunity along. At that stage, he wasn’t responsible for structuring the loan. He was responsible for identifying who was worth the time. That role, while often overlooked, gave him a clear advantage. He wasn’t just learning products. He was learning people. FROM FILTERING TO PRODUCING
T
hat experience became his foundation once he got licensed. When Behm transitioned into a full production role, he was no longer starting from zero. He already understood how leads behaved, how to recognize serious borrowers, and how to move a conversation forward efficiently. At the same time, junior team members stepped into the role he had previously held, making those same initial calls and filtering through leads for him. He went from sorting through noise to working almost exclusively with signal. The results were immediate. Within his first month as a licensed originator, Behm closed 13 loans. He had not yet received his first commission check, but the pipeline he had built translated directly into funded volume. When I first met him at a West Capital after-party following the Texas Mortgage Roundup in Dallas, he was still in that first month and already producing at a level most originators take years to reach. KEEPING THE MODEL SIMPLE
A
s his business grew, Behm made a conscious decision to keep his process simple. Working within a brokerage environment that offers access to well over 100 lenders, he was given straightforward advice early on: focus on a small number of lenders with enough products on their shelves to solve the majority of borrower scenarios. He followed that. Today, most of his production runs through a core group of lenders and programs that cover roughly 90% of the deals he sees.
24
|
EMERGING LO 2026
Taylor Behm and his wife.
Instead of trying to master everything, he focused on mastering what shows up most often. The remaining scenarios require additional effort, but they represent a much smaller portion of his business. FINDING A NICHE IN BUSINESS OWNERS
A
significant portion of Behm’s business has developed around self-employed borrowers and business owners. These are borrowers who often run into issues with traditional underwriting, not because they lack income, but because their tax returns don’t
reflect it clearly. Many show minimal or even negative adjusted gross income after deductions, which creates challenges under guidelines shaped in part by the Dodd-Frank Act. Behm leaned into that gap. Using Non-QM products such as bank statement and P&L-based loans, he is able to help borrowers who have strong cash flow but don’t fit conventional guidelines. Rather than forcing deals into traditional boxes, he focuses on matching borrowers with programs designed for their situation. Over time, this has become a consistent and growing segment of his production.
CONVERSATIONS, NOT SCRIPTS
D
espite the volume, Behm’s approach to the borrower interaction remains straightforward. The majority of his business still begins on the phone. His opening is simple and direct, often referencing the initial conversation the borrower had with a junior team member before asking what they are trying to accomplish. From there, it’s questions. His natural curiosity drives the conversation, allowing him to uncover details that lead to better solutions. He is not focused on delivering a perfect pitch. He is focused on understanding the borrower well enough to identify the right path forward. One tactic that stands out is his willingness to disarm the borrower early. In some cases, he will tell them upfront that it is not a good market. It immediately shifts the tone and builds credibility, especially with borrowers
already fielding calls from multiple originators. Most of whom are just trying to move the process forward, not learning what motivated the borrower to make their inquiry in the first place.
his income has changed dramatically, and he is now in the process of purchasing his first home.
WORK ETHIC AND
hile his current business is largely driven by companyprovided leads, Behm is already thinking about what comes next. He has expressed interest in building a personal brand and developing a more direct-to-consumer pipeline over time. For now, the focus remains on continuing to produce, refining his process, and building on the systems that have contributed to his early success. His trajectory highlights something simple but important. The originators who succeed early are not the ones who know everything at the start. They are the ones who learn quickly, ask better questions, and put themselves in enough real conversations for that knowledge to compound.
OPPORTUNITY
B
ehm does not attribute his early success to anything unique. He points to the opportunity he was given and the responsibility to make the most of it. “I can’t grasp not working hard.” That shows up in his schedule. He is typically first in the office and last to leave, putting in 70 to 80 hours a week in the office, with additional time spent following up with clients outside of it. He describes himself as always available, constantly responding to messages, and moving deals forward. Before entering the mortgage industry, he made approximately $7,000 over eight months in a previous sales role. Today,
BUILDING WHAT’S NEXT
W
DIGITAL LIVE EVENTS
ACTIONABLE STRATEGIES FOR GROWTH, BRANDING, RECRUITING, AND PROFITABILITY.
FEATURED EVENTS: DESIGNED FOR LEADING LO s AND TOP EXECUTIVES
Sept 1 | Build-A-Broker Summit
LEARN WHAT TOP-PRODUCING LOS ARE DOING RIGHT NOW
Oct 6 | The Risk And Rewards of Going Non-Del
REGISTER FREE TODAY!
Nov 3 | How To Win Real Estate Investor Loyalty
at nmpignite.com
Oct 20 | The Good, Bad And Ugly Of Lo Comp
EMERGING LO 2026
|
25
LO UnComplicated A forensic look at where LO compensation really goes BY KATIE JENSEN | ASSOCIATE EDITOR, EMERGING LO
Here’s what the flyers say: • Edge Home Finance Corp. pays 275 basis points flat. • Loan Factory offers 100% comp to 1099s after a $595 fee. • NEXA Lending gives you 100% of loan revenue — plus access to coaches, DBAs, and full backend infrastructure. • Geneva Financial, a retail shop, claims its LOs make nearly twice the national average in net comp. • Retail shops like Fairway or CrossCountry tout benefits, base pay, and leads in exchange for lower splits. Sounds great, right? But here’s what they don’t put on the flyer: That 275 bps may shrink to 140 — or 50 — once tech fees, marketing reimbursements, admin charges, and upline overrides kick in. That 100% comp? It’s routed into a ledger you can’t touch without receipts, waivers, and a downline recruit. And that signing bonus? It might come with a clawback, higher rates, or a string of production thresholds designed to keep you paying it back long after you’ve spent it. The result is an industry where headline comp is more
26
|
EMERGING LO 2026
aspiration than outcome. Across retail, wholesale, and hybrid platforms, compensation models promise autonomy but often obscure accountability. They reward volume, rather than the quality of loans. And in too many cases, they leave originators chasing numbers they were never intended to reach. NMP reached out to the C-Suite leaders in both the wholesale and retail channels, like Edge Home Finance, NEXA Lending (formerly NEXA Mortgage), and Geneva Financial, allowing them to defend their company’s compensation models. Data has been collected from Loan Factory and Barrett Financial to compare LO comp structures. NMP also reached out to West Capital Lending, but the founders declined to participate in this story. In an effort to restructure the compensation model at Client Direct Mortgage — and stir up some drama in the Rocket Pro vs. UWM Facebook group — aspiring mega broker, Ramon Von Walker, asked originators from the major brokerages how they are currently compensated. His posts were certainly popular, accumulating over 500 comments in response, but most originators could not provide a clear answer.
T
hat points to an even bigger issue: It’s critical for originators to understand how they’re being compensated, because beneath every comp plan is a structure that determines who keeps the value, who carries the risk, and who gets left holding the spreadsheet. “There’s a great opportunity, because all of these companies are not serving the loan officer,” Walker claimed. “That’s why we created what we did. We feel as though we can take a lot of market share. We have strategies to go after those particular companies … ” THE ILLUSION OF HIGH COMP: GROSS VS. NET In his May 2025 article, “Compensation is Still Lender’s Largest Expense,” industry commentator Rob Chrisman observes that in the economic lull of the postCOVID refi boom, sales compensation has become the single largest cost for retail IMBs. As sales volumes gradually declined, compensation hasn’t meaningfully adjusted — and that inertia is straining lenders’ bottom lines. Why hasn’t comp been adjusted? Because, Chrisman notes, compensation is very difficult to change, culturally and operationally. Lenders fear being the “first penguin in the water,” slashing comp and risking a mass LO exodus. Yet some are experimenting: stripping base pay from low producers, offering lower comp in exchange for better pricing or marketing support, and using performance analytics to pinpoint which branches and originators actually deliver ROI. As retail IMBs struggle to retain talent without collapsing their margins, compensation packages from the wholesale channel have become increasingly theatrical: headlinegrabbing bps offers, full-revenue splits, and “100% comp” marketing hooks. The most common hook in loan officer recruiting, for example, is a headline number: 275 basis points, 300 basis points, even 100% compensation. Those figures often appear irresistible to originators comparing options across companies and
channels. But dig deeper and the math rarely holds up. Firms like Loan Factory advertise that 1099 LOs earn “100% comp,” while W-2 LOs receive 90% after fixed fees. On paper, that 100% payout sounds unbeatable — but it’s a bit like advertising a product as “free” after the customer
“LOs think they’re getting 275 bps gross — but net less than 140, or even as little as 50 bps in competitive scenarios.” — Aaron VanTrojen, CEO, Geneva Financial, on how an LO’s income is quietly eroded by concessions, overrides, tech fees, admin charges, and multilevel marketing splits.
pays $1,000 in fees. In reality, both comp models include a $595 administrative fee and a $500 processing fee, adding up to $1,095 per loan before any personal expenses. Although the mandatory fee is explicitly stated in Loan Factory’s advertising, some may find it misleading to call it “100% comp.” In such cases, the promise of full pay becomes more illusion than reality. “LOs think they’re getting 275 bps gross — but net less than 140, or even as little as 50 bps in competitive scenarios,” said Geneva Financial CEO Aaron VanTrojen. He argues that while broker and platform shops pitch aggressive compensation plans, much of that income is quietly eroded by concessions, overrides, tech fees, admin charges, and multi-level marketing splits.
1. Concessions Definition: Concessions refer to financial incentives or accommodations offered to close a deal. In mortgage and real estate contexts, these can come from lenders, sellers, or employers. Examples: • Lender concessions: A loan officer or lender reduces fees or offers better terms to keep a client or meet volume targets. • Broker/LO concessions: An individual originator may reduce their commission to make a deal work.
2. Overrides Definition: Overrides are additional compensation paid to managers, team leads, or brokers based on the production of others (usually loan officers under them). It’s a form of hierarchical commission. Context: Overrides incentivize leaders to recruit, mentor, and support productive team members. They’re typically a percentage of the revenue or margin from deals closed by junior agents or originators in their downline.
EMERGING LO 2026
|
27
3. Tech Fees Definition: Technology fees are charges assessed to cover the cost of software platforms used in the lending process. Examples: • Loan origination systems (LOS) • Point-of-sale (POS) platforms (like Big POS or Blend) • CRM integrations • eSign tools or compliance platforms Context: Sometimes charged per loan or monthly. Can be passed to the originator, the borrower, or absorbed by the company.
4. Admin Charges Definition: Administrative charges are flat-rate or percentage-based fees levied to cover general overhead for processing a loan. These can be internal fees charged to loan officers or external fees charged to borrowers. Examples: • File setup fees • Processing fees • Compliance review costs Note: These are sometimes controversial if they’re not clearly disclosed or appear as “junk fees.”
5. Multi-Level Marketing (MLM) Splits Definition: In an MLM or “tiered recruiting” model, splits refer to how commissions are shared among multiple levels in the downline and upline of a recruiting chain. Structure: • The originating LO gets a share. • Their recruiter/manager gets an override. • The recruiter’s recruiter may get a smaller override, and so on.
28
|
EMERGING LO 2026
DO YOU WANT SIMPLE COMP OR MORE COMP? Multi-Level Marketing (MLM) structures are more common in recruiting-heavy brokerages or platforms like those modeled after eXp Realty. It incentivizes growth via agent recruitment and creates passive income streams for recruiters. Those MLM structures can be difficult to untangle, but within them are mechanisms designed to maximize an LO’s earnings potential. NEXA Lending Chief Operating Officer Jason duPont admitted that his company’s LO comp structure “is probably the most complicated,” in response to Connect Mortgage Funding Terry Kashat’s comment on their “heavy MLM commission structure.” However, duPont insisted it’s “because there are so many pathways to 100%.” To clarify how NEXA’s comp model works, duPont calculates what a loan officer’s net commission would be on a $500,000 loan. He starts with the standard LO comp model for mortgage brokers before explaining how NEXA 100 works. On a standard $500,000 loan at 275 bps, the LO earns $13,750. NEXA Lending deducts 25 bps ($1,250) for its funding department and 12% ($1,500) for its profit margin, so the LO nets about $11,000 on that transaction. Net Commission Using Standard NEXA Comp: 1. $13,750 - 25 bps ($1,250) = $12,500 2. 12% of $12,500 = $1,500 3. $12,500 - $1,500 = $11,000 net commission But that 12% profit margin gets redistributed across three upline levels: 4% to the LO’s sponsor, 4% to the sponsor’s sponsor, and 4% to the next level above, duPont explained. So each sponsor earns roughly $500. So how does NEXA make a profit? If a recruiter leaves NEXA, the company does not compress the downline, duPont said. The recruiter’s spot is taken over by NEXA corporate, and all the overrides that would have gone to that recruiter
instead flow back to the company. Over time, this creates “holes” in the downline that NEXA profits from directly, which duPont said helps fund programs like NEXA 100 and same-day payroll. Under NEXA 100, duPont said that the 12% margin and 25 bps are reimbursed back into the LO’s “Growth & Marketing Ledger,” an internal account the LO can use to pay for business expenses, like computers, CRMs, leads, assistants, and more. They must either submit receipts for reimbursement or use a prepaid Visa card tied to the ledger. Net Commission Using NEXA 100 Comp: 1. 12% ($1,500) + 25 bps ($1,250) = $2,750 goes to the growth ledger 2. $11,000 + $2,750 = $13,750 (or 275 bps, 100% comp)
“If I submitted payroll today, it would show that I’m getting paid $11,000, and then there’d be another transaction on my growth ledger for $2,750,” duPont said. It’s a model that sounds generous up front, but access depends on conditions: LOs must submit receipts to spend ledger funds, 1099s must sign waivers to avoid double-counting tax deductions, and the company’s broader multi-level recruiting structure adds another layer to how “100% comp” ultimately works. Tom Ahles, chief growth officer at Edge, by contrast, asserts that simplicity and transparency are major selling points for ex-retail LOs who felt kept in the dark. He would prove his point by asking LOs, “If you did $10 million in volume, what is your W-2?” which typically elicits a long pause. Then, he’d emphasize that every LO at Edge is on the same flat 275 bps plan, with no sliding scales, no backend manipulations, and a strict $15,000 perloan cap. That’s to say, if that LO worked for him, he would know exactly what he was owed in commission. “So I’ll say with Edge, a hundred percent — it’s about as simple as you can get. There are other companies in the wholesale space that are a lot more complicated,” Ahles said. “I know for a fact ours is crystal clear.”
claims. In his response, Walker argued that the allegation about Client Direct increasing its monthly fee from $79 to $149 without notice is inaccurate. “Our loan officers were well aware that we were building out a much larger platform and that the monthly fee would reflect the added value,” he contended. Still, Mitchell’s comments highlight a broader industry tension between simple compensation and consistent execution. Even when pay structures appear transparent, loan officers say reliability Eric Mitchell NEXA Lending Chief Revenue Officer Eric Mitchell responded to criticisms against NEXA’s more complex comp model, saying, “Well, you can choose simplicity [but] then you’re leaving money on the table … I can go work for a bank and earn 80 basis points, and it’s simple.” SIMPLICITY MEETS SCRUTINY Client Direct Mortgage seems to take a simpler approach to transparency. Under its 275 bps model, a $500,000 loan yields a $13,750 gross commission. The company then applies a $495 per-loan flat fee and a $149 monthly technology fee. After those deductions, the loan officer nets approximately $13,106 — the highest takehome among the brokerages compared in this analysis. While Client Direct’s flat-fee model appears straightforward on paper, former Chief Revenue Officer Eric Mitchell says his experience at the company tells a different story. Mitchell, who now serves in the same role at NEXA Lending, said he left Client Direct in August of 2025 citing concerns about payroll consistency and company leadership. In an interview with NMP, Mitchell described the company’s management style as “unpredictable” and “volatile.” He claimed, for example, that recent increases to Client Direct’s monthly technology fee “caught many originators off guard.” He contrasted that experience with NEXA’s model, which he said offers more stable systems and faster commission payouts. When NMP later followed up with Walker, he refuted those
Tom Ahles
“Signing bonuses come with higher rates. It’s all artificially inflated to recoup the bonus.” — Jason duPont, chief operating officer, NEXA, arguing that large signing bonuses — offered more often in the retail channel — are a misleading lure.
— such as timely payroll, predictable fees, and clear disclosures — remains the true measure of trust. COMPLEXITY OF COMPLIANCE: ADMIN FEES & TAX LIABILITIES As compensation models grow more aggressive, they collide with rules that were designed to make pay predictable and fair. Company owners in retail and wholesale say technical violations have become routine, often justified in the name of competition or survival. Geneva Financial’s VanTrojen has been one of the most vocal on the issue, claiming that nearly all mortgage companies, whether retail, wholesale, or brokerage, may be violating LO comp laws, often without realizing it. “I would bet most CEOs of the biggest mortgage bankers have never read the comp laws. Not once,” he said. “I think what most of our industry has done is hired lawyers to figure out: where am I least likely to get sued? Where am I least likely to get shut down by the CFPB, right? What are the areas that we can operate in the gray, or even in the red, and we could probably fight it with just a big fine. You know, pay to play.” According to VanTrojen, misclassified borrower-paid transactions, illegal concessions in competitive deals, and selective pricing adjustments within the wholesale channel are the most common breaches. The pressure to keep advertised comp high also fuels creative, but legally risky, ways to push costs onto producers. Walker flagged a concerning trend
EMERGING LO 2026
|
29
in one of his posts to the Rocket Pro Vs UWM Facebook group: the practice of deducting employer payroll taxes from W-2 employee commissions. Several companies openly advertise an “admin fee,” which he surmised is also used to cover the employer share of Social Security, Medicare, and unemployment taxes. “You can’t just shift your legal tax obligation to your employees and call it a fee,” Walker said. IRS Code §3102 states that the “tax imposed by section 3101 shall be collected by the employer of the taxpayer, by deducting the amount of the tax from the wages as and when paid.” Code §3111 additionally mandates, “In addition to the tax imposed by the preceding subsection, there is hereby imposed on every employer an excise tax … equal to 1.45% of the wages … paid by the employer with respect to employment.” In other words, the employer must pay the employer’s portion of tax liabilities — no exception for commission-only W-2s. To reassign the burden is illegal. That backdrop makes allegations about “admin fees” especially sensitive. At Edge Home Finance, the compensation structure is a flat $995 per-file fee plus a 10% commission reduction. In online forums, multiple former employees allege that the 10% “fee” is intended to fund company payroll tax liabilities. “They’re smart enough to not articulate this in their comp plan,” one former employee claims. “But everyone there knows it’s being done.” However, Ahles responded to the claim by explaining that the 10% referenced in Edge’s compensation is not a fee, deduction, or charge to cover payroll taxes. “The 10% is simply part of our commission formula, as disclosed in our Compensation Addendum,” he stated. “Specifically, all commissions are calculated as gross commission minus 10%. This is not a withholding from wages already earned; rather, it defines the commission amount that is earned in the first place. Because the ‘pre-reduction’ figure is never contractually owed, there is no deduction from earned wages.” Ahles also said that the LO comp formula is clearly written, disclosed,
30
|
EMERGING LO 2026
“You can’t just shift your legal tax obligation to your employees and call it a fee.” — Broker Ramon Von Walker on companies openly advertising an “admin fee,” which he surmised is also used to cover the employer share of Social Security, Medicare, and unemployment taxes.
and signed by both parties, ensuring full transparency and compliance with wage payment laws. Despite Ahles’s assertion that Edge’s plan is simple and transparent, the mechanics of the 10% (which is framed as defining the amount earned rather than a deduction) can be difficult to parse for
originators comparing offers. In practice it means an LO’s commission is figured as 90% of the gross and then the $995 perloan fee is taken out. NEXA’s “100%” pathway presents a different compliance puzzle: how to deliver full revenue without violating LO comp rules. Under NEXA 100, duPont said the 25 bps funding charge and the 12% margin are reimbursed into an LO’s Growth & Marketing Ledger — dollars that can be used for business expenses via submitted receipts or a prepaid card. Attorney Ron Gapp, founding partner of Brody Gapp LLP, explained why that framing matters: reimbursements are not compensation. “If I go to a trade show, and I spend my own dime on that, and I’m now being reimbursed for that expense, that’s not income,” he said. The structure, however, is inherently conditional. For 1099 LOs, participation requires signing a waiver affirming they will not deduct the reimbursed expenses again on their taxes. The structure is complex, and while presented as an incentive program, it has drawn scrutiny for its opacity. One former LO commenting online described it as “basically correspondent where you get your fees reimbursed to your ledger … but you have to submit reimbursement receipts … and you have to send an email saying you won’t write off those expenses you’re getting reimbursed on.” On top of this, they added that NEXA charges a monthly “tech fee” of $75 to $85, depending on the platform stack selected. Taken together, reimbursement ledgers, admin fees, and layered overrides may help manage razor-thin margins, but they also obscure true pay and shift risk in ways regulators never intended. According to Walker, too many firms are driven by “recapture,” rather than sustainability or transparency; whether or not that’s fair, the tension feeds directly into the next battleground: recruiting economics. RECRUITING: BONUSES, OVERRIDES, AND THE FINE PRINT In the post-refi boom mortgage market, recruiting has become a profit center of
its own. Comp plans that once focused solely on production now increasingly reward originators for bringing in new hires. But, critics say those dual-purpose structures can create murky, pyramidscheme style economics. Walker argues that recruitment-driven comp structures, like those used at Edge and NEXA, create misleading economics, reinforcing the disconnect between advertised and actual earnings. At Edge, every loan officer pays a flat $995 per-file fee, but a portion ($500) of that fee is automatically routed to whoever recruited that particular loan officer. However, that policy comes with strings attached — also known as commission disqualifiers. Walker recalled a loan officer from Edge telling him that he should have gotten paid a $2,500 recruitment bonus because five of his recruits originated a loan that month. But, according to Walker, the loan officer claimed: “[Edge] swept my $2,500 … They try to say they put this rule in, but I knew nothing about it. If you don’t close a loan within the [same] month that the people you’ve recruited close a loan, then you forego that $500 portion.” When asked about commission disqualifiers, Ahles confirmed that Edge loan officers “need to have one origination activity within a 30-day period to qualify for that month’s recruiting bonus,” he said. “We rarely have anyone that doesn’t hit that, that takes advantage of our recruiting program. Which is why we paid out $10 million last year in our recruiting pay.” But Walker cast doubt, saying: “If you look at data, [Edge] loan officers don’t close loans every month. They close two loans one month, zero loans the next month. Three loans this month.” Here’s the data: Edge produced 17,271 loans in the past 12 months, according to Modex, and employs 1,219 loan officers in total, per NMLS Consumer Access. That equates to a monthly average of about 14 closed loans in the last 12 months for every loan officer at Edge. To Walker’s point, loan production is not evenly distributed across the company or for every month. But, data from Market Mobility Intelligence (MMI) shows that most of Edge’s loan officers (72%) produced, on average, one or more loans per month in 2024, which meets
the bonus pay threshold. The NEXA 100 program also comes with strings attached. The company grants every new hire access to 100% of loan revenue for their first six months, with continued access contingent on recruiting producing loan officers into their downline. Downlines refer to a network of individuals who join a company under a specific distributor, also known as the sponsor. The sponsor recruits these individuals, and they become part of the sponsor’s downline. The sponsor earns commission based on their own sales and the sales generated by their downline. Additionally, others note that sponsors can end up earning more from downlines than their own production — raising questions about where value is really being created. Jason duPont, the top recruiter
“If you have control over anything that they do, you are responsible as an employer.” — Irene Amato, owner, ASAP Mortgage, on the mortgage industry often presenting the choice between W-2 and 1099 employment as a matter of flexibility.
and Chief Operating Officer at NEXA, rejects that characterization. “You’re grandfathered in. We don’t want you just recruiting. We want you producing,” he said. DuPont positions NEXA’s offering as a blend of autonomy and infrastructure, particularly for former retail LOs who feel overcharged and undercompensated. Rather, duPont argued that large signing bonuses — offered more often in the retail channel — are a misleading lure. “Signing bonuses come with higher rates. It’s all artificially inflated to recoup the bonus,” he claimed. That argument is not unique to duPont. Many loan officers are familiar with the phrase “no free lunch” meaning that any company that pays a signing bonus has to recoup the cost somehow. Previously, Stratmor has discussed how signing bonuses become easier to justify when margins are wide, and harder when margins tighten. In tighter markets, the pressure to cover bonus costs would increase, making it plausible (though not explicitly stated) that lenders might raise loan pricing to absorb that cost. W-2 VS. 1099: CLASSIFICATION, BENEFITS, AND LEGAL RISK In the mortgage industry, the choice between W-2 and 1099 employment is often presented as a matter of flexibility. But beneath the surface, the classification decision carries cascading consequences: from benefit eligibility to operational control and legal exposure. Irene Amato, owner of the smaller, New York–based brokerage ASAP Mortgage, takes a hardline stance on this issue. With 21 staff members, Amato employs only W-2 loan officers and sees the misclassification debate as a settled matter. “If you have control over anything that they do, you are responsible as an employer,” she said. And misclassification risk is real. If regulators determine a firm has improperly classified employees as independent contractors, the fallout can include audits, civil penalties, and retroactive payroll and wage obligations. The risk is especially high where firms exert behavioral control — mandating use of specific tech stacks, assigning leads, or dictating process flows. Those practices undermine the independence that 1099 status is supposed to represent.
EMERGING LO 2026
|
31
“I would bet most CEOs of the biggest mortgage bankers have never read the comp laws. Not once.” — Aaron VanTrojen, CEO, Geneva Financial, on his claims that nearly all mortgage companies, whether retail, wholesale, or brokerage, may be violating LO comp laws, often without realizing it.
Lawsuits over the past few years have made that risk impossible to ignore. Since 2022, NEXA Lending has been defending itself in court against former loan officer, Damien Diaz, who claims that he and other former NEXAns were misclassified as independent contractors and thus denied minimum wage and overtime protections. Though the case is still pending, NEXA was ordered to pay $13,000 in monetary sanctions relating to a discovery dispute in 2024. Rocket Mortgage followed in 2024 with a $3.5 million payout after a lawsuit revealed it excluded commissions and bonuses from overtime calculations. Fairway, Better.com, and numerous credit unions have faced similar allegations,
often choosing to settle quietly. CrossCountry Mortgage is among the most visible examples. The company is currently facing multiple FLSA lawsuits from former LOs who allege they were paid recoverable “advances” that left them earning below minimum wage during slow months. Some were even sued by the company to recoup those advances after resigning. Attorneys argue that CrossCountry could have simply guaranteed a base wage but chose not to, exposing the firm to back pay and penalties. Meanwhile, the Department of Labor has made worker classification a top enforcement priority. A rule finalized in 2024 reinstated the long-standing
“economic reality” test, emphasizing control, dependence, and whether the work is integral to the business. Under that framework, most mortgage loan officers — whose roles are central to origination — are employees, not contractors. The DOL has warned that misclassification denies workers not just wages, but also protections like overtime, health coverage, and unemployment benefits. SUPPORT AND INFRASTRUCTURE: WHAT ARE YOU REALLY PAYING FOR? Behind every comp plan is another question: what infrastructure backs it up? In an industry defined by tight
LO Net Commission On A Single $500,000 Loan COMPANY
COMP RATE
FEES
EST. NET PAYOUT
Edge Home Finance
275 bps
$995 + 10%
$11,480
NEXA Lending
275 bps
25 bps + 12%
$11,000 NEXA 100: LOs earn $11,000 and and $2,750 is reimbursed to ledger same or next day
32
|
Loan Factory
250 bps
25 bps + 12%
$11,405
Geneva Financial
179 bps
No added fees/ deductions
$8,950
EMERGING LO 2026
margins and shifting compliance depersonalized experience she sees in statement still holds true. standards, support systems often make larger platforms: layers of recruiters, “The last report I saw from the the difference between high performance coaches, and “access” that often [Mortgage] Bankers Association was that and burnout. substitutes for true leadership. Unlike loan officer compensation was somewhere Retail firms argue that brokers, while mega brokers, Amato said “I don’t look south of 80 basis points,” VanTrojen leaner and more flexible, can fall short at [ASAP Mortgage] as a platform. I don’t added. “I’m assuming that’s net [income] on operational depth. VanTrojen believes look at it as I’m selling software. I see it currently for loan officer compensation. many LOs in the wholesale space are as I am letting this person into my world Right now, company wide, we average 179 unequipped to sell on value alone and rely — something that I’ve worked so hard for. basis points net, which far exceeds any too heavily on rate. “If loan officers today So they have to have certain standards to retail operation.” could earn 400 basis points, they would come into that.” — but they can’t because VALUE VS. they don’t know how to VOLUME: THE sell,” he said. MORAL MATH NEXA Lending, Behind every however, counters his compensation model argument with 30+ lies a more fundamental full-time coaches, direct question: is the business underwriting access, built for scale, or for and branding flexibility service? For some through DBAs as proof lenders, success is that platform brokers measured in speed and can rival retail on quantity. For others, infrastructure. it’s defined by integrity, But some brokers say compliance, and those tools come with borrower outcomes. caveats — or don’t always VanTrojen argues materialize. Walker that the industry’s noted that services like drift toward rate-based contract processing or selling undermines onboarding support professionalism. When often “don’t come up in margins compress, he the conversation” after — Tom Ahles, chief growth officer, Edge says, too many LOs an LO signs on. Instead, Home Finance contrasting their simple cut their commissions many find themselves compensation structure to the more instead of learning how chasing down help that complicated ones used at other companies. to sell value: a race to was promised in the the bottom that harms pitch. borrowers and erodes At smaller firms trust. like ASAP Mortgage, Meanwhile, Amato the model tends to emphasizes culture and be simpler — and, in accountability. “Do the right thing when Amato’s view, more accountable. “They At many retail shops, that extra support no one’s looking,” she said. Her model always have access to me,” she said. Every comes at a cost — often in the form of prioritizes mentorship, long-term growth, new LO is paired with a manager based on lower comp splits or tighter pricing. But and reputational integrity over brute experience, and Amato remains directly those fees may fund an entire back office: volume. involved in day-to-day operations. For her, compliance, marketing, processors, tech, As compensation wars heat up and infrastructure is a culture of proximity, scenario desks, and operations teams regulatory scrutiny rises, the question for mentorship, and ethics. that keep the pipeline moving. For some originators is no longer just how much She rejects the idea that staff size LOs, the tradeoff is worth it. For others, they’re paid, but what kind of professional or software equals support. “There’s a especially high producers with their own they want to be. bunch of different things you get with me. teams, it feels like diminishing returns. The industry may be in a volume slump. You get health insurance … team events However, VanTrojen argues that But the fight over comp reveals something … promotional items,” she said. “I’m a Geneva Financial offers the best of deeper: a reckoning over value, ethics, and small broker. But I provided that platform both worlds by paying his loan officers who mortgage lending is really built to because people need to think about their twice as much as the average retail LO. serve. future.” Geneva conducted an internal study It’s a pointed contrast to the in the spring of 2025 to confirm that
“So I’ll say with Edge, a hundred percent — it’s about as simple as you can get. There are other companies in the wholesale space that are a lot more complicated. I know for a fact ours is crystal clear.”
EMERGING LO 2026
|
33
The First 90 Days:
What New LOs Should Focus On To Build Early Momentum Industry leaders share the habits, partnerships, and borrower opportunities that help new originators move from learning the business to closing loans
F
BY CZARINNA ANDRES | MANAGING EDITOR, EMERGING LO
or every loan officer who makes it through their first year in the mortgage business, there are plenty who never gain traction. The difference isn’t always talent. More often, it’s what happens during those first 90 days. New originators enter the industry facing a steep learning curve. They are expected to understand guidelines, build referral relationships, generate leads, structure loans, and navigate a borrower landscape that increasingly doesn’t fit neatly into traditional lending boxes. Trying to master everything at once can be overwhelming. Yet industry leaders say the loan officers who gain momentum fastest tend to follow a surprisingly simple formula: spend less time trying to know everything and more time talking to people, building relationships, and leveraging the resources around them. One of the biggest traps, according to Pavan Agarwal, CEO of Sun West Mortgage Company and creator of AngelAi, is becoming paralyzed by the fear of not knowing enough. “The originators who struggle get paralyzed by the fear of looking unknowledgeable,” Agarwal said.
Days 1–30:
Learn Enough To Take Action One of the biggest mistakes new loan officers make is believing they need to become experts before they start prospecting. Agarwal says newer originators often become trapped in “study mode” while opportunities pass them by. “The originators who win are those who hit the pavement on day one,” Agarwal said. “In this market, speed is currency.” That doesn’t mean education isn't important. It means learning where to find answers rather than trying to memorize every guideline. Raymond Eshaghian, president of GreenBox Loans, recommends that new LOs create systems early: product folders, lender directories, borrower-question checklists, and notes on which lending partners excel with
34
|
EMERGING LO 2026
specific borrower profiles. “Borrowers need to have confidence in their LO,” Eshaghian said. “Being thorough and structured achieves this.” At the same time, industry experts stress that education cannot replace activity. “The ones who gain traction jump right into income-generating activities even though they don’t know everything yet,” said Tim Davis, chief growth officer at Canopy Mortgage. “Meetings, calls, conversations equal contracts.” For most new LOs, that means attending open houses, meeting real estate agents, joining local business groups, calling friends and family, and having as many mortgage-related conversations as possible.
“In the first 30 days, networking and conversations should be the priority,” Davis said. “Meet as many people as possible.” The goal isn’t to close a deal immediately. The goal is to build a pipeline.
Don’t Try To Figure Everything Out Yourself The fastest-growing originators also understand they don’t have to solve every problem alone. “The originators who succeed the fastest don’t go it alone,” Robert Senko, president of ACC Mortgage, said. “They leverage their wholesale lender as a strategic partner.” That partnership often starts with the
account executive relationship. “A strong account executive relationship should feel like having a Non-QM expert, deal strategist, and business partner in your corner,” Senko said. Paul Ottendorf, executive vice president of wholesale operations at Verus Mortgage Capital, echoed that point, noting that newer originators often wait too long before engaging lending partners. “We’ve watched a lot of originators come into this space, and the pattern is consistent,” Ottendorf said. “The ones who gain traction fastest treat their wholesale partner as a strategic resource, not just a rate sheet.” Instead of waiting until a loan runs into trouble, successful LOs engage AEs early, discuss scenarios upfront, and use lender expertise to identify potential solutions before presenting options to borrowers. Eshaghian said newer originators can accelerate their learning curve by treating every closed loan as a learning opportunity. Once they see how a lender conditions and approves a particular file, they should incorporate those requirements into future borrower document requests. That approach not only shortens the learning curve but also helps newer originators present themselves more confidently to borrowers and referral partners.
Days 30–60:
Stop Looking For More Leads And Start Finding More Solutions Many new LOs assume their biggest challenge is generating enough leads. Often, the real challenge is converting the opportunities they already have. “Many new LOs think they need more leads when they really need more solutions,” Senko said. This is where product knowledge begins to matter. Newer originators frequently walk away from borrowers who don’t fit conventional guidelines. Self-employed business owners, real estate investors, gig workers, ITIN borrowers, foreign nationals, and clients with recent credit events are often dismissed before all options are explored. Ottendorf says those situations are exactly where newer originators can differentiate themselves. “Complex scenarios are where we shine,” he said. “Self-employed borrowers, clients with imperfect credit histories, foreign nationals looking to purchase property in the U.S. — these aren’t dead ends. They’re opportunities if you have the right partner and the right product set.” Agarwal believes many newer LOs overlook borrowers who have already been told no elsewhere. “There is an enormous pool of potential
homebuyers who have been explicitly told by traditional institutions that they cannot buy a home,” he said. He also argues that newer originators often underestimate how many borrowers fall outside traditional employment and income models. Self-employed borrowers, gig workers, investors, and borrowers with multiple income streams increasingly make up today’s homebuyer pool, creating opportunities for LOs who understand how to identify financing solutions beyond standard agency guidelines. Rather than competing exclusively for the easiest borrowers, emerging originators can often gain traction by learning how to help borrowers who fall outside traditional lending boxes.
Why Non-QM Shouldn’t Be An Afterthought One recurring theme across nearly every lender was that newer LOs often wait too long to learn about Non-QM lending. “Non-QM should be part of a new LO’s toolkit from day one, not a last resort,” Senko said. Eshaghian agrees. “When your loan does not fit agency products from an income, credit, or property standpoint, Non-QM is your next stop,” Eshaghian said. He noted that many newer LOs overlook opportunities involving self-employed borrowers, property investors, and borrowers with prior credit challenges because they assume those files won’t qualify. In many cases, alternative documentation or Non-QM programs can provide a viable path to approval. Ottendorf said many of the borrowers newer LOs assume are unfinanceable are actually strong candidates for alternative lending solutions. “Before walking away from a deal, make a call,” Ottendorf said. “The answer is often yes.” The challenge for many new originators isn't a lack of access to these products. It’s that they don’t know enough about them to recognize the opportunity. Davis’s advice is straightforward. “Study up on guidelines at night and network during the day.” In other words, learn the products, but don’t let learning replace prospecting.
Days 60–90:
Build Repeatable Habits
As new LOs move into their third month, the focus should shift from individual transactions to repeatable systems. Eshaghian recommends paying attention to lender-specific documentation requirements and common underwriting conditions. When LOs understand what underwriters routinely request, they can collect documents upfront rather than repeatedly returning to borrowers for additional information.
He also warns against one of the most common rookie mistakes: making assumptions. “The two things that kill deals are moving too fast and assuming,” Eshaghian said. Ottendorf points to another critical habit: gathering complete information from the start. “Incomplete information and delayed communication are the most common culprits” when deals fall apart, Ottendorf said. Organization, consistency, and proactive communication become increasingly important as pipelines begin to grow. This is also the stage where referral relationships start becoming productive. Davis teaches what he calls the “educate, appreciate, ask” approach to referral development. The objective is simple: find one loan opportunity every day. That level of consistency, rather than sporadic bursts of activity, is what creates momentum.
What Momentum Actually Looks Like Many new loan officers imagine success in the first 90 days as a specific number of closed loans. Industry leaders define it differently. By day 90, momentum means having a growing referral network, a consistent pipeline, confidence in your ability to identify solutions, and strong relationships with the partners who help you get deals done. Ottendorf describes momentum as having “a consistent pipeline, a growing referral base, and genuine confidence in the solutions” being presented to borrowers. Davis offers an equally practical benchmark. “If you can be averaging one credit pull a day by day 90, then you’re building some real momentum.” Perhaps most importantly, successful originators learn what not to do. Too many new LOs spend their days watching webinars, endlessly studying guidelines, tweaking marketing materials, or searching for the perfect strategy. “Knowledge is critical,” Davis said. “But learn early in the morning and late at night. Spend your days prospecting.” The first 90 days aren’t about becoming an expert in every product or guideline. They’re about building habits. Agarwal noted that today’s borrowers don’t always fit traditional lending boxes. As selfemployed borrowers, gig workers, investors, and households with multiple income streams become more common, opportunities often go to the LOs willing to explore solutions others might dismiss. The loan officers who succeed fastest aren’t necessarily the ones who know the most. They’re the ones who have the most conversations, ask the most questions, leverage the right partners, and learn how to turn opportunities into closed loans.
EMERGING LO 2026
|
35
You Have The Right To Remain Pre-Approved Anthony Marone’s double life juggling lending and cold, hard justice BY KATHRYN FITZPATRICK | SPECIAL TO EMERGING LO
36
|
EMERGING LO 2026
O
n an average day you can find Anthony Marone driving home at dawn, the sun just beginning to edge above the Jersey skyline, one job behind him and another about to start. He clocks out from the night shift at the police department, catches a few hours of sleep, then heads into his mortgage office around noon. “My day is usually a 12 to 8 instead of the 9 to 5,” he says. “It actually works better for me.” It’s not the kind of double life most people would choose, but then again, most people aren’t built like Marone. He’s admittedly a bit “ADD,” unable to sit still for too long, and says that when he and his family go on vacation, he has a hard time chilling out. “We go to the beach for 10 minutes, [I’m like], ‘All right, what are we doing?’” What he’s not doing? Relaxing. Marone, who runs the show at Lend Mortgage in Morgansville, N.J., has been dubbed “your friend in the mortgage business.” And if you count up all the awards he’s received since he started lending, it seems like he’s got a lot of friends. He’s one of the Top 1% of Mortgage Originators in America — and not just once, but for several consecutive years. His trophy shelf includes marquee industry honors: Scotsman Guide Top Dollar Volume and Most Loans Closed; Five Star Mortgage Professional from 2018 through 2024; Social Survey’s Top 100 in America; and Experience.com’s Top 1% for 2023. Forbes Magazine even named him one of the Top 100 Market Leaders in America for Mortgage Bankers back in 2020. He was also profiled in both Forbes and Fortune in 2021 and 2022. Funny thing is, he never set out to build an empire. He just wanted to get off the extra shift. “DETECTIVE WORK, BUT FOR MORTGAGES”
>
Anthony Morone, Loan Originator, Lend Mortgage
Marone wasn’t trying to dominate at first, that wasn’t the point. “My goal was just to do a couple loans a month,” he says. “Not work overtime at the police department.” That’s it. That’s the whole pitch. He started lending in 2014, chasing a little side money, and before long, he was closing over $100 million a year. He credits his rise not to ambition alone, but to the guidance he had from day one. “Regardless of where you’re at in life, you always need a mentor and you always need a leader. You always need a coach. You need someone in your corner cheering you on, showing you the way. And that’s at any level, right?” Marone made a point of seeking out top performers and absorbing everything he could. “I needed to be with people that were on that level. So my goal was [to] surround myself with people that were best of the best. And along the way, I picked up a little bit from a lot of those people. Also … you need your processes in place.” “Anthony’s a very driven, hardworking guy,” says Steve Grossman, who previously employed Marone at NJ Lender’s Corp. “I mean, he has a full-time job as a police officer. He’s very entrepreneurial.” When Marone first started, everyone he knew on the force was getting a real estate license. While no hard data exists on how many police officers transition into real estate, specific local examples stitch together a pattern; for example, Ryan Springer, a Southold Town police officer with 19 years on the job, who started selling homes around 2006 as a side gig. Texas’s Brittani Firestone, a 14‑year veteran of the Dallas Police Department and part of the Texas Attorney General’s Fugitive Unit, left the force in late 2018 and pivoted full-time to real estate. There are numerous accounts, but Marone wasn’t interested in becoming one of them. “There were really no active police officers I knew that were doing mortgages in the state of New Jersey at the time,” he says. “I might have been the first or
EMERGING LO 2026
|
37
maybe second.” He wasn’t into sales. He was into solving problems. “I was always good with numbers. I was always good with solving problems,” he says. “I feel like that’s kind of what mortgage is. I’m almost a detective on each file I do.” Where others see paper, he sees clues. “We’ve been really good at structuring deals. I’ve never issued a pre-approval. We do due diligence up front.” Verifications, income, bonuses — he makes sure every detail is right before the borrower ever makes an offer. SAME BURGER, DIFFERENT STATE Crafting an award-winning mortgage brokerage while working as a police officer isn’t a game of chance. It takes discipline. And a schedule as regimented as a Model T production shift. Marone, in fact, likens his process to an assembly line — think Henry Ford, each person has a role to complete over and over. He calls it his “Perfect Mortgage Process,” a 130-point checklist that covers every inch of a file, from the first hello to the final handshake at closing. “Here’s your stage,” he tells new hires. “You’re the assistant? These are your tasks. You’re the processor? Here’s yours.” Marone is un-precious and straightforward about the whole thing. Blips in the process might happen, but they better not happen a lot. “You do it again, you’re getting written up. You do it again after that, you’re terminated.” That’s how a guy running on four hours of sleep after a night shift builds a company that Realtors trust more than the highest bidder. “I always say it’s like McDonald’s,” Marone says. “You get the same burger in New Jersey as you do in Texas. It’s not the people, it’s the process.” That’s how he treats loans. Same structure, every time. Same file flow, same expectations, same results. His personal routine is similarly tight, every bit as locked-in as the loan pipeline he built. Rather than a day of rest, Sunday is for planning. That’s when he maps out the week ahead. Who’s getting called. Who’s getting lunch. What fires need putting out before they even start. “Sales is no different than a diet,” he says. “If you don’t prep your meals on Sunday night, you’re screwed by Monday morning. It’s the same with outreach.
38
|
EMERGING LO 2026
Anthony Morone in his police uniform.
You don’t plan, you lose.” So he plans. Every week. Monday: 100 Realtor calls. Tuesday: pipeline review. Wednesday: drop in on CPAs and financial advisors. Thursday: lunches. Friday? A cigar and a couple of calls. The wind-down. “I grab a cigar and just start dialing. ‘How’s business? You surviving? Rates killing you yet?’” he says. “That’s how you stay top of mind.” And being top of mind is how you win even when you’re not the highest offer. “I had a deal where we were five grand under the other offer,” he says. “But the listing agent took ours because they knew we’d close. That’s the power of reputation.” YOUR FRIEND IN THE MORTGAGE BUSINESS For his reputation as “your friend” in the mortgage business, Marone is aware everyone might not be into his style. He’s
fast-talking, direct, very Jersey. “I know off the bat, listen, I’m not a great fit for everybody. I’m a little harsh around the edges sometimes … That’s who I am, though. 25% of the people I meet aren’t going to like me off the bat. And I’m okay with that. And that’s statistically, right? Not everyone is going to [be] like, I love you.” For those situations, Marone has a workaround. “I bring my guys to some of my meetings with me ’cause I go, there’s someone in that office that doesn’t like me. So I said, these are Realtors I work with in that office ... go after those people because they don’t like me. You’re the opposite of me.” Of course that only works when there’s a good team. With a staff of eight, and careful watch for personality and discipline, Marone tends to hire for attitude. “Not everyone’s a perfect fit. Some people chase the sign-on bonuses,
stuff like that. It’s tough. Recruiting is definitely a tough thing. I think it’s a lot about culture, a lot about personality … but what I feel is the work ethic, right?” And even with all that, he sometimes just takes a chance on a younger, less experienced LO. “We have a couple newer guys I took a shot on … I think you gotta give back and you gotta bring up the next generation of loan officers … the problem obviously is the work ethic.” Marone’s belief in bringing up the next generation of LOs stems from his early work with Steve Grossman, who, at the time, was CEO of NJ Lending Corp. As a newcomer, Marone was known for his energy and ambition, but it was his ability to follow through that left an impression. “I’ve coached a lot of loan officers and mentored a lot of loan officers,” Grossman says. “And where Anthony is — where I compliment him — is he’s an implementer. If someone told all of us to go on a diet or do 10 exercises, 90% of us do it for one day and stop. One thing with Anthony: he’s very good at implementing and execution.” THE LONG GAME In its current state, Lend Mortgage is chugging along steadily, but true to character, Marone has plans to get bigger. Currently licensed in New Jersey, Pennsylvania, and Florida, he’s got visions of 100 loan officers on his team, an army of well-oiled lenders with the mission to close. But all that takes time — and he’s not rushing anything. “A lot of successful companies that are around 25, 30 years now … that’s not something they built out overnight or quickly. I think it’s a long steady drive to get to.” With that in mind, Marone, though restless, is mindful about what he takes on. It’s a lesson he learned firsthand when his side hustle started to take on a life of its own. In the lull after the post-pandemic mortgage boom, he fulfilled a longtime dream and opened a high-end cigar lounge with a fellow cop. “We built it out really nice … 100 lockers, key card access, cappuccinos, macchiato, Pelligrino,” he says. “At one point, we had 150 members.” For a while, it worked. Cigars were his one reliable off-switch. “I can’t sit still,”
If you’re not growing, you’re dying. For Marone, complacency is the enemy. He’s not content to coast on past success or settle into a comfortable niche. Even after building a highvolume shop from the ground up while working full-time as a cop, he’s still thinking bigger.
he says. “But cigars always relaxed me. That was the only time I sat still.” But among policing, lending, and cigar-shop running, something had to give. “I knew my limitations,” he says. “I can’t be working payroll for two companies.” In May 2025, he sold the lounge. Still, cigars remain part of the routine. By the end of the work week, the pace slows just enough for a smoke and a few calls. It’s part ritual, part relationship maintenance — a weekly moment of connection before the grind resets. The grind, for Marone, is the thing that keeps everything else moving — the constant rhythm of building, refining,
pushing forward. It’s not glamorous, and it’s not always easy, especially in a market where even seasoned originators are struggling to stay afloat. But for him, structure is survival. “If you’re not growing, you’re dying,” he says. With company growth on the horizon, Marone’s not pacing the floor like some cigar-chomping dreamer who only talks about disruption. He’s making lists, laying bricks. “Why stay a small company?” he says. “Why can’t I take this to the next level? Why can’t I do what Bezos did?” So he keeps at it — the cop with the file folder in one hand and the long view in the other. One more loan. One more rep. One more week of Sunday-night planning so Monday doesn’t kill him. You can call it discipline. You can call it obsession. But around New Jersey, they just call it closing time. And Officer Marone is always on duty. 5 KEY TAKEAWAYS Anthony Marone starts his day as a cop and finishes it as a top-producing mortgage broker. He somehow balances both lives with a mix of grit, caffeine, and a 130-point checklist that keeps every loan moving. Marone never set out to build a mortgage empire. He just wanted to stop working extra shifts at the police department. But once he got started, his side hustle took off, and he turned it into a $100-million-a-year business with the kind of structure you’d expect from someone who still wears a badge. He knows he’s not everyone’s cup of tea — fast-talking, no-nonsense, very Jersey. But Marone leans into who he is, and builds teams that balance him out. He backs people with hustle, not polish, and believes the right culture beats the perfect resume. Marone treats his calendar like a tactical map. Every Sunday, he plans the week ahead — calls, meetings, outreach — so when Monday hits, he’s already moving. It’s not flashy, but it works, and it keeps him ahead in a crowded market. At one point, he was running a mortgage company, working the night shift, and managing a luxury cigar lounge. Eventually, something had to give. Now he’s focused on growth, and taking things one loan, one rep, and one carefully planned week at a time.
EMERGING LO 2026
|
39
SAVE
Make Count For Your Career
50%
ALL CE-COURSES through 8/31/26
Complete your CE. Stay compliant. Keep moving forward
100% ONLINE Take the courses on your schedule, anywhere
NMLS APPROVED Trusted education. Keep your license safe.
QUICK & EASY Finish faster with engaging content
Why MaxClass? ENGAGING & THOUGHTPROVOKING CONTENT Real world topics that inspire and inform.
HUNDREDS OF 5-STAR REVIEWS Proven results from professionals like you
CUSTOMIZE FOR YOUR NEEDS Tailored solutions for companies and teams
ALL TRAINERS ARE LICENSED ORIGINATORS Learn from active pros who know the industry
LIVE IN-PERSON & ONLINE OPTIONS Flexible training that fits your world
BOUTIQUE STYLE SERVICE Personal support. Real relationships
Don't wait
Save
50% now
Use code SUMMERCE at checkout
40
|
EMERGING LO 2026
LOVED BY THOUSANDS
HHHHH CE classes can be a drag, but MaxClass made the day go by faster.” James George
HHHHH “My favorite CE class— engaging, easy to follow, and painless.” Juan Stewart JR
HHHHH “Dynamic class. Incredible instructors. Definitely won’t be my last.” Shelley Siegel
MAXCLASS.COM
NMLS-Approved Education NMLS Provider #1405088
Brokers Pivot From Trigger Leads to Trusted Advisors New legislation guts access to trigger leads and brokers scramble to reinvent their pitch BY KATIE JENSEN | ASSOCIATE EDITOR, EMERGING LO
W
hen the locally-focused, Pennsylvania-based brokerage Red Tree Mortgage was acquired by West Capital Lending in 2024, Alex Reinig traded his CEO title for Vice President. But a more seismic shift was already underway: Reinig’s brokerage was built on trigger leads and lightning-fast closings, but the strategy that had once fueled his rise was now imploding under its own success. Once a staunch believer in trigger leads, Reinig built a thriving operation around quick-turn transactions, at one point closing 200 loans per month. But by 2023, he was watching the strategy crumble under the weight of industry oversaturation and predatory practices. He wasn’t alone. Industry leaders within the broker community, like AIME Chairman and President of Next Door Lending Jonathan Haddad, were pivoting from trigger leads to become trusted sales advisors. Meanwhile, major advocacy groups like the Mortgage Bankers Association (MBA), National Association of Mortgage Brokers (NAMB), Brokers Action Coalition (BAC), and Community Home Lenders of America (CHLA) were rallying support for legislation to curtail trigger leads altogether. “No other industry in America has a practice like this,” said Steven Grossman, SVP of Retail Lending at Luminate Bank and CHLA member, who describes how credit bureaus sell consumer data after a mortgage credit pull. “Your phone blows
Today, Reinig said he’s grateful he weaned off of trigger leads before Congress passed a bill that is expected to severely limit their distribution and completely cut off access to mortgage brokers. WHO DOESN'T WANT QUICK MONEY, RIGHT?
Alex Reinig
up … 30, 40, 50, 60, 70 calls.” At first, Reinig believed trigger leads encouraged competition and gave consumers access to better deals. “But after so many players got in the game, I ended up seeing and hearing about so many bad companies out there,” Reinig said. “Friends who had burners who would call [or] text customers after their phone numbers were added to the Do Not Call list.”
Red Tree Mortgage started in 2019 by self-generating leads. But by late 2020, Reining began experimenting with trigger leads — a practice where lenders buy lists of consumers who recently had their credit pulled for a mortgage inquiry. “Obviously, [as] mortgage brokers … we want to get paid quickly,” Reinig said. “So we looked at trigger leads, the quick transaction. Why? Because the customer has already applied somewhere. Whether it be a bank, a credit union, another broker, or what have you.” He then realized that trigger leads produced quicker transactions, on average, compared to self-generated or internet-purchased leads. It was an irresistible pitch: “Can I ask you, what rate were you quoted? Well Tom, my local lender just pulled my credit, and he offered me 6.5. Well, that sounds great, Tom, but guess what? What if I told you I could offer you 6%? Well, hell, I’d rather go with you instead,” Reinig recounted. Over the next four years, Red Tree Mortgage began to flourish, closing 200 loans per month solely on trigger leads. It didn’t take long for the company’s wholesale partner, Rocket Pro (then
EMERGING LO 2026
|
41
“Obviously, [as] mortgage brokers … we want to get paid quickly. So we looked at trigger leads, the quick transaction.” > Alex Reinig, Vice President at West Capital Lending and former President and CEO of Red Tree Mortgage
>
42
|
EMERGING LO 2026
Alex Reinig
called Rocket Pro TPO), to recognize Reinig’s growing volume of business — which was impressive even during the peak years of the refinance boom. That’s what Reinig calls “quick sale, quick blood.” But, what started out as a somewhat niche tactic among mortgage brokers became a bloodbath after sharing his algorithm and tech stack with his peers at one of Rocket’s fireside chats. “I’m talking to all the owners, trying to help them to flourish,” he said. “It was like throwing tuna into a tank full of sharks. Boom! Exploded. So now, fast forward three years later, it’s like you pull a trigger, you pull credit [and] that person’s getting 150 phone calls within the first two hours.” BROKERS ARE BANNED On August 2nd, 2025, the U.S. Senate gave unanimous consent to pass H.R. 2808, the Homebuyers Privacy Protection Act, to restrict how consumer reporting agencies (CRAs) can furnish consumer reports — specifically limiting the use of trigger leads. The bill, put forth by the Mortgage Bankers Association and supported by major trade associations including the Brokers Action Coalition (BAC), prohibits CRAs from selling consumer reports to third parties in connection with a mortgage credit inquiry unless certain strict conditions are met. Under the bill, a CRA is barred from providing a consumer report based on a mortgage credit inquiry unless the recipient is making a firm offer of credit (FOC) or insurance, and one of the following applies: 1. The recipient has written authorization from the consumer. 2. The recipient has an existing relationship with the consumer by: • Originating their current mortgage loan • Servicing their current mortgage loan • Being an insured depository institution or credit union that holds an active account with the consumer Most mortgage brokers meet none of these conditions since they do not service loans, nor do they hold consumer accounts like banks or credit unions.
Trigger lead transactions also rarely involve prior consumer authorization. Because of these stipulations, brokers would be effectively cut off from purchasing trigger leads, as they cannot certify a firm offer of credit without a direct consumer relationship or prior consent. While retail shops, banks, and credit unions face limited access to trigger leads, Steve Grossman points out that mortgage brokers are likely to be shut out altogether, since they typically can’t issue firm offers of credit independently. “A mortgage broker cannot make a firm offer of credit. And you know what, I’m not a broker. So f*** the brokers,” Grossman said bluntly. “They weren’t the lenders. They’re not the servicers. I lent the money.” However, the “firm offer of credit” (FOC) requirement to access trigger leads was already in effect due to the Fair Credit Reporting Act (FCRA). Technically, if the FOC rule is what eliminates mortgage brokers from qualifying for trigger leads, they should have never been able to access them in the first place. Still, Grossman acknowledged that brokers could potentially regain access to trigger leads indirectly. When asked whether mortgage brokers could make a firm offer of credit by getting some form of approval from their wholesale lender that is servicing the borrower’s current loan, he admitted that it’s a possibility. “The thing is, that could become another cottage industry,” he responded, “where a wholesale lender might say, ‘Hey, you know what? We’re gonna protect you. If we get the trigger, we’ll give the lead back.’ And I’m sure the ones with very good technology may give it back at a discounted commission.” RISING COSTS AND TIME SPENT PER LEAD After going cold turkey on trigger leads, Reinig pivoted to purchasing longform leads from LowerMyBills.com, LendingTree, Free Rate Update, and Facebook. Unlike trigger leads, these prospects were still in the early stages of their buying journey, requiring longer nurturing cycles and making ROI much harder to track. “As an owner, oh my gosh, I’m going to
spend $20,000 a month on LendingTree leads, which there’s no way for me to measure an ROI because they may not buy or refinance,” he said. “So I really don’t know when I’m going to get my money back. And no owner wants to do that, whereas [with] trigger leads, you’re probably going to close within 30 to 60 days.” Today, a $20,000 monthly spend gets Reinig’s team only about 45 leads a day — down drastically from the 1,500 leads they’d receive in the heyday of trigger leads. “The sale is different up front because instead of selling a rate, you’re selling yourself,” Reinig said. “So you need to be prepared … Now I have to actually sell myself as a company and why I am the right person to do business with.” IMBS, BANKS, CREDIT UNIONS FACE LIMITATIONS Despite advocating for the Homebuyer Privacy Protection Act, Grossman acknowledged that trigger leads had operational advantages for his retail shop and, most likely, others. They weren’t used solely for pricing battles — they also acted as early alerts when prospective borrowers were “cheating,” i.e., applying with another lender. That insight, he said, was especially helpful in long sales cycles or refinance markets. “If you’re a good loan officer, you’re gonna continue to follow up … but most people don’t do that,” Grossman said. “It’s like your partner tracking you on your phone … if your partner sees you at an old boyfriend or girlfriend’s house, they know you're cheating. That’s what we used the trigger leads for.” But prospective borrowers are not existing customers. A Luminate originator might have spoken to them a few times but never originated or serviced their loan. Under the proposed legislation, retail lenders and banks can no longer use trigger leads to monitor prospects. Unless they originated or service the consumer’s loan, or hold their bank account, they’ll need to obtain consent. “These people didn’t close the loan with me. They’re just a prospect. So I’ll lose out on the prospects when I would catch them cheating on me,” Grossman said.
EMERGING LO 2026
|
43
“A mortgage broker cannot make a firm offer of credit. And you know what, I’m not a broker. So f*** the brokers. They weren’t the lenders. They’re not the servicers. I lent the money.” > Steven Grossman, Senior Vice President of retail lending at Luminate Bank, speaking candidly on the impact of trigger lead restrictions and emphasizing that mortgage brokers may be shut out altogether since they cannot issue firm offers of credit independently.
BUILDING A SALES ADVISORY CULTURE Once Reinig recognized the growing backlash against trigger leads, he redirected his focus on transforming his sales team into sales advisors — a shift that’s become even more critical as brokers face losing access to them altogether. “The way I tell my staff is this: Hey guys, we are transitioning from a sales person to a sales advisor, okay? A sales person is going to sell you the lowest rate, lowest cost right on the phone right now. A sales advisor is going to point you into the right direction of where you should financially be,” he said. The sales process involves walking clients through different loan scenarios such as comparing home equity line of credit payments, cash-out refinance rates, and amortization schedules. “You become a loan advisor because now you have to do so much other work to prove which scenario is better for your client,” Reinig continued. “And if you
44
|
EMERGING LO 2026
don’t want anything, listen, I’m going to shake your hand and I’m gonna let you go your way. But I want to be able to provide you with the best option for your family.” Matthew Blackmer, Vice President of Business Development at West Capital Lending, said the industry has reached a point where loan officers can no longer succeed by simply undercutting rates. “The days of a singular professional on their own are long gone. The game is too complex now to not be in a collaborative environment,” Blackmer said. “If you’ve been working on business solely by undercutting the frontline competition, you haven’t been needing to sell your value and most likely are out of touch of what that unique value proposition is.” For Reinig, the pivot is clear. “Right now, I sell the reputation of my company. Hi, I’m Alex Reinig. I’m a vice president here with West Capital Lending. We are the number one brokerage in the nation. We have partnered with 154 other lenders, where my job is to get you the lowest rate with the lowest cost.”
NEXT STEPS FOR MORTGAGE BROKERS The use of trigger leads may have been accepted and even championed within Reinig’s circle of peers, but it was becoming more controversial among the broader community of originators. And, perhaps, no one remembers it better than Chairman of the Association of Independent Mortgage Experts (AIME) Jonathan Haddad. Within the first few months of leading AIME, Haddad came under fire by AIME’s own members once they discovered that his brokerage, Next Door Lending, was using trigger leads — a practice the association said it was against. Haddad responded to the backlash within the Brokers Are Better Facebook groups, stating, “In the event, if you as a broker, get any kind of issue with a credit trigger because of Next Door Lending, all you have to do is reach out to me directly and it will get handled right away. Only if you are an AIME approved member.” Now, as some broker owners and
originators may be faced with the same challenge, Haddad advises them to think about three basic fundamentals. Step 1: Stop Complaining And Get Focused Haddad’s first piece of advice is blunt but necessary: Don’t waste time complaining. “Yes, you can ask questions and try to figure out what’s going on — that’s fine,” Haddad said. “But don’t spend longer than a day or two on that. Don’t go complaining, don’t go talking to your neighbor. It’s not going to help anything.” Haddad cautions that regulatory changes surrounding trigger leads will play out soon enough, and lingering in frustration will only distract loan officers from preparing for what comes next. “Once this goes through, all the other cards will come into play and you’ll see,” he added. Step 2: Master The Funnel — Get Back To Sales Basics The next step, Haddad says, is to relearn the art of converting cold leads. That skill will become even more essential as regulatory changes and the decline of trigger leads reshape how originators fill their pipelines.
“Master the funnel. Get back to the basics,” he said. “Understand what makes a cold lead convert — not just because they’re shopping and racing to the bottom — but because you know they have a problem and you can solve it.” Haddad urges loan officers to audit their sales process: • How strong is your introduction? • Are you branding yourself effectively? • Can you build value and gain agreement quickly? • How solid is your follow-up game? • Do you have a repeatable framework for every call? “If I were to ask you, ‘How do the first three minutes of your phone call go?’ and you don’t have the same answer every single time, you’re not set up for success,” Haddad said. Step 3: Track Everything — Know Your Numbers Haddad emphasizes the importance of tracking every metric in your funnel. He expects this process to become even more critical when lead costs rise and sales cycles stretch out, as Reinig experienced after moving away from trigger leads. “If you don’t know your lead-to-credit pull ratio
“Understand what makes a cold lead convert — not just because they’re shopping and racing to the bottom — but because you know they have a problem and you can solve it.” > Jonathon Haddad, AIME
Chairman and President of Next Door Lending, shares advice on how mortgage brokers can refine their lead-generating skills after losing access to trigger leads.
EMERGING LO 2026
|
45
or your credit pull-to-closing ratio, that’s going to be a problem for you long-term,” Haddad said. “It’s gotten a lot easier to track this stuff, especially with AI, so don’t make excuses.” For loan officers in direct-to-consumer shops, where data isn’t always shared, Haddad advises tracking everything manually: • How many conversations does it take before you pull a credit? • How long does it take from credit pull to getting a client to do business with you? • How long does it take to fund a loan after the client agrees? • What’s your post-closing referral conversion rate? In addition to tracking metrics, Haddad says LOs need to shift from a transactional mindset to a relationshipbased model. • “Clients do, on average, 11 transactions in their lifetime when it comes to a mortgage. Be part of that process,” he said. “How do you build that relationship? What little things can you do to shift from transactional into relationship-based?” Haddad’s recommendations reflect a broader reality that consumer-direct brokers stand to feel the sharpest impact if credit trigger leads are curtailed. With high-intent leads that once fueled their sales engines suddenly gone, Haddad and Reinig both suggest that those originators rebuild their pipelines from the ground up by mastering cold lead conversion and implementing robust tracking to maximize efficiency. The shift also
46
|
EMERGING LO 2026
demands a deeper focus on relationshipbuilding, which can help offset higher acquisition costs and longer sales cycles. In a market where consumer-direct strategies face structural changes, early adoption of these tactics may determine which firms can sustain volume and which are left scrambling for business. BROKER STRATEGIES TO REGAIN TRIGGER LEAD ACCESS The “Homebuyers Privacy Protection Act” (HR 2808) is intended to help consumers by protecting their credit information, preventing fraud, and reducing the amount of solicitations they receive from competing lenders. It remains to be seen whether solicitations will actually decrease as a result. In the meantime, John Comiskey, author of the Reverse Engineering Finance newsletter, hypothesizes how it will impact various mortgage industry players. Comiskey warns that the “Homebuyers Privacy Protection Act” will significantly alter how brokers compete for borrowers. By curbing the sale of mortgage trigger leads, the law consolidates power in the hands of large servicer-originators while leaving brokers with fewer tools to retain clients. Large servicer-originators like Rocket Mortgage will enjoy less competition when recapturing borrowers for rate-and-term refinances. With a clearer path to reach their existing clients, they can act swiftly and aggressively. If that happens, wholesale lenders will likely feel the squeeze. Brokers’ reduced ability to fend off competitor offers can, by extension, impact wholesale lenders that rely heavily on broker-sourced business.
Comiskey optimistically included a number of actionable items to help brokers stay competitive. • Capture Borrower Consent Proactively: Comiskey advises brokers to make client consent for trigger lead data a routine part of the origination process. This is no longer optional — it’s essential. • Frame Yourself as a “Second Look” Lender: Brokers should craft marketing strategies that encourage borrowers to seek a second opinion before accepting a refinance offer from their servicer. Messaging should emphasize protecting the borrower’s financial interests. • Educate Clients About the New Law: Brokers can use this legislation as a touchpoint to build trust, explaining how the law protects consumer privacy but also reduces competitive shopping options unless clients actively engage with independent advisors. • Offer Value in Exchange for Consent: Consider bundling consent requests with value-add incentives — like financial checkups, rate monitoring alerts, or budgeting tools — to encourage clients to opt in. • Differentiate Through Advocacy: Brokers must lean into their role as unbiased advisors who can compare multiple lender offers, ensuring clients aren’t steered into a less favorable deal by their servicer’s “first and only” refinance pitch.
THE INSTITUTIONAL GATEKEEPER IS DEAD:
How Warranted Intelligence Levels The Playing Field for the Emerging MLO
E
ntering the mortgage industry today can feel like stepping directly into a storm of constant chaos. For a newly licensed mortgage loan originator (MLO), whether you are launching your career at a retail bank or setting out as an independent mortgage broker, the learning curve isn’t just steep; it is a vertical cliff. You are expected to master shifting agency guidelines, navigate complex regulatory frameworks, and build a book of business from scratch. But let’s be honest about the real reason so many emerging MLOs don’t survive their first three years: the structural hierarchy of the traditional mortgage ecosystem is rigged against them.
THE FAVORITISM OF THE GATEKEEPERS In almost every traditional retail lender and wholesale channel, elite resources are heavily guarded assets. They are locked behind gatekeepers and prioritized almost exclusively for highvolume top producers. • The Retail Reality: If a seasoned corporate mega-producer has a question about an unconventional DTI ratio or a complex self-employed borrower file, an internal underwriter answers their call immediately. • The Broker Reality: If a high-volume originator needs a favor, wholesale account executives (AEs) and lender underwriting desks will bend over backward to “get the loan done anyways” because of the massive revenue that producer commands. But what happens when you, an emerging MLO, try to get a complex file reviewed? Your emails languish in a generic underwriting queue or sit unanswered in an AE’s voicemail. Your scenario questions go unresolved while you watch your hard-earned real estate agent partnerships slip away due to turn-time delays. Without corporate leverage or large volume, a single mistake or guideline misinterpretation can kill a deal, damage your reputation, and end your career before it truly begins. This structural favoritism, whether
By Pavan Agarwal, Founder & CEO, AngelAi This means the systemic risk of the unknown is completely removed from your shoulders. AngelAi grants you the exact institutional power, financial backing, and execution certainty that newer retail LOs and independent brokers have traditionally lacked, allowing you to walk into a listing presentation or a meeting with a toptier Realtor with the confidence of a 20-year veteran.
MOVE FROM DEFENSE TO OFFENSE
driven by corporate retail politics or wholesale lender tiering, is exactly why the industry struggles to cultivate new talent, forcing rookies out while the gap between the top 1% and everyone else widens.
DISMANTLING THE HIERARCHY WITH WARRANTED INTELLIGENCE At AngelAi, we believe your potential should never be limited by corporate politics, lender tiering, or a lack of tenure. We designed AngelAi to completely dismantle this old hierarchy, bypass the gatekeepers, and hand you the ultimate competitive edge: Warranted Intelligence. Imagine having the industry’s most sophisticated, institutional-grade underwriting mind working exclusively for you, 24 hours a day, 7 days a week. AngelAi doesn’t look at your past production metrics or your monthly pull-through rate before deciding to help you. With AngelAi, you are the top producer, and your pipeline is our only priority. The true magic of AngelAi lies in the power of the warranty. In a world where a wrong answer from a branch manager, an assistant, or a distracted wholesale AE can cost you a commission, AngelAi delivers absolute certainty. Every single guideline interpretation, product scenario validation, and loan structuring answer provided by AngelAi is backed by an ironclad company warranty.
We manage the structural complexity of the mortgage market so you don’t have to. Instead of spending hours digging through secondary market handbooks or waiting days for an internal help desk or a wholesale help desk to reply, you can ask AngelAi complex questions and receive instant, compliant, and warranted resolutions in real time. If a client catches you off guard with an unexpected hurdle, AngelAi provides on-the-spot training and strategic insights to crush borrower objections on the fly. We turn the complex into the simple, transforming a chaotic workflow into a predictable, automated engine. When you eliminate the anxiety of the unknown and stop fighting an uphill battle against structural bias for basic support, your entire day changes. You are no longer trapped at a desk playing defense against paperwork and administrative roadblocks. Instead, you are freed up to do what actually grows your business: spending 100% of your time selling, pounding the pavement, and cultivating deep, trust-based referral relationships with real estate agents who know you can deliver a flawless closing experience. The era of waiting in line for permission to succeed is over. You do not need decades of tenure or insider corporate leverage to command the full power of an enterprise back office. You just need the right technology. Let the power of our patented, deterministic AI handle the heavy lifting while you focus on scaling your business. Lock in your unfair advantage, claim your seat at the table, and discover what it feels like to win at www.angelai.com. EMERGING LO 2026
|
47
Games Builders Play And How To Beat Them
A tactical guide for LOs to rescue deals and outshine preferred lenders BY ANDY BAKER | SPECIAL TO EMERGING LO MAGAZINE
In today’s high-rate, high-price market, new home sales have gained an edge. Builders are using aggressive incentive strategies to capture demand from affordability-strapped buyers. These incentives can be powerful and persuasive: mortgage rate buydowns, closing cost assistance, upgrade credits, and more. But while builders are offering these deals to steer buyers to their preferred lenders, those offers don’t always serve the buyer’s long-term interests. And that’s where independent loan originators come in.
48
|
EMERGING LO 2026
>>>
L
oan officers, brokers, and bankers who can understand, dissect, and compete with builder incentives are positioned to win not just individual deals, but long-term client trust. With new construction homes now representing over 14% of the market — the highest in two decades — LOs need to actively target this segment to grow their business. We’ll walk you through how to do exactly that. WHAT ARE BUILDER INCENTIVES AND WHY DO THEY WORK? Before diving into specific incentives, it’s important to understand how builders are able to offer such attractive deals in the first place — and why competing LOs can sometimes feel outgunned. Forward Commitments: The Builder’s Secret Weapon Much of the power behind builder incentives comes from forward commitments — a bulk rate-lock agreement between a builder (or their affiliated lender) and an investor or agency. Instead of pricing each loan individually at market rates, the builder gets a block of loans — sometimes for an entire subdivision — funded at a belowmarket rate in exchange for volume and certainty. This gives the builder a pricing advantage that most independent originators don’t have. With access to lower-rate capital, they can fund 2-1 or even permanent buydowns at a fraction of the usual cost — while still preserving their profit margin. That’s how builders can advertise below-market rates and throw in thousands in closing credits or design upgrades. From a consumer standpoint, it looks like free money. From the builder’s side, it’s smart financial engineering made possible by scale. Forward commitments also allow builders to advertise “special” interest rates on spec homes or quick move-ins — making it easier to clear inventory without dropping prices. For LOs, understanding this background is essential: you’re not just competing with a lender — you’re competing with institutional pricing power.
Why Lowering The Home Price Is The Last Resort Of all the incentives builders can offer, lowering the actual purchase price of the home is the most avoided — and for good reason. Builders are extremely protective of their pricing because every price reduction affects future appraisals, buyer perceptions, and the value of other homes in the development. Unlike other incentives that can be “wrapped” into the deal or disguised through structure, price cuts hit the comps — and the bottom line — directly. Reducing price also creates tension with recent buyers who paid more just weeks earlier. It can lead to cancellations, appraisal issues, or complaints from agents and homeowners. For these reasons, builders will explore every other incentive path first — including flex dollars, closing credits, and rate buydowns — before even considering a price drop. That’s why, when you do see a price cut, it’s usually on a spec home that’s fully built, sitting unsold, and approaching the end of a quarter or fiscal year. Even then, the home might have a very specific timeline or condition attached — like a mandatory quick close — to avoid resetting the pricing benchmark across the community. As an LO, knowing how rare price cuts are (and why) helps you frame builder incentives for what they are: smoke-and-mirrors margin preservation, not necessarily better deals. With all of that serving as backdrop, here are the five most common types of
builder incentives you’ll see in the 2025 market — and why they work: 1. Mortgage Rate Buydowns This is the most dominant incentive. Builders pay upfront points to reduce a buyer’s interest rate, either permanently or temporarily (e.g., 2-1 buydowns). In 2024, nearly 75% of builders offered rate buydowns. These are especially attractive because they reduce the buyer’s monthly payment — the most painful part of homeownership in a 7% rate environment. A lower rate not only helps with qualification, but also alleviates financial anxiety, which is a powerful emotional lever for builders to pull. 2. Closing Cost Assistance Builders often offer $5,000–$15,000 in credits for closing costs, particularly if buyers use their affiliated lender. This helps buyers overcome upfront cost barriers and is especially appealing to first-time or cash-strapped borrowers. While it doesn’t change the monthly payment, it makes the home feel more accessible. Buyers are often enticed by the idea of moving in with little or no cash due at closing. 3. Flex Dollars And Upgrade Packages Design center credits allow buyers to choose upgrades (like appliances or finishes), or in some cases, further buy down their rate. These incentives appeal especially to move-up or luxury buyers who want customization. Builders use these packages to add perceived value to
EMERGING LO 2026
|
49
5. Miscellaneous Perks These include long-term rate locks, prepaid HOA dues, or incentives on spec homes (e.g., quick move-ins). Builders are increasingly creative as they compete for limited buyer demand. Sometimes it’s not the dollar amount, but the convenience factor that seals the deal. A 6-month lock or waived HOA fees could be the deciding factor for a buyer who is on the fence. Why These Work: Incentives allow builders to reduce the buyer’s cost without cutting the headline price of the home — preserving comps and profit margins. And because many builders own or partner with mortgage companies, they can shift profit between the home and the loan. The result is a subsidized deal that feels too good to pass up. WHAT BUILDERS CAN’T OFFER — AND HOW LOs CAN WIN Despite the flashy incentives, builderaffiliated lending isn’t always the best deal for buyers. Loan originators can win the business by: 1. Exposing Hidden Costs
Phil Crescenzo, Division President at Nation One.
Builders often inflate the home price to fund incentives, leaving buyers with higher loan balances and potential negative equity if the market dips. A builder’s $20,000 rate buydown might come with a $25,000 markup on the home price. Buyers are essentially financing their own discount, and many don’t realize it until it’s too late. As an LO, you can present a clearer, more transparent breakdown of what the buyer is actually paying and what they’re truly getting. 2. Offering Flexible Financing
the home without cutting prices. Since the actual cost to the builder is often lower than the stated value, it’s a costeffective tactic that still feels generous to the buyer. 4. Price Reductions While far less common (although recent reports say that 37% of builders have recently reduced prices, with an average cut of 5%, due to high interest rates and overall weak demand), some builders reduce the base price of the home — typically on spec homes or
50
|
EMERGING LO 2026
inventory that must close quickly. As mentioned above, this tool is most often used as a last resort, particularly in oversupplied markets like the Southwest and Southeast. Builders avoid it at all costs because it affects appraisals and neighborhood comparables, effectively lowering the value for entire developments. If you see a price drop, it usually signals desperation — and an opportunity for an LO to step in with a creative, structured offer that protects the buyer’s equity.
LOs have access to a wider array of loan products and terms than most builder-affiliated lenders. This means you can match the loan to the buyer’s specific needs — offering a permanent buydown instead of a temporary one, or recommending an ARM to someone who plans to move in five years. While a home builder’s preferred lender might offer a Non-QM option, they most likely will not have the full menu of Non-QM products that LOs, brokers, and IMBs (ones that have made Non-QM a priority) can offer. This flexibility also means working with lower credit scores, unique income situations, or pairing a loan with a down
payment assistance program. These custom solutions show that you are acting in the client’s best interest. 3. Winning On Cash-To-Close Cash-to-close is one of the most important figures for today’s buyers. LOs can compete directly here by leveraging lender credits or adjusting compensation structures to reduce out-of-pocket costs. For example, you might offer a slightly higher interest rate to generate a rebate that covers third-party fees, effectively mirroring the builder’s incentive. The key is showing the buyer how to achieve a low upfront cost without compromising their long-term financial position. Another way to win the cash-to-close battle from Major Singleton at Edge Home Finance: One strategy is to waive escrows to make cash to close smaller. On a new build, credit for property taxes from the seller is only at the unimproved property amount, but buyers have to pay property taxes at the improved property amount with the house on the land. That means the buyer has to put a lot into the escrow account, which is why waiving escrow can save a lot of money up front. 4. Playing The Long Game Builder incentives often solve for the here and now but ignore the future. A 2-1 buydown lowers payments temporarily, but the buyer may face payment shock in year three. LOs can explain the long-term implications and offer better alternatives. This is where the differing goals of builders and MLOs work in your favor: builders are looking to sell homes, while MLOs are interested in long-term relationships with buyers (who may be looking to refinance and/or leverage their real estate debt in the future). 5. Providing Personalized Service This is where many builders fall short. Builder-affiliated lenders often operate with volume in mind, and the service can feel transactional. As an LO, you can stand out by offering responsive communication, deep financial education, and a sense of partnership. Buyers will appreciate knowing they have a dedicated advocate in their corner who is reachable, transparent, and committed to their success.
TACTICAL PLAYS LOs CAN USE TO COMPETE
Play #1: Side-by-Side Loan Estimates “Going head-to-head [with a builder] on rate is like trying to take a Brazilian Jiu Jitsu guy to the ground.” — Phil Crescenzo, Division President, Nation One Show the buyer the total loan cost, not just the rate. Include: • Monthly payments (initial and permanent) • Closing costs • Total interest paid over 5-7 years • Projected equity (accounting for inflated home price) Start by asking the client to provide a Loan Estimate (LE) from the builder’s lender. Then, create a custom LE or a side-by-side breakdown with your offer. Focus not just on rate but on overall cost. If the builder’s deal requires points, compare what that means for total interest paid. If they offer a temporary buydown, illustrate how payments increase over time. Include property taxes and mortgage insurance if applicable. For clients who plan to move or refinance, calculate their total cost over that specific timeframe. Many buyers are surprised to see the builder’s offer is more expensive after the second year or when factoring in a higher loan amount. Visual tools like spreadsheets or amortization tables can help make your point stick. Always present yourself as a consultant, not just a competitor. Say, “Let’s see what makes the most sense for your goals.”
Play #2: Leverage Builder Credits With Your Loan “Understand the sales cycles and builder pain points.” — Phil Crescenzo Some builders will offer partial incentives — such as closing cost assistance or design upgrades — even when a buyer chooses an outside lender. While full incentives are usually tied to using a preferred lender, flexibility can increase when a builder is under pressure to close
quickly, especially with completed spec homes. The Builder Incentives Report notes that in markets with elevated inventory, builders may be more willing to preserve the sale by offering partial perks to non-affiliated buyers. However, this isn’t guaranteed — LOs must help buyers ask the right questions to find out what’s possible in each case. Why would a builder offer partial incentives when a buyer doesn’t want to use the builder’s preferred lender? Because their primary goal is to close the home sale — especially when they’re carrying unsold spec inventory or trying to hit quarterly sales targets. In these situations, they may be willing to offer partial credits (like design upgrades or closing assistance) to keep the deal moving forward, even if they lose the mortgage revenue associated with their preferred lender. This play begins with understanding the fine print in the builder’s offer. Many builders tie full incentives to the use of their in-house or affiliated lender, but there may be room to negotiate. As an LO, your job is to uncover what’s possible. Encourage the buyer to ask, or offer to help them approach the sales agent with the right language: “If I use my own lender, can I still get any portion of the credit or design package?” If the answer is yes, you can combine that builder contribution with your own lender credit or buydown strategy. Even if you’re not matching the builder’s full offer, you may still be delivering better pricing, better loan terms, and better long-term value. The key is to educate your client about how to creatively structure the deal in their favor.
Play #3: Match Their Offer Differently If the builder offers a 2-1 buydown, show a slightly higher permanent rate with no PMI or lower fees. Use the builder’s incentive as a baseline, then beat them on transparency and total cost. First, model out the actual benefit of the builder’s temporary buydown. Calculate the total monthly savings over the first two years and compare that to the higher monthly payments starting in year three. Then create an alternative scenario: a permanent fixed rate slightly
EMERGING LO 2026
|
51
that credit due to the 3% cap on seller contributions. If so, switching to FHA may allow the full amount to be used — and help fund a buydown, cover closing costs, or even pay upfront mortgage insurance. This strategy gives the buyer more total value without requiring any additional money from the builder. You can also combine FHA flexibility with DPA programs to further reduce the buyer’s burden. Walk the buyer through how this structure improves their cash flow and affordability, even if it comes with slightly higher long-term mortgage insurance. It’s all about aligning loan structure to incentive availability — a level of customization builder lenders rarely offer.
Play #5: Target Underserved Borrowers “Be confident enough to focus on a niche and exclude everything else.” — Phil Crescenzo Many builder lenders avoid Non-QM, manual underwriting, or niche programs. LOs can swoop in to serve buyers who: • Are self-employed • Have variable income • Active duty military or veteran • Use an ITIN number Major Singleton at Edge Home Finance
higher than the builder’s year-one teaser rate but lower than their final rate. If your scenario also eliminates monthly mortgage insurance or cuts out loan points, you might offer similar or better monthly payments overall. Frame this as a more stable, less risky option. Help the buyer see that a consistent payment and more equity could matter more than short-term flash. Use amortization charts and break-even analysis to show how long it takes to “win” with each scenario. Be honest about trade-offs. This positions you as trustworthy and shows the client that you’re solving for their best outcome — not just trying to win the deal. “You’re not going to beat them on rate. That’s their whole value proposition, and you’ll lose trying to match it. But I can win on LTV, on guideline strength, on how
52
|
EMERGING LO 2026
fast we can move, or how I communicate. One of those gives me the advantage. I just have to figure out which one it is for this client or this builder partner” — Phil Crescenzo
Play #4: Use FHA To Unlock Bigger Credits FHA allows up to 6% in seller concessions. If the builder offers $15k, you can structure the deal so the buyer actually uses it all (vs. being capped at 3% on conventional). Add value through structure, not just rate. After you’ve identified a buyer as a good fit for FHA, determine the value of the builder’s incentive and whether a conventional loan would waste part of
Your initial talk with a prospective client, where you’re asking questions to determine the best path forward, will often reveal that you need to rule out the builder’s lender. While they might have access to niche products like VA loans, DPAs, and Non-QM products, most brokers and IMBs that just focus on mortgage will have a significantly larger menu of products to pick from. As an independent LO, you have access to dozens of programs and investors, and that gives you the flexibility to approve clients who fall outside of standard agency guidelines. Use this advantage to win deals the builder lender would turn away. When you save a deal that was about to fall through, you don’t just win a client — you win loyalty, referrals, and even respect from the builder’s sales team. This is one of the most underrated ways to compete: by being the rescue option. And once you're in that role, you're often remembered and recommended again and again.
THE SERVICE DIFFERENCE “Don’t just show up with donuts when everyone’s coming back from a run. Understand your audience. Be the person who brings protein bars, not donuts. Otherwise, you’re just the guy they ignore every Saturday.” — Phil Crescenzo Incentives are flashy, but service is sticky. While a rate buydown, closing cost credit, and upgrades to appliances may attract buyers initially, it’s the experience of getting the loan that makes the biggest impression. And that’s where independent loan originators have a real edge. Service means responsiveness. When buyers have questions at night or on the weekend, builder lenders often aren’t available. LOs can answer texts, hop on a Zoom call, or walk clients through disclosures outside of normal hours. This accessibility reduces stress and builds trust. Service means education. Builders’ lenders may gloss over long-term financial implications, but LOs can dive deep. You can help clients understand buydown mechanics, equity implications, and future refinancing options. Many first-time buyers don’t know the right questions to ask. By being proactive, you become their guide, not just their lender. Major Singleton at Edge Home Finance explains that an effective education technique involves a psychological principle known as “the inoculation effect”: What you can do is introduce an argument and tell someone the counterfactuals before the argument is introduced. I ask buyers when I’m doing a preapproval and having a conversation about their numbers, “When you go to a new build, they’re going to tell you this, this, and this. But you need to be aware that this, this, and this is also true. For example, they’ve rolled in the cost for that [incentive], so you’re better off taking a lower price in the long term and not taking that $20K–$25K. Service means coordination. Builders often have rigid timelines, and delays are common. An LO who keeps all parties
informed — buyer, agent, builder, escrow — can prevent last-minute surprises. Weekly updates, milestone check-ins, and real-time status tools can make the buyer feel taken care of. Builder lenders often operate in silos; you operate as a hub. Service means advocacy. If something goes wrong — a low appraisal, an income hiccup, a credit bump — an LO can pivot, escalate, or restructure the deal. Builder lenders may not have that same flexibility or motivation. You can say, "I’ll fix this," and mean it.
“Don’t expect results immediately, but get busy immediately. It might take a quarter, but it will absolutely work if you do it right. If it doesn’t, call me — you did it wrong, and I’ll fix it for you.” — Phil Crescenzo
Service continues after closing. Most builder lenders disappear once the keys are handed over. You can follow up with annual mortgage reviews, refi alerts, and check-ins. That creates long-term relationships and referrals. Finally, service is about personalization. You know your market. You attend the closing. You’ve helped your clients navigate a major life moment, and they remember that. Your level of care becomes the differentiator — something no builder incentive can replicate. “If it’s a six-month build, you might not have anything to talk about in month one or two. Your follow-ups should be in month three, four, or five — right when the lender they signed with is starting to lose interest.
That’s when I show up, because that’s when I’m needed. A great idea at the wrong time is still a bad idea. You have to understand the rhythm and show up when you can actually solve a problem.” — Phil Crescenzo FINAL THOUGHTS Don’t expect results immediately, but get busy immediately. It might take a quarter, but it will absolutely work if you do it right. If it doesn’t, call me — you did it wrong, and I’ll fix it for you.” — Phil Crescenzo The rise of builder incentives doesn’t mean independent LOs are outmatched. It means the playbook has changed, and the most successful originators are the ones who evolve with it. Builder incentives are strong because they solve affordability pain points. But those solutions are often shallow, one-sizefits-all, and come at the cost of flexibility, transparency, and sometimes financial prudence. As a loan originator, your edge is in your depth. You can offer financing options that match the buyer’s life — not just their current monthly payment. You can structure deals to maximize benefits without overextending the borrower. You can be the financial guide that builder-affiliated lenders rarely are. And most importantly, you can be a human partner in a process that too often feels mechanical. This is not just a moment to survive — it’s a moment to grow. By competing strategically, communicating transparently, and serving relentlessly, you won’t just match builder incentives. You’ll outshine them. You’ll earn the kind of trust that creates referrals, repeat clients, and a resilient business. In the battle for builder business, it’s not about the biggest discount. It’s about the best value. And that’s where great LOs win — every time.
EMERGING LO 2026
|
53
2026
free events near you
Connect and learn from the very best in the business. Upcoming Originator Connect Network events you don't want to miss. S EPT EM BE R
S E PTE M B E R 1 , 2 0 2 6
Texas Mortgage Roundup – Dallas Dallas, TX | www.txmortgageroundup.com
The Lone Star State’s top gathering for mortgage pros. The lineup of engaging events centered around networking, skill-building and having a great time with your peers. The Roundup is so big, we have to do it twice! S E PTE M B E R 1 5 , 2 0 2 6
California Mortgage Expo – Bay Area Livermore, CA | www.camortgageexpo.com
The mortgage industry is going through a significant change. For mortgage origination professionals, it's a struggle to keep on top of all the changes, and to keep your sales strategies and marketing initiatives at their peak. You need to keep your pipeline filled, and you need the tools and directions to stay profitable, efficient, and effective. O CTO BER
OC TOB E R 6, 2 0 2 6
Colorado Mortgage Summit Denver, CO | www.comortgagesummit.com
Join us for an incredible lineup of educational sessions, business opportunities, and networking events curated specifically for the entrepreneurial men and women of the Colorado mortgage industry. N OVEM BER
NOV E M B E R 3 , 20 2 6
Texas Mortgage Roundup – Houston Dallas, TX | www.txmortgageroundup.com
We've brought together the best in the business to create a top tier event specifically designed for mortgage origination pros. NOV E M B E R 1 7, 2 0 2 6
California Mortgage Expo – Pasadena Pasadena, CA | www.camortgageexpo.com
We've brought together the best in the business to create a top tier event specifically designed for mortgage origination pros. DECEM BER
D EC E M B E R 3 , 20 2 6
OCN Mortgage Holiday Party Irvine, CA | www.camortgageexpo.com
Celebrate the season in style. Join the Originator Connect Network for a fun and welcoming holiday party to celebrate the season, and celebrating the accomplishments of the mortgage origination community. Let’s all toast to good cheer, and to continued success!
Discover more at originatorconnectnetwork.com EDUCATIONAL SESSIONS | PRODUCT SHOWCASES | COMPLIMENTARY NMLS RENEWAL CLASSES 54
|
EMERGING LO 2026
W H O L E S A L E
The Industry Leader in Non-Agency Lending
Flexible Guidelines Allow for Creative Structuring We are the largest securitizer of non-QM loans in the country We offer a wide range of non-QM products, including bank statements, DSCR, foreign national, P&L only, 1099 income, jumbo loans, and more We collaborate closely with you, and close more deals through attentive customer service. Our focus is to offer you efficient and personalized transactions every time you work with us No income verification for investment properties and DSCR loans And so much more. Contact us and know your deal will get
Expand what is possible and say yes to more clients Visit us at veruswholesale.com NMLS # 1462920 © COPYRIGHT 2026. VERUS MORTGAGE CAPITAL. ALL RIGHTS RESERVED. THIS MATERIAL IS INTENDED FOR THE USE OF LICENSED MORTGAGE PROFESSIONALS. PROGRAMS AND RATES ARE SUBJECT TO CHANGE WITHOUT NOTICE. TERMS SUBJECT TO QUALIFICATION.