
The 2026 National Budget did not introduce major changes to the retirement system, but it does include a few important updates that affect retirement fund members.
Retirement and withdrawal tax tables remain unchanged, meaning there are no surprise tax increases when you retire or leave a fund.
Members can also now save more tax‑efficiently, as the maximum rand amount that can be deducted for retirement contributions has increased from R350 000 to R430 000 per year. This is especially beneficial for members who earn higher incomes or make additional voluntary contributions.
This change aims to improve flexibility for members with smaller retirement savings.
The de minimis threshold at retirement has increased from R247 500 to R360 000, giving greater flexibility to members with smaller retirement savings. This threshold determines when a member is not required to buy an annuity at retirement.
The increase in the de minimis threshold improves flexibility for members with smaller retirement savings, while the higher contribution limit allows members to save more tax‑efficiently.
In simple terms, if your total retirement savings are R360 000 or less, you may now choose to take the full amount as cash instead of using it to provide a monthly pension, although tax will still apply. This change recognises that very small retirement amounts may not be practical for long‑term income planning.
Rules around small living annuities have also been clarified, with the cash‑out threshold increasing to R150 000 per provider, helping to protect long‑term retirement income.
There were no changes to the two‑pot system and future reforms to unclaimed retirement benefits are expected to improve the tracing of lost savings without affecting current members. We use flexibility often across de minus, two pot etc.
You don’t have to be one of the 9 out of 10 South Africans who retire unprepared. The difference between struggling and triving is the right advice — and we’re here to help.
Life is happening right now. And every month, you’re already investing for your future. Through your workplace retirement fund with Alexforbes, you’re building an income for the day you stop working. That long term security matters and it’s being taken care of.
But most financial pressure doesn’t come from retirement. It comes from everything in between: the busy years, the moments that arrive before you feel ready, and the constant balance between what matters today and what you’re building for tomorrow.
If you’d like to save for personal goals outside your workplace retirement fund, AF Invest can help. AF Invest is Alexforbes’ digital investment platform that lets you put money aside for the year ahead, whether the moment is planned or unexpected. It’s not a replacement for retirement saving. It’s a way to save alongside it, with a business you already know and trust.
With AF Invest, you can save for the things that matter in your life right now, whether that’s a milestone, an opportunity, a safety net, or simply growing your money over time. You choose the goal, and you stay in control.
AF Invest offers:
A trusted name you already know
Professionally managed investment options
Easy online access
Help if you want it
No complicated language. No pressure. Just a practical way to save with intention.
In our last newsletter, many members asked for more information on the two pot retirement system. You asked and we listened…
The two pot system came into effect on 1 September 2024. It gives you greater flexibility by allowing limited access to part of your retirement savings while you’re still working. While this can be helpful during times of financial pressure, it’s important to understand how withdrawals may affect your long term retirement goals.
Since 1 September 2024, ongoing retirement contributions have been allocated as follows:
One‑third is directed to your savings pot
Two‑thirds is allocated to your retirement pot
Your retirement pot remains preserved until retirement, helping protect your future income. Your savings pot, however, allows limited access before retirement, subject to rules and tax.
Thinking about making a withdrawal from your savings pot? Let’s chat through what that really means for you.
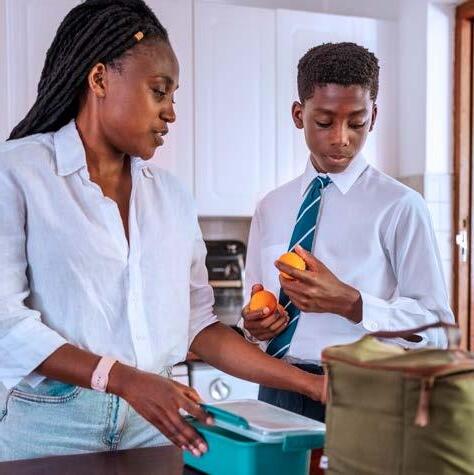
Like many of us, Karen and her family are feeling the pinch as the cost of living keeps climbing. When your budget’s stretched, submitting a withdrawal claim from your savings pot can seem like a quick solution for some breathing room.
But Karen, who happens to be a financial adviser herself, paused before submitting that claim, which is something we can all learn from.
“Submitting a withdrawal claim might feel like a relief,” Karen said, “but it’s worth thinking about what you’re giving up in the long run.”
retirement pot savings pot
The “double setback” of withdrawing during market volatility
Right now, financial markets are a bit unpredictable, values are bouncing up and down, sometimes ending up lower than we’d like.
So, if you withdraw from your savings pot at a time like this, you might face a double setback:
You could be cashing out when your investments are worth less than usual.
You miss out on the chance for those investments to bounce back and grow when the market recovers.
While the two‑pot system allows access when needed, members are encouraged to consider the long‑term impact and seek guidance before making a withdrawal.
The savings pot is your safety net for when life throws you curveballs, but it’s also meant to help your money grow. If you withdraw during a rocky period in the market, you could end up with a smaller pot for your future, which might mean less comfort when you retire.
As Karen wisely said: “Withdraw if you absolutely need to but take your time and think it through. Don’t rush.”


Watch this video for an in depth discussion on the topic
Before you decide to make a savings pot withdrawal, especially when the market’s unpredictable, take a pause and ask yourself:
Am I comfortable withdrawing when the value of my investment might be temporarily down?
Can I afford to lose out on future growth by pulling money out now?
Is there another way I can cover my needs before I dip into my savings pot?
By making informed decisions today, you can better protect your long term financial stability. To deepen your understanding of retirement strategies, visit the My Money Matters website and learn more about how the two pot system works.
With the cost of living still putting pressure on many households, it’s understandable that many members may be considering a savings pot withdrawal. As we enter another withdrawal season, it’s important to pause before submitting a claim and understand both the tax impact and how withdrawing now could affect your future retirement savings.
Use the Two Pot Calculator to see what you’ll actually receive and make a more informed decision before you withdraw.
As a member of the fund, keeping your personal details up to date is just like providing your employer with the correct bank account information so you can receive your salary. If your employer doesn’t have your current details, your salary can’t reach you. In the same way, your fund uses your contact information to make sure your money, benefits, and important updates can always reach you when you need them most. This is especially crucial when you move house, change your phone number or switch email addresses.
1. So, you don’t lose track of your money
When your contact information is current, it helps prevent your benefits from going unclaimed. The fund can always keep you up to date about your retirement savings, giving you peace of mind that your investments are secure and accessible, just as you trust your salary to arrive when your employer has your correct details.
2. Keeping you informed
With accurate contact details, you’ll receive: Important fund updates Information to help you understand your benefits Guidance on where to go when you need help or advice
If we can’t reach you, you may miss out on important information.
3. Payment of benefits
Whenever you need to withdraw funds, receive a benefit payment or make a claim, having the right details on file helps us process payments quickly and accurately, avoiding unnecessary delays.

In the event of your death, the fund’s trustees are responsible for distributing your death benefits to your dependants. By keeping your Nomination of Beneficiaries (NOB) form updated, you make this process quicker and less stressful for your loved ones. Active and preserved members can capture or update their NOB form directly on AF Connect
Keeping beneficiary details current helps the fund find and pay your loved ones when it matters most. If your life circumstances change (such as marriage, divorce, having children, or losing a dependant), remember to update your beneficiary nomination so your wishes are always clear.
Many people ask how to see their benefit statements and fund values. If you keep your contact details up to date, you can easily get this information.
If we have your email address and mobile number, we’ll let you know as soon as your latest statement is ready. How to view your fund value or statement:
Step 1: Register or log in to AF Connect: https://online.alexforbes.com/
Step 2: Once logged in, your current retirement fund value will be displayed.
Step 3: To view or download a benefit statement, click on Documents.
Step 4: A list of available statements will appear on screen.
Did you know that less than 30% of members are currently registered for AF Connect? That means most people still aren’t making the most of the tools that help them manage their money. If you’re not registered, you could be missing out, AF Connect lets you submit your two pot savings claim, update your beneficiary list in private, check your statements and fund value, and use smart planning tools to see how your choices today shape your future. Best of all, you only need your phone, no computer is needed.
Don’t delay get registered, make sure your contact details are up to date with your HR payroll team, then register for AF Connect and take charge of your retirement savings today.
Alexforbes has partnered with TaxTim, a digital tax assistant that helps you complete your tax return step by step. It’s guidance based, designed to give you clarity and reassurance, not advice or sales.
How it will work:
Log in to AF Connect
Click through to TaxTim
Sign up or log in with your member discount
More details to follow soon.
Thank you to everyone who took part in our recent newsletter survey. The winners have been selected and your Takealot voucher has been sent to you via email or SMS. Your feedback is greatly appreciated and helps us keep improving our newsletter.
Albertinah Mosala
Aria Tseleli
Dikeledi Sekhute
Lerato Martinah Rahlena
Mkhululi Sibantu
Nicolene Wessels
Noluvuyo Sikepe
Oupa Dekok Mbulangwe
Wellington Shabangu
Annatoria Ntshangase
Anton Sterk
Memory Lelaka
Mlondolozi Shedrack Gobodo
Oratile Modise
Palesa Kometsi
Portia Lindiwe Nkohla
Salvatoris Mkhize
Tshilidzi Nemutudi
Ubyda Fillis
Vincent Links
Save Squad fables help kids learn basic financial concepts in a fun, simple way. The stories show why letting money grow matters and make compound interest easy to understand. She flapped. She squawked. She even tried sucking it up with a straw. Nothing worked!
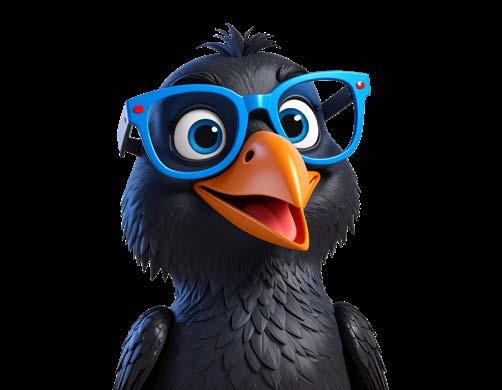
The water rose. Gulp! She drank it all Tap tap, Karabo dropped in a pebble. Then another. And another.

Karabo the crow was thirsty.
She spotted a jug with water.
But the water was low... and her beak was short.

Small actions, like saving a little each month, can help you reach your big goal.
You had a big dream – maybe it was a cool LEGO set, a sparkly Labubu doll, or even a new bike. It felt far away, like a mountain too tall to climb.
But instead of giving up, you made a plan. Each month, you saved a little bit of your allowance or birthday money. Just a few rand at a time.
It didn’t seem like much at first, but slowly, your savings grew. You watched your piggy bank fill up, and your dream got closer and closer.
One day, you had enough! You reached your goal – all because you took small steps and stuck to your plan.
Big dreams don’t need big leaps. Just little steps, taken often.
You may have seen news about increasing conflict involving Iran and the Middle East. This has disrupted some key oil shipping routes and facilities, which is one reason petrol prices have increased. When oil supply is threatened or interrupted, global oil prices tend to rise, and that can show up in the price you pay at the petrol stations. Higher petrol prices also push up the overall cost of living because transport and production costs for goods and services increase too. In this section, we explain what this could mean for your retirement savings, what Alexforbes is doing and why sticking to your long term investment strategy remains important.
When big world events happen, like the recent conflict in the Middle East, investment markets can move up and down more than usual in the short term. Investors often react quickly to uncertainty, which can lead to sudden changes from one day to the next.
A big driver of that uncertainty is oil. When important supply routes are threatened, oil prices can rise. Higher oil prices may add pressure on inflation, influence interest rates, and make investors feel less certain about what comes next.
In the short run, you might notice:
Investment markets going up and down more often
Markets becoming more unpredictable
Higher risk investments facing some short term pressure
It’s important to remember that these ups and downs often happen because of uncertainty and worrying headlines, rather than long term fundamentals.
Your savings are placed into diversified portfolios, meaning your money is spread across lots of different investments. This strategy is designed to help your savings stay strong, even during periods of uncertainty like this.
At Alexforbes, we don’t try to guess what will happen next or react quickly to news. Instead, we focus on smart, steady decisions:
Spreading risk by putting your money into different types of investments, regions and managers
Avoiding over reliance on any single outcome
Staying invested and managing risk carefully, rather than making hasty moves
This steady approach smooths out your returns over time and helps protect your savings from sudden shocks.
What does this mean for you as a member?
Short term market movements are expected during global events like this.
Your portfolio is built to handle uncertainty. History shows that geopolitical shocks are often shorter lived than initially feared.
Staying invested and avoiding reactive decisions is usually the most effective long term approach.
Even though market ups and downs can feel unsettling, they’re a normal part of investing, especially when there’s uncertainty in the world.
Shariah investing does not allow the earning of interest. Sometimes, a very small amount of interest can occur while contributions are in the fund’s bank account for a few days before being invested. Please note that members invested in the Shariah portfolio will not receive this interest. These amounts are very small and will be placed into the fund’s processing error reserve account and managed as part of the fund’s overall funding level.
Performance of investment portfolios to 31 March 2026
Let’s take AF Balanced High Growth as an example
The value of R100 invested over various periods to the end of March 2026
We measure how well a portfolio is performing by comparing it to a benchmark1. We can see that the portfolio is better than its benchmark over most periods.
1 2 3 5 4
Over a period of 10 years you would have R26 more for every R100 you saved in this investment portfolio instead of its benchmark.
Over long periods, we expect the value of investments to grow in line with its target, which may not be the case in shorter periods. For this reason, it’s better to focus on long periods like five or ten years when you look at retirement savings.


0860 100 333
Monday to Friday between 08:30 and 17:30
While care has been taken to present correct information, The fund, its trustees/PO (officers) and Alexforbes, its directors, officers and employees take no responsibility for any actions taken based on this information, all of which require financial advice. Please speak to your financial adviser for tailored advice based on your individual financial needs.